

Buy
BHP is a diversified resources company that mines copper, iron ore, metallurgical coal and is building a potash project, and it is listed on the ASX.
Institutional sell-side research rates it Buy because strong cash flow and a solid balance sheet support a 60 per cent payout ratio through the FY27 production dip, with net debt expected to stay below US$10 billion. It also points to a copper pipeline of about US$50 billion that could lift equity copper production to about 1.8Mt from FY35. Pilbara and Escondida margins fund both growth and a fully franked dividend.
- Sell-side rating
- Buy
- Sell-side target
- A$65.70
- Upside to target
- +20.9%
- Initial price
- A$57.562 Nov 2026
- Last close
- A$54.3418 Nov 2026
BHP‘s copper production, the part of the business the market most wants to see grow, came in well short of expectations in the September quarter after a cluster of maintenance, weather and operating setbacks in Chile and South Australia. Iron ore and coal made up for it, with the Western Australian iron ore business setting September quarter records at both mine and port, coal output beating expectations and strong realised prices for copper and metallurgical coal. All FY27 production and unit cost guidance was also left unchanged. Institutional sell-side research has BHP rated Buy with a 12 month price target of A$65.70, about 14.1 per cent above the share price of A$57.56 when this research was published. The shares also have a trailing dividend yield of 4.2 per cent, fully franked, and BHP has a copper growth pipeline of about US$50 billion still to come through.
Research published 2 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About BHP
BHP is a diversified resources company listed on the ASX under the code BHP, with a financial year ending in June. The financial figures in this piece are in US dollars unless marked A$. Copper is its main growth commodity, produced at Escondida and Spence in Chile, through Copper South Australia, which includes Olympic Dam and Carrapateena, and through its interest in Antamina. Its iron ore business, known as WAIO, operates in the Pilbara. In coal it runs BMA, a metallurgical coal business, and NSW Energy Coal. BHP is also building the Jansen potash project, with first potash expected in mid-calendar 2027. Further copper options include Vicuna in Argentina, a joint venture with Lundin Mining, and the Resolution project. In Arizona, BHP sold its San Manuel property to Faraday Copper for shares, lifting its stake in Faraday to about 32 per cent.
Copper Fell Short in a Disrupted Quarter
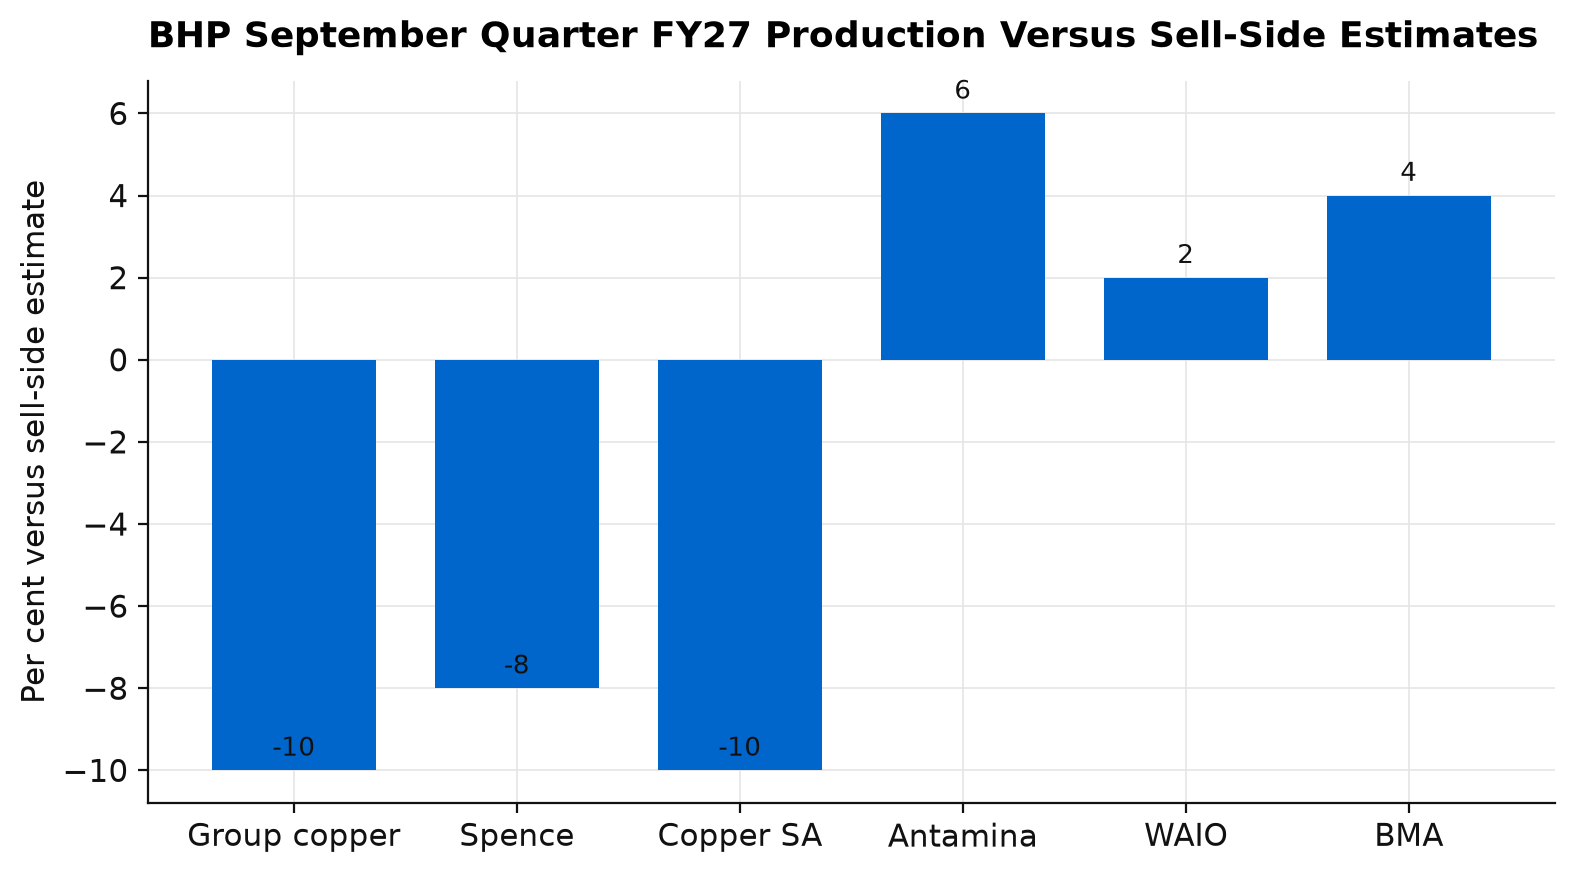
Group copper production was about 401kt in the September quarter, where kt means thousand tonnes. That was around 10 per cent below institutional sell-side estimates and 5 per cent below market consensus, the average forecast across analysts covering the stock. Scheduled maintenance, severe weather in Chile, a conveyor failure at Carrapateena and safety stoppages all hit in the same three months, giving a weak start to the year in copper, BHP’s main source of long-term growth. BHP still kept its FY27 copper guidance unchanged.
Escondida accounted for most of the miss. It produced about 253kt, against a sell-side estimate of about 289kt. The shortfall came from lower throughput, meaning the amount of ore pushed through the processing plant, which fell to about 31.4Mt, where Mt means million tonnes, down 14 per cent on the same quarter last year. The grade of ore going into the concentrator was better than expected, at 0.81 per cent copper against a forecast of 0.78 per cent. Volumes were held back by scheduled maintenance, by severe weather in July and August, and by a temporary suspension of mining after a fatality at the site on 23 September. Against that, cathode production, which is copper recovered by leaching ore, rose 18 per cent to about 55 thousand tonnes as recoveries from the Full SaL and sulphide leach operations kept improving.
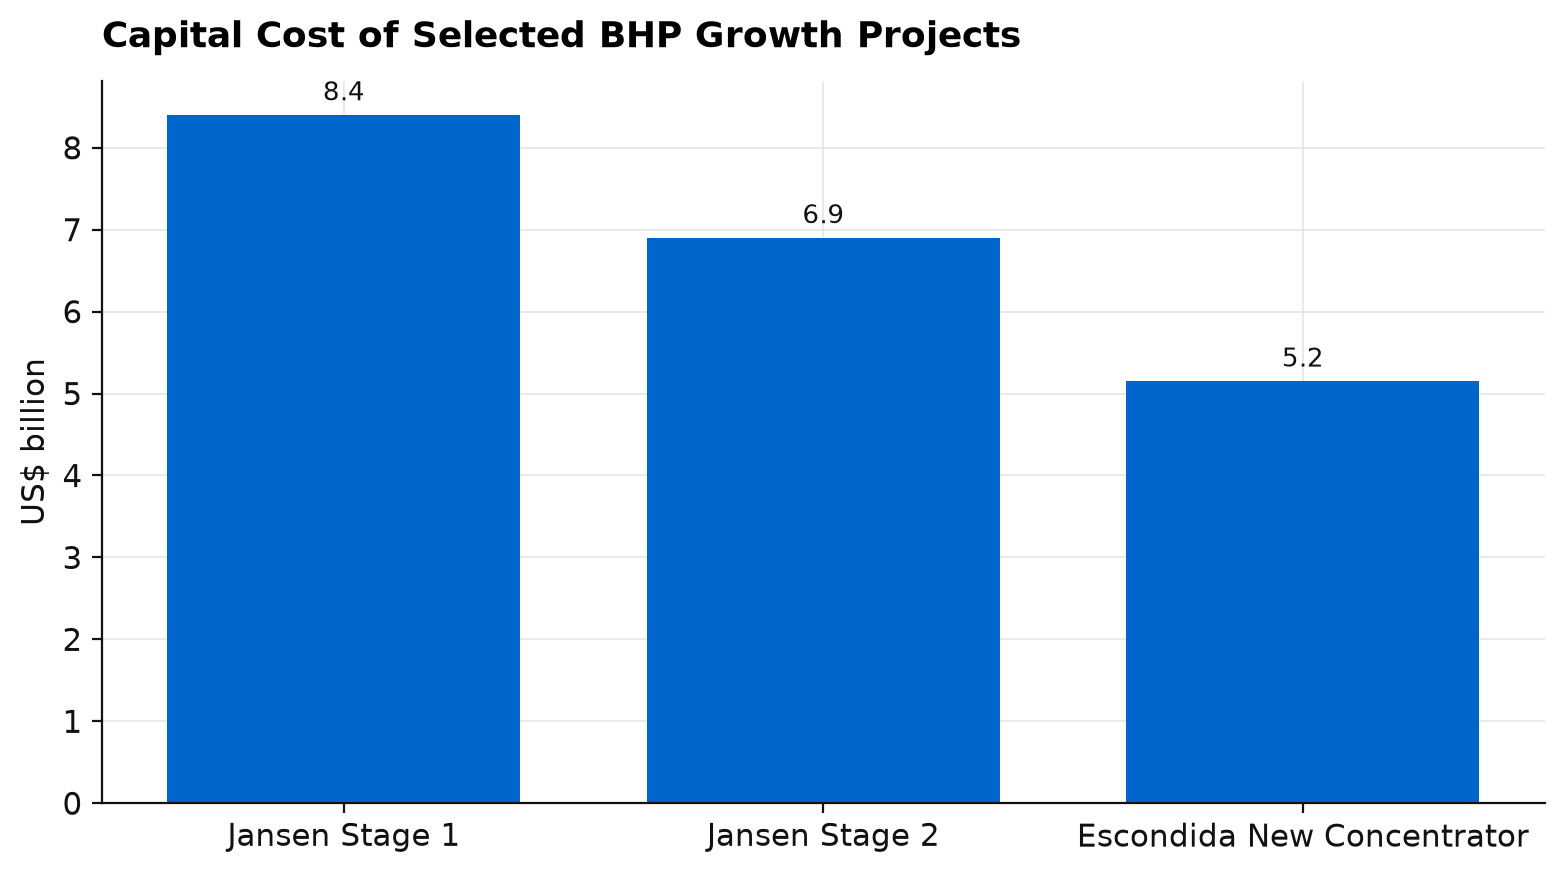
BHP also approved US$0.8 billion of pre-commitment funding at Escondida, on a 100 per cent basis, meaning for the whole mine including its partners’ shares, for engineering, permitting and execution readiness on the Escondida New Concentrator. The proposal is for a plant of about 157ktpd, or thousand tonnes per day, at a cost of US$5.15 billion. Institutional sell-side research expects a final investment decision in the first half of calendar 2027 and first ramp-up around mid-2030. Separately, a new collective agreement with Escondida’s Union N°2 of Supervisors was signed and took effect for 36 months from 14 October 2026.
Spence produced about 47.4kt, 8 per cent below sell-side estimates, on a lower planned feed grade and ongoing problems with variable, clay-affected ore. Its guidance of 210-230kt for the year is unchanged but weighted to the second half. BHP has also signed a memorandum of understanding with KGHM, the 55 per cent owner of Sierra Gorda, to explore technical, exploration and development synergies with Sierra Gorda. Sell-side research includes no benefit from this in its base case but estimates the key potential synergies at US$2-4 billion. Copper South Australia produced about 60.7 thousand tonnes, 10 per cent below both sell-side estimates and consensus. The shortfall reflected a seven-week belt outage at Carrapateena, now back at full capacity after a progressive ramp-up through September, and a planned build of anode inventory at Olympic Dam ahead of a smelter maintenance campaign scheduled for the first half of FY28. Antamina outperformed, producing about 40 thousand tonnes, 6 per cent above sell-side estimates and 18 per cent above consensus, although its zinc output fell 70 per cent on the same quarter last year because of planned lower grades.
Strong copper prices made up part of the shortfall, with BHP receiving about US$7.0 per pound and provisional pricing adding to that. Copper is often sold at a provisional price that is later settled against the market price, so when prices rise after a shipment the company books a gain. The company also released updated Mineral Resources for the Olympic Dam block cave, a style of underground mining where ore is undercut and allowed to break up under its own weight, ahead of a Copper South Australia site visit the company has scheduled for November.
Record Iron Ore and Stronger Coal Output
WAIO, the iron ore business, produced about 71.9Mt on a 100 per cent basis, roughly 2 per cent ahead of sell-side estimates and a September quarter record at both mine and port, even with heavy maintenance during the quarter. The rebuild of Car Dumper 4, one of the machines that tip ore out of rail wagons at port, cost about 1.4 million tonnes of output. That rebuild is around 40 per cent complete and on schedule to finish in the first half of FY27.
The sixth car dumper, CD6, is on track for the fourth quarter of FY28, and the Western Ridge Crusher is due to deliver first ore in the first half of FY27. WAIO is targeting more than 305 million tonnes a year by the end of FY28. Iron ore prices were weaker, with BHP realising about US$76.3 per tonne on a free on board basis, meaning the price at the port before shipping. That was 9 per cent lower than a year earlier, in line with a weaker benchmark price for ore of 61 per cent iron content and affected by elevated freight.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARIn coal, BMA produced about 4.9Mt, 4 per cent ahead of sell-side estimates and 1 per cent ahead of consensus, on better operating performance and mine sequencing, despite a stoppage at Peak Downs. A longwall move at Broadmeadow, where the large underground cutting machine is shifted to a new section of the coal seam, is scheduled for late in the second quarter of FY27. NSW Energy Coal produced 4.4 million tonnes, ahead of expectations, helped by higher bypass coal, which is coal that can be sold without going through the wash plant, and the early completion of wash plant maintenance. Its production is expected to be weighted to the first half. Realised metallurgical coal prices were strong at about US$243 per tonne.
Institutional sell-side research sees BHP’s near-term cash flow and balance sheet as strong. Capital spending is running at about US$11 billion, yet with all of its copper growth projects included, BHP’s net debt, meaning borrowings less cash, should stay below US$10 billion, well within the company’s own net debt ceiling of US$20 billion. The recent completion of a US$4.3 billion silver streaming deal, where a buyer pays cash upfront in return for a share of future silver output, has strengthened the balance sheet further, and a US$2 billion Pilbara power sale is expected in the first half of FY27. With strong iron ore and copper prices, sell-side research thinks BHP can maintain a 60 per cent payout ratio, the share of profit paid out as dividends, through the forecast production dip in FY27, and fund its growth pipeline from cash flow, recycling capital from infrastructure if needed.
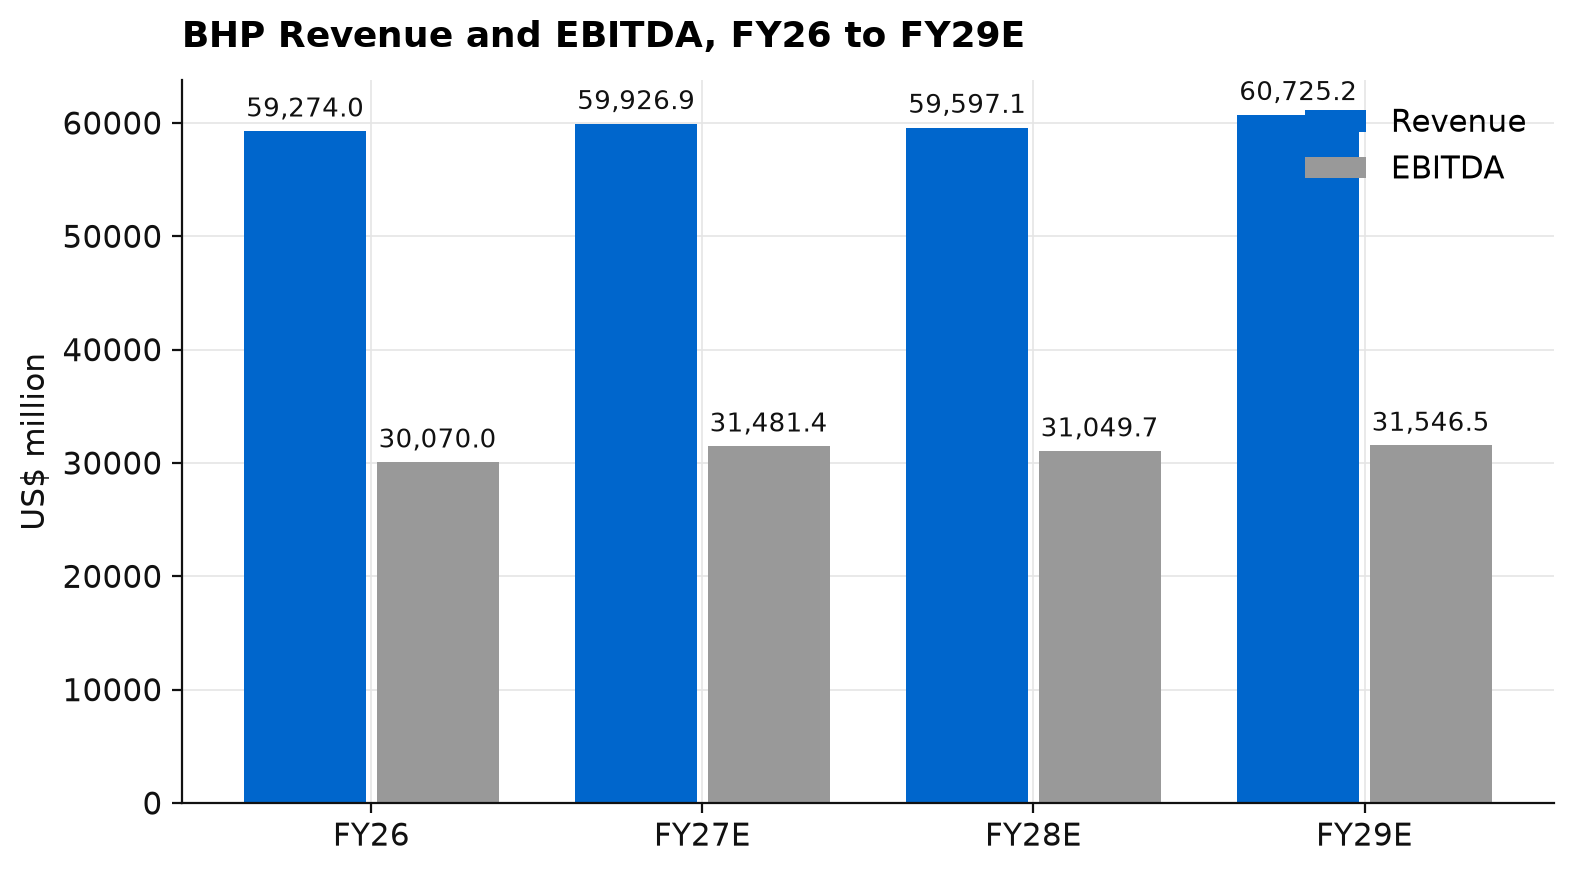
Revenue was US$59,274 million in FY26, and sell-side research forecasts US$59,926.9 million in FY27, US$59,597.1 million in FY28 and US$60,725.2 million in FY29. EBITDA, which is earnings before interest, tax, depreciation and amortisation and a rough measure of operating cash profit, was US$30,070 million in FY26 and is forecast at US$31,481.4 million, US$31,049.7 million and US$31,546.5 million over the same three years. After this result, sell-side research left its FY27 EBITDA estimate unchanged and lifted FY28 and FY29 by 1 per cent each, after realigning to guidance and remodelling the internal concentrate transfer from Copper South Australia to Olympic Dam. For income investors, BHP has paid about A$2.42 per share in dividends over the past twelve months, a trailing yield of 4.2 per cent at A$57.56, fully franked. Fully franked means company tax has already been paid on those profits, and the attached franking credits can reduce the tax an Australian shareholder, including an SMSF, pays on the dividend.
Copper and Potash Projects Drive Longer-Term Growth
Institutional sell-side research sees BHP’s major opportunity as growing copper production through a pipeline of about US$50 billion of projects. These include Escondida and Spence in Chile, Vicuna in Argentina, which is the Josemaria and Filo del Sol joint venture with Lundin Mining, Copper South Australia Phase 1, and Resolution. In South Australia the ambition is an expansion of Copper South Australia to about 500 thousand tonnes a year. Folding the Olympic Dam block cave into its base case has lifted sell-side forecasts of BHP’s consolidated copper production, the full output of operations it controls, to about 2.3Mt by FY35.
Counting only BHP’s ownership share, known as equity production, sell-side research forecasts copper output rising from 1.2Mt in FY28 to about 1.8Mt from FY35. BHP itself is targeting copper production growth of about 3-4 per cent a year, compounded, between FY27 and FY35, against a more conservative sell-side estimate of about 2.8 per cent. FY27 is expected to be the low point for copper over the medium term, about 3 per cent below FY26 because of expected lower grades at Escondida, so a soft first quarter fits the forecast.
Beyond copper, Jansen Stage 1, BHP’s project for potash, a fertiliser input, is now 87 per cent complete and on track for first potash in mid-calendar 2027 at a cost of US$8.4 billion. Jansen Stage 2 is 18 per cent complete at a cost of US$6.9 billion, with first production expected late in FY31.
Sell-side research credits BHP with stronger margins and operating performance than other global miners, particularly at Escondida and in Pilbara iron ore, where it generates more free cash flow per tonne than its peers, which helps it fund a pipeline this large without straining the balance sheet or the dividend.
Valuation and the Buy Case
Institutional sell-side research has a 12 month price target of A$65.70 on BHP, nudged up from A$65.50 after the result, implying 14.1 per cent upside from the share price of A$57.56 when this research was published. Forecasts barely changed despite a clear copper miss, because guidance held, the bulks outperformed and prices did much of the work. Earnings per share were US$2.60 in FY26, and sell-side research forecasts US$2.51 in FY27, US$2.45 in FY28 and US$2.54 in FY29, a shallow dip through the copper production trough and a period of heavy investment.
The research’s Buy rating rests first on cash flow and a strong balance sheet, which sell-side research believes supports a 60 per cent payout through the FY27 production dip, with net debt expected to stay below US$10 billion even with every copper project funded. It also rests on the copper pipeline of about US$50 billion, which gives BHP a path to about 1.8Mt of equity copper production from FY35, and on superior margins and operating performance, especially in the Pilbara and at Escondida, which let BHP fund growth and dividends together.
At the share price of A$57.56 when this research was published, the trailing dividend yield is 4.2 per cent, fully franked, the price target implies 14.1 per cent upside, and the copper pipeline adds long-dated growth. The research’s case assumes copper volumes recover through the rest of FY27 as guidance implies, while the bulks keep funding the dividend and the projects.
Key Risks
BHP’s earnings move with commodity prices over the next 12 months and with currencies, including the Australian dollar, the Chilean peso and the Canadian dollar, and a fall in iron ore or copper prices would hit cash flow quickly. Operating costs and capital spending can rise, and higher costs would reduce margins. Execution is a risk across a large slate of projects including Jansen, the Escondida New Concentrator and the Copper South Australia expansion, where delays or overruns would push back growth. The September quarter also shows that weather, equipment failures and safety stoppages can disrupt operations. Other risks are changes to taxes and royalties in the countries where BHP operates, and a large external acquisition that the market does not welcome.
Our View
Record iron ore volumes, better coal output and strong realised prices absorbed the copper miss this quarter. The things we would watch from here are whether Escondida’s throughput recovers through the rest of FY27, whether Spence delivers the second-half weighting its guidance needs, and whether the Escondida New Concentrator reaches a final investment decision on the timetable sell-side research expects. We also like that BHP is funding growth from cash flow and asset recycling, such as the silver stream and the planned Pilbara power sale, which protects the balance sheet and the dividend.
If you would like to discuss BHP, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR