

Buy
a2 Milk is a New Zealand company whose largest business is selling infant milk formula, including to parents in China and under its English label a2 Platinum range.
Institutional sell-side research rates it Buy because the China label rebuild, which costs the first half of FY27, sets up a stronger FY28. New products and the refreshed a2 Platinum have launched, and Pokeno insourcing is on track. It forecasts FY28 EBITDA growth of about 29 per cent and earnings per share growth of about 30 per cent.
- Sell-side rating
- Buy
- Sell-side target
- A$8.20
- Upside to target
- +13.1%
- Initial price
- A$7.3917 Nov 2026
- Last close
- A$7.2518 Nov 2026
a2 Milk is rebuilding its China label infant formula business after supply and availability problems, and the cost lands in the first half of FY27. Sales of its China label formula to end customers were running at only about 40 per cent of their pre-disruption level in August. The company is lifting marketing spend to win parents back, and is targeting a return to 100 per cent by the end of FY27. Institutional sell-side research has a2 Milk rated Buy with a 12 month price target of A$8.20, about 11.0 per cent above the share price of A$7.39 when this research was published. That target was lifted from A$7.40 as the valuation now looks to FY28 earnings.
Heavy marketing spend is expected to cut margins sharply in the first half of FY27, with most of the year’s profit coming in the second half. For FY28, institutional sell-side research forecasts growth of about 29 per cent in EBITDA and about 30 per cent in earnings per share. EBITDA stands for earnings before interest, tax, depreciation and amortisation, and it is a common way of measuring operating profit. New China label products and a refreshed a2 Platinum formula have already launched, and moving a2 Platinum production into the company’s own Pokeno plant is on track. The next checkpoint is the annual general meeting on 19 November, where the company is expected to give an update on FY27.
Research published 17 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About a2 Milk
The a2 Milk Company is a New Zealand company whose largest business is infant milk formula. It sells formula under two broad labels. China label products are registered for sale in mainland China and reach parents through mother and baby stores and online, including the company’s own website. English label products, led by the a2 Platinum range, are sold in English packaging. The company also has a US business, where margins are expected to improve, and is growing its Genesis product and its presence in Vietnam. It owns a manufacturing facility at Pokeno in New Zealand and is bringing production of English label a2 Platinum in house from Synlait, which has made it until now. a2 Milk is listed on the ASX under the code A2M and on the NZX as ATM, reports in New Zealand dollars and has a 30 June financial year end.
A Weaker New Zealand Dollar Lifts the Revenue Line
a2 Milk reports in New Zealand dollars but sells into markets priced in Australian dollars, US dollars and Chinese renminbi. When the New Zealand dollar falls, each unit of foreign sales converts back into more New Zealand dollars. Since the company reported its full-year result in August, the New Zealand dollar has depreciated by about 2.5 per cent against the Australian dollar, about 5 per cent against the US dollar and about 6.6 per cent against the renminbi. Institutional sell-side research has updated its forecasts to reflect that, lifting revenue estimates by 3 per cent for 1H27 and by 2 per cent for each of FY27, FY28 and FY29. In this piece, 1H27 means the first half of the 2027 financial year, the six months to 31 December 2026, 2H27 means the second half, and FY means the financial year to 30 June.
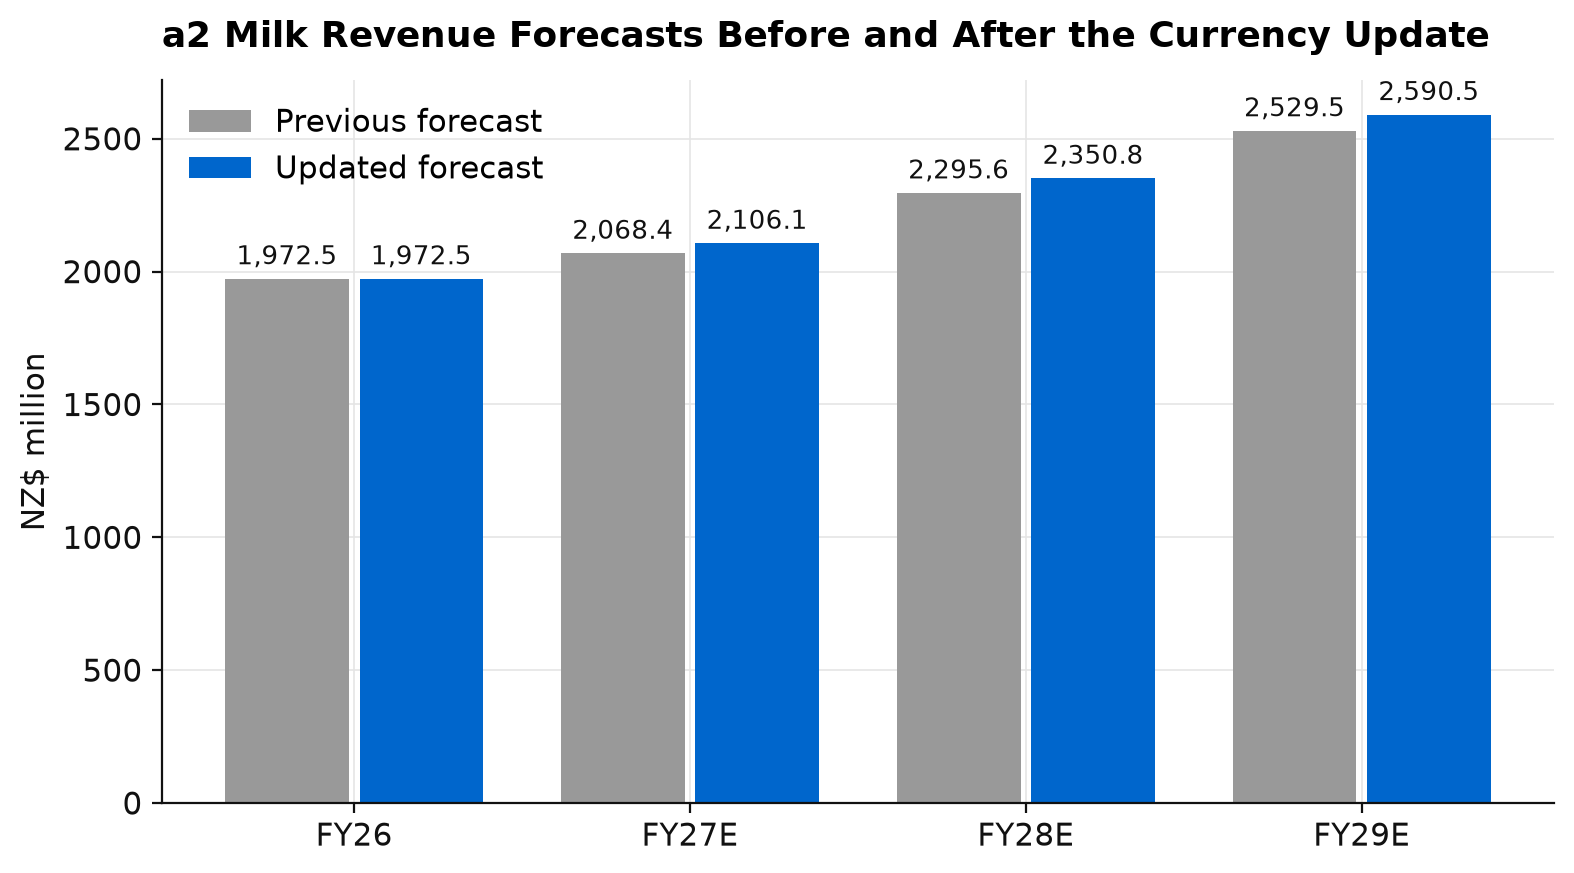
In dollar terms the revised revenue forecasts are NZ$2,106.1 million for FY27, up from NZ$2,068.4 million previously, NZ$2,350.8 million for FY28, up from NZ$2,295.6 million, and NZ$2,590.5 million for FY29, up from NZ$2,529.5 million. That compares with reported FY26 revenue of NZ$1,972.5 million. The chart below shows the old and new forecasts side by side, with the updated figure higher in every year.
EBITDA forecasts rise by only about 1 per cent, because a good share of a2 Milk’s costs are also in foreign currencies. Marketing is a large item, and around 30 per cent of the cost of goods sold is in US dollars, so a weaker New Zealand dollar makes those costs more expensive too. The company also hedges its currency exposure on a rolling basis, locking in exchange rates in advance through financial contracts, so currency moves feed through to results slowly.
The company previously guided to mid-single-digit revenue growth for FY27, meaning growth somewhere around the middle of the single-digit range, with 1H27 revenue broadly in line with 1H26. Institutional sell-side research expects a modest upgrade to that guidance driven by the currency moves, and its 1H27 sales forecast sits about 4 per cent above the market consensus. Guidance also calls for infant milk formula sales in FY27 to be broadly similar to FY26, with China label gradually recovering through the year and English label offtake, meaning what consumers buy in stores and online, gaining momentum during 1H27.
Rebuilding China Label Means a Weaker First Half
a2 Milk lost early-stage China label customers after supply and availability issues with its Stage 1 product, the formula for the youngest babies. In August the company said China label offtake was running at about 40 per cent of pre-disruption levels, and its goal is to get back to 100 per cent by the end of FY27.
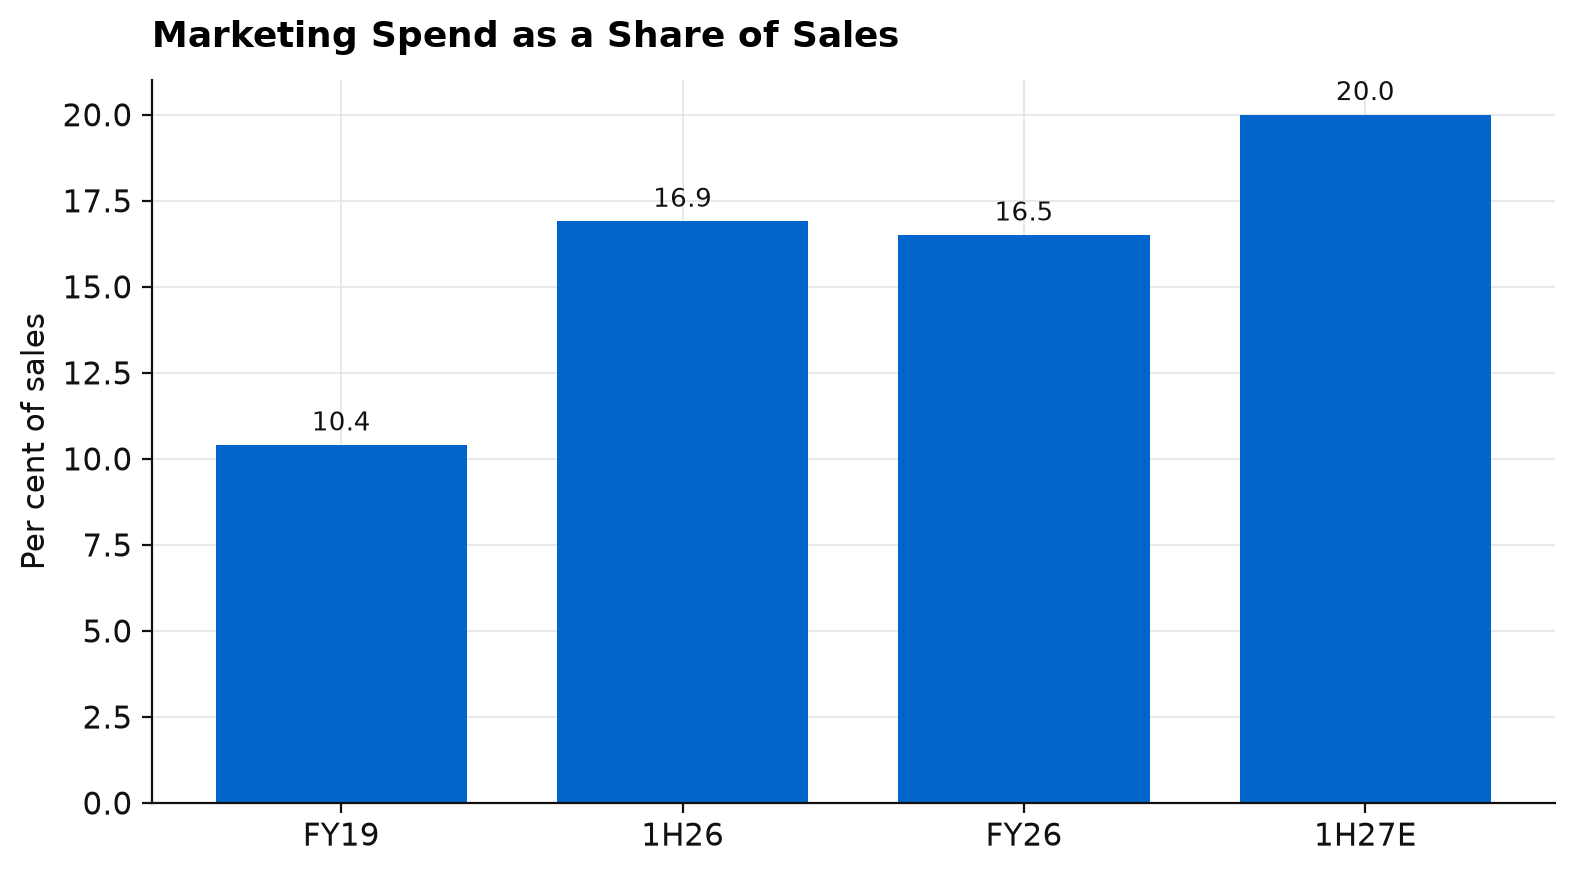
To win them back, the company has guided to higher marketing spend, particularly in 1H27, and institutional sell-side research expects marketing to reach about 20 per cent of sales in that half, against 16.9 per cent in 1H26. Marketing as a share of sales had already climbed from 10.4 per cent in FY19 to 16.5 per cent in FY26, as the chart shows, so the 1H27 figure would be a further step up.
The company guided to an FY27 EBITDA margin of about 15 per cent, with 1H27 materially down on 1H26. EBITDA margin is EBITDA divided by revenue, which shows how many cents of operating profit the business keeps from each dollar of sales. Institutional sell-side research forecasts an FY27 margin of 14.8 per cent, slightly below the 15 per cent consensus, and expects the 1H27 margin to fall by 450 basis points year on year, where a basis point is one hundredth of a percentage point, against a consensus expectation of a 310 basis point fall. On these numbers its 1H27 EBITDA forecast sits about 8 per cent below consensus, even though its sales forecast is above it.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARInstitutional sell-side research expects about 63 per cent of FY27 EBITDA to fall in 2H27, and company guidance already says group revenue and EBITDA will be materially weighted to the second half. With a weak 1H27 profit already flagged, China label offtake will show whether the recovery is working.
Nielsen data for the mother and baby store channel, known as MBS, showed a2 Milk’s sales down 52 per cent year on year in July and August, which was an improvement on May and June. Its rolling 12-month market share in that channel was 3.4 per cent, down 41 basis points on a year earlier and 29 basis points on the previous month.
New Products and Pokeno Insourcing
Institutional sell-side research says new products and insourcing, the two initiatives behind FY28, appear to be on track. On products, a2 Milk launched two new China label formulas, Zhichu Qirun and Zhichu Zhichun, which became available on its website from 3 October and 9 October. Both are priced at a premium of between 10 and 20 per cent to the existing China label product. Institutional sell-side research expects the two new China label products to drive $150 million of sales by FY30.
In the English label range, the company launched an updated a2 Platinum formula on 6 November, the first meaningful upgrade to the formula since 2022. The new version has higher levels of Omega-3 DHA, plus added Lutein, a nutrient for eye and brain development, and a prebiotic called GOS. The tin has shrunk from 900g to 800g while the recommended retail price stays at $43, an implied effective price increase of about 12.5 per cent, though the richer formula is also likely to cost more to make. The packaging gets new artwork, a scoop in the lid for convenience and a QR code for traceability. A pediatric range is due to launch in English label during 1H27, following the China label pediatric launch in 2H26.
Further out, the company is upgrading its Genesis product with a probiotic and packaging changes aimed at making it more competitive, and it is growing in Vietnam. Institutional sell-side research expects Genesis and Vietnam together to reach about $200 million of incremental sales by FY30, and across the full new product slate it expects more than $400 million of incremental revenue between FY25 and FY30. That compares with group revenue of NZ$1,972.5 million in FY26.
The second initiative is insourcing: a2 Milk is moving production of its English label a2 Platinum product from Synlait to its own Pokeno facility in New Zealand. The launch of the new a2 Platinum formula suggests the transition is on track, and the company has reiterated that Pokeno should break even in FY27 and be profitable from FY28 to FY30. Institutional sell-side research expects Pokeno to add about 160 basis points to the group EBITDA margin by FY30, and expects group EBITDA margins to reach about 20 per cent in FY30, up from the roughly 15 per cent guided for FY27.
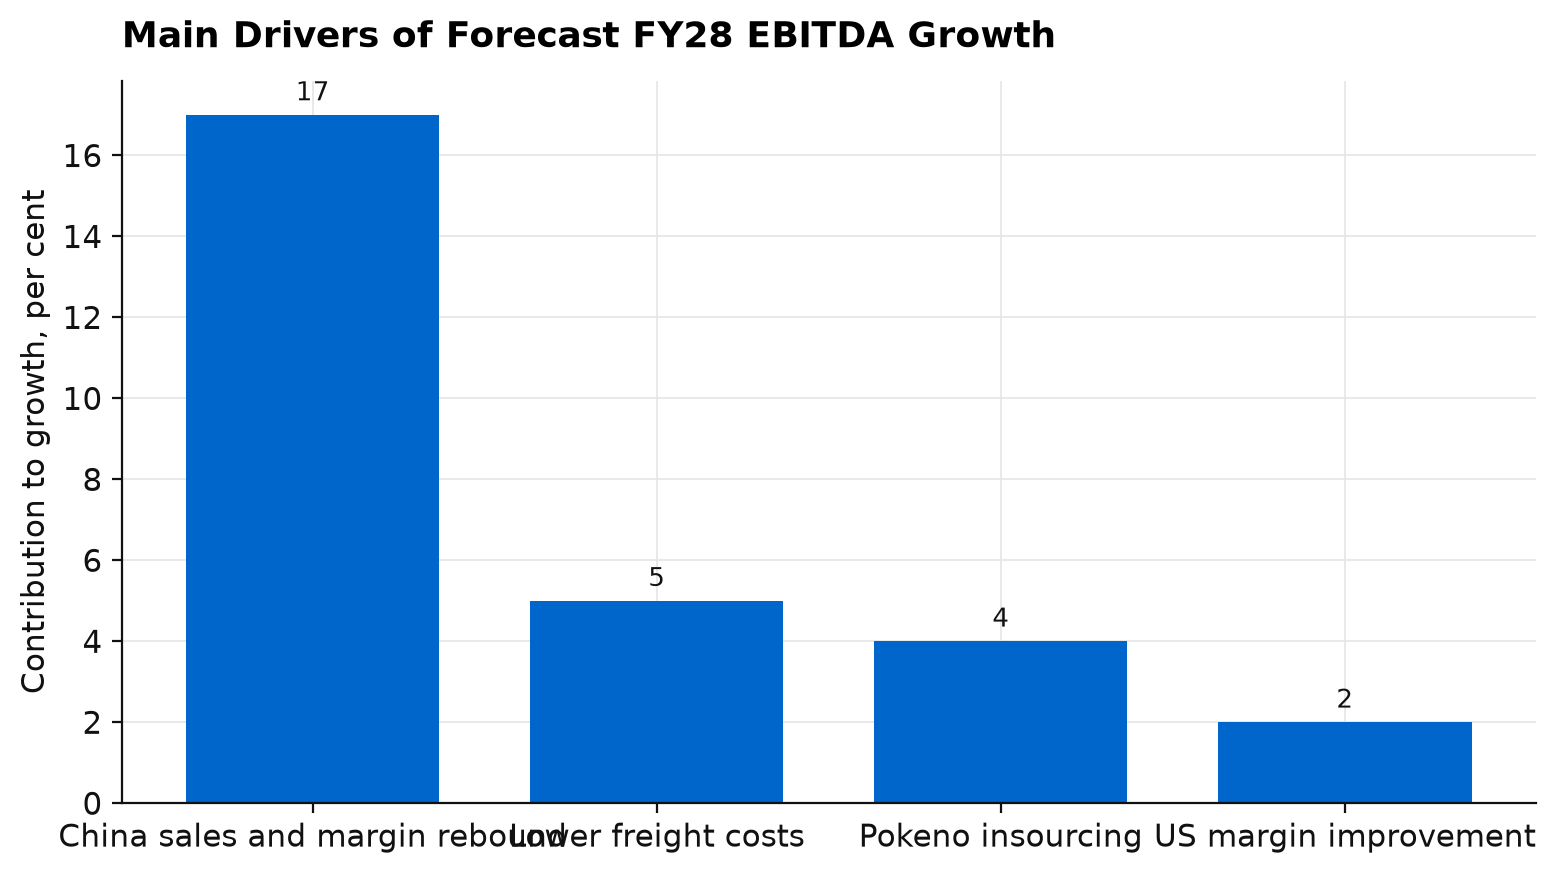
Institutional sell-side research forecasts EBITDA rising from NZ$312.5 million in FY27 to NZ$402.9 million in FY28, growth of about 29 per cent, with earnings per share up about 30 per cent from NZ$0.30 to NZ$0.39, and then to NZ$0.46 in FY29. The largest contributors to that FY28 growth are a strong rebound in China sales and margins, worth about 17 per cent, lower freight costs at about 5 per cent, Pokeno insourcing at about 4 per cent and better US margins at about 2 per cent. The China rebound is expected to follow the FY27 spending on recruiting new users and winning back customers.
For FY27 the company expects cash conversion, the share of operating profit that turns into cash, of about 70 to 80 per cent, capital expenditure of about $70 million and depreciation and amortisation of about $20 million.
Valuation and the Buy Case
The 12 month price target of A$8.20 was lifted from A$7.40 as the valuation moved from FY27 to FY28 earnings, the year the China rebuild and Pokeno are expected to show in the numbers. That puts the target about 11.0 per cent above the share price of A$7.39. Institutional sell-side research forecasts are broadly in line with consensus for FY27 and FY28 earnings, but about 4 per cent ahead for FY29, driven by revenue.
a2 Milk has also paid A$0.44 per share in dividends over the past twelve months, a trailing yield of 6.0 per cent at A$7.39 based on dividends already paid, fully franked.
The currency tailwind is already in the forecasts and should support the guidance discussion at the AGM. The new China label products and the refreshed a2 Platinum have launched as planned, with an English label pediatric range due in 1H27, which lowers the execution risk on the revenue recovery. Pokeno insourcing also puts part of the margin improvement under the company’s own control. Against that, institutional sell-side research is below consensus on 1H27 EBITDA, in line with company guidance for a materially weaker first half.
At the AGM on 19 November and the 1H27 result, the measures to watch are China label offtake climbing from about 40 per cent toward the 100 per cent target, and any change to FY27 guidance.
Key Risks
The biggest macro risk is the Chinese birth rate: marriage registrations in China fell about 15 per cent year on year in the September 2026 quarter, back to September 2024 levels after a rebound through 2025, and because marriages have historically been a leading indicator for births, this suggests birth growth in 2027 may be weak, which could shrink the infant formula market by more than expected. Currency is a second macro risk, since the revenue upgrades depend on the weaker New Zealand dollar and a reversal would take some of them back. On the competitive side, a2 Milk’s rolling 12-month share of the mother and baby store channel was 3.4 per cent and still falling, and the early-stage customers lost through Stage 1 China label supply issues may prove harder to win back than planned. On execution, the 1H27 margin could fall by more than the 450 basis points expected if the marketing push costs more or works more slowly, and any slip in the Pokeno transition would delay the margin benefit. Finally, there are risks particular to infant formula, including further contamination or recalls, particularly in China, and ongoing damage to the brand in China from the recent US recall.
Our View
a2 Milk has chosen to spend through a soft first half to rebuild China label demand, while new products and Pokeno build toward the FY28 forecasts. Short interest is about 7.1 per cent of free float, meaning that share of the stock available to trade has been borrowed and sold by investors betting the price falls. If the AGM update and the 1H27 result show offtake recovering, some of those investors may need to buy shares back, which can add to a move higher. If offtake stalls, the first-half weakness would run longer and put the Buy rating at risk.
If you would like to discuss a2 Milk, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR