

Buy
BlueScope Steel is an Australian-listed steelmaker that makes coated and painted steel, including COLORBOND and TRUECORE, with major operations in Australia, the United States and Asia.
Institutional sell-side research rates it Buy because higher US steel prices and a stronger Australian business have lifted first-half FY27 earnings guidance to approaching A$1.1 billion. Falling capital spending supports forecast free cash flow of about A$700 million in FY27, and the research sees the shares trading at a discount to peers with a strong balance sheet. It also regards the company's 2030 targets as conservative.
- Sell-side rating
- Buy
- Sell-side target
- A$39.30
- Upside to target
- +23.6%
- Initial price
- A$32.6613 Nov 2026
- Last close
- A$31.7918 Nov 2026
BlueScope Steel has raised its earnings guidance for the first half of FY27. Earnings before interest and tax, or EBIT, a simple measure of operating profit, is now expected to be approaching A$1.1 billion for the half, above the prior guidance range of A$860 million to A$960 million, which would be the highest half-year result since FY22. Most of the lift has come from the United States, where steel prices have stayed high on low imports and firm domestic demand, and the Australian business is selling more of its premium COLORBOND and TRUECORE products. Institutional sell-side research has BlueScope Steel rated Buy with a 12 month price target of A$39.30, about 20.3 per cent above the share price of A$32.66 when this research was published.
Research published 13 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About BlueScope Steel
BlueScope Steel is a steelmaker listed on the Australian Securities Exchange and, according to institutional sell-side research, one of the highest-margin value-add steel businesses in the world, because of its global lead in metal coating and painted steel. Around 40 to 50 per cent of its steel production is painted and coated product, which earns much higher margins than plain steel. The group reports through five businesses: Australian Steel Products, home to the COLORBOND and TRUECORE brands; North Star, a US steel mill; Buildings and Coated Products North America, which includes Steelscape in the western US; Coated Products Asia; and New Zealand and Pacific Steel. Its financial year ends on 30 June, and it owns the Port Kembla blast furnace and a 1,200-hectare portfolio of surplus industrial land.
North America Drives the Guidance Upgrade
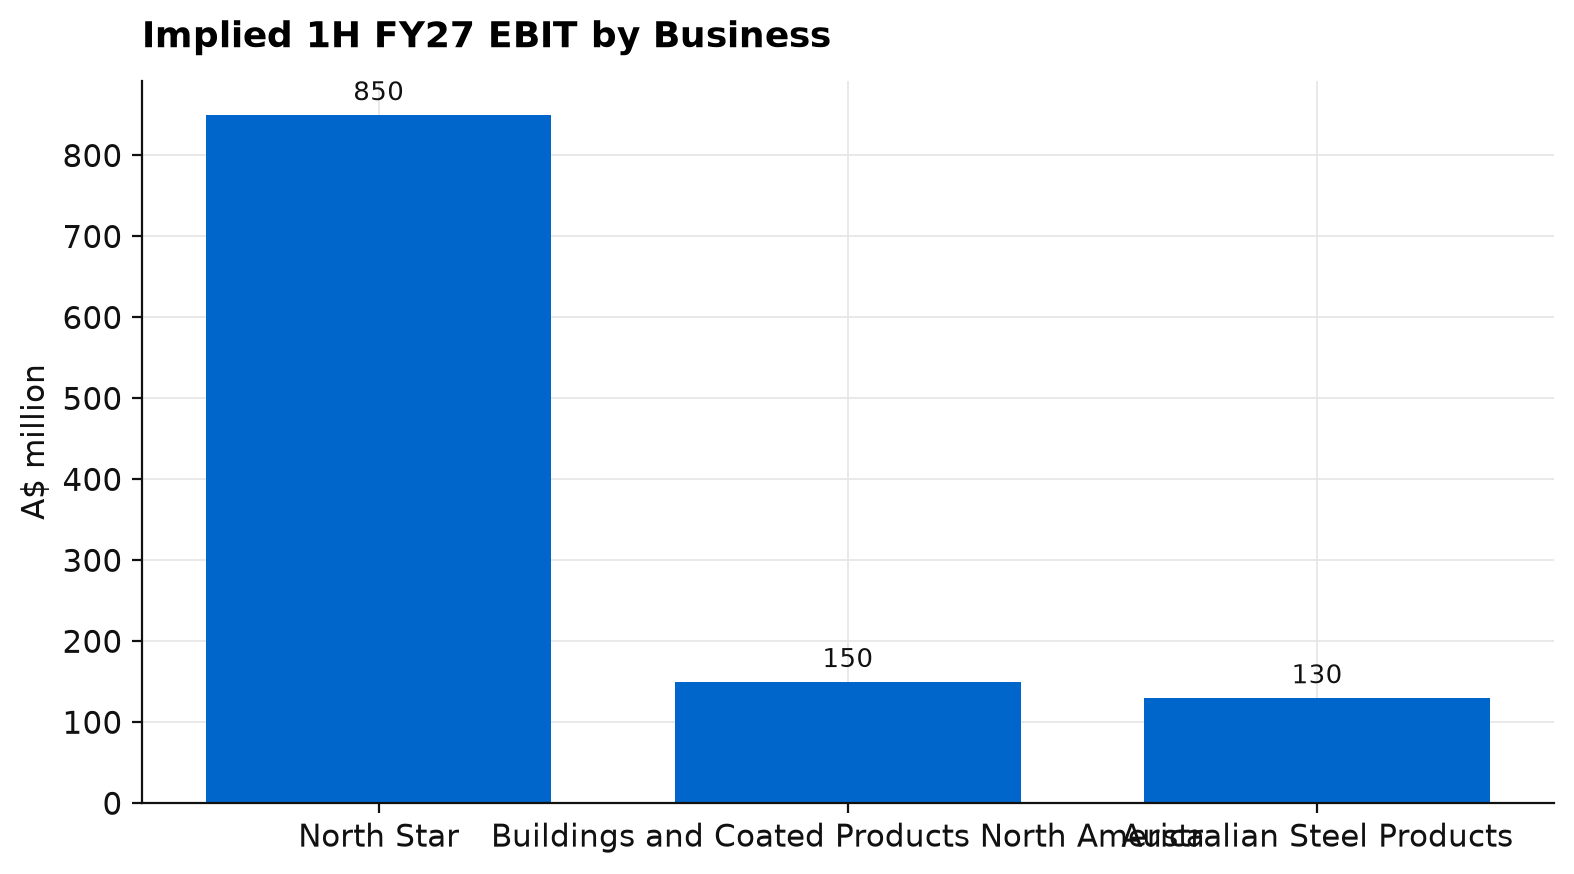
BlueScope had previously guided to first-half FY27 EBIT of A$860 million to A$960 million and now expects a figure approaching A$1.1 billion, while the research’s own forecast had been about A$900 million, near the middle of the old range. Most of the upgrade comes from North America, where BlueScope now expects EBIT around two-thirds higher than in the second half of FY26, implying roughly A$1 billion from the region. Within that, the North Star mill is expected to contribute about A$850 million and the Buildings and Coated Products business, known as BCP, about A$150 million.
A steel spread is the gap between the price a mill gets for its steel and the cost of the main raw materials it uses to make it, so a wider spread leaves more profit on every tonne sold. North Star is a mini-mill, a steelworks that makes new steel mainly from recycled scrap, and BlueScope now expects its US mini-mill spread to average US$810 a tonne, up from the US$750 a tonne assumed in its earlier guidance. North Star is also selling more steel, as a debottlenecking project that removes pinch points in the plant lifts capacity from 2.9 million tonnes to about 3.3 million tonnes a year, and the research thinks those extra tonnes are being sold at today’s higher spot prices.
US hot rolled coil, or HRC, the benchmark flat steel product that much of the US market prices off, is up about 40 per cent in 2026 to a spot price near US$1,320 a short ton, a US measure slightly lighter than a metric tonne, and BlueScope’s US steel spreads have risen by about the same 40 per cent. Recent results and guidance from Cleveland-Cliffs and Steel Dynamics, two other US steelmakers, have also pointed to sustained high US steel prices.
Within BCP, Steelscape, the coated steel operation in the western US, delivered stronger results, and the Buildings arm earned higher margins.
The Australian Business Is Recovering
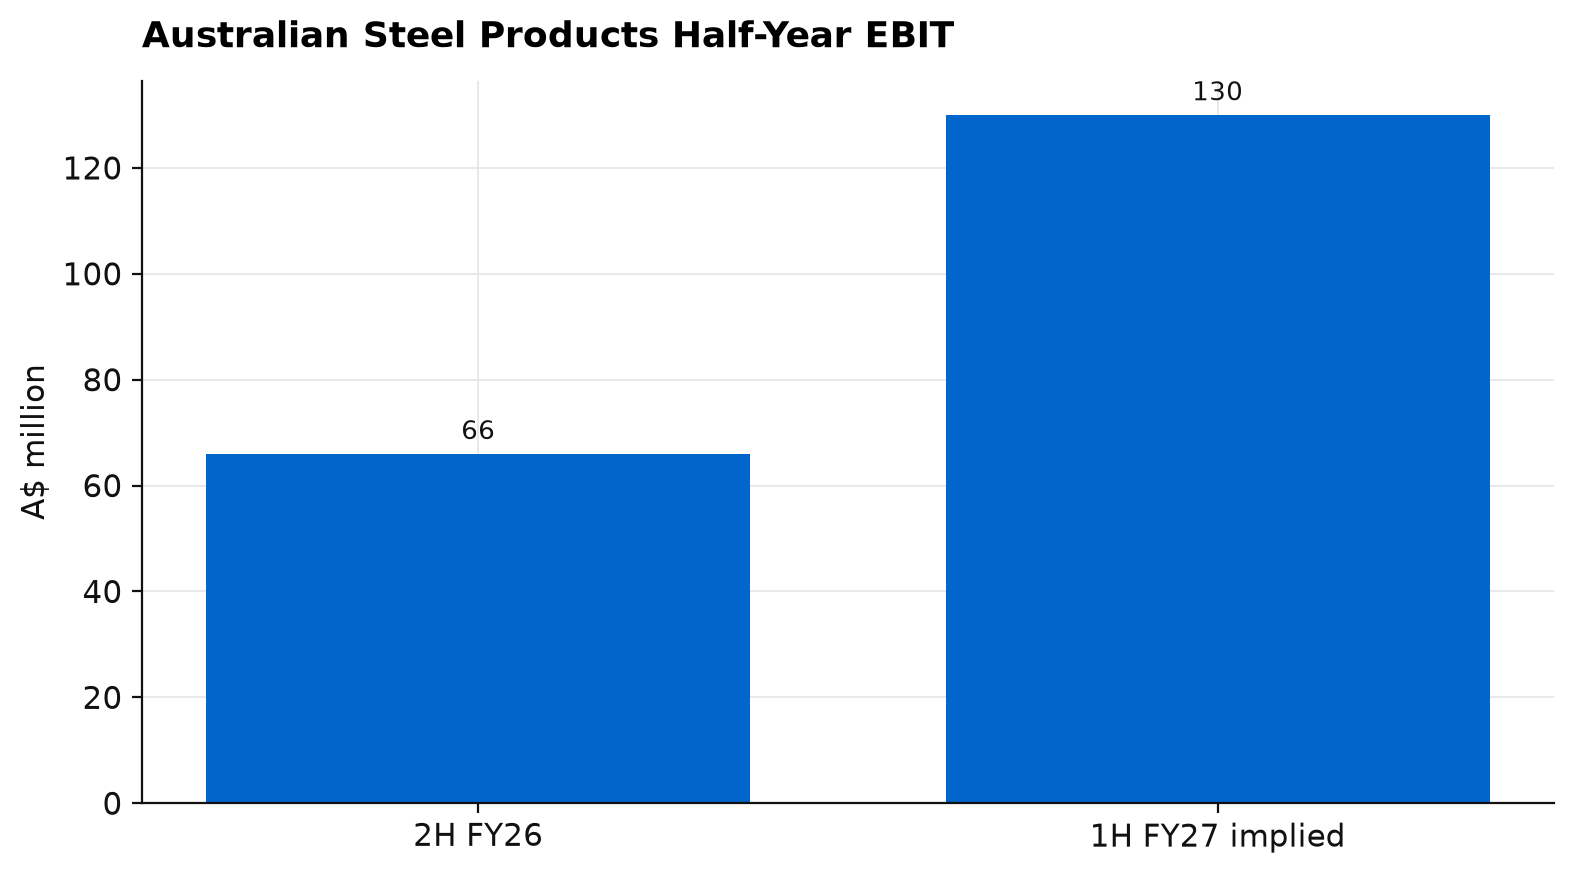
Australian Steel Products, the domestic business, is expected to roughly double its EBIT from the A$66 million it earned in the second half of FY26, implying about A$130 million in the first half of FY27, which would take it back to the kind of half-year earnings it produced across calendar 2024 and 2025.
Higher demand and a larger share of value-add sales, meaning painted and coated products that sell at a premium to plain steel, are behind the improvement, and they helped offset slightly softer benchmark spreads. Over 2026, Australian spreads have risen only modestly because local pricing lags moves overseas. Domestic volumes rose 5 per cent half on half in the second half of FY26, helped by ongoing strength in non-dwelling construction and infrastructure, and sales of COLORBOND and TRUECORE products reached their highest level since 2022. Institutional sell-side research thinks volumes have risen further in the December half as a new metal coating line, line number 7, ramps up.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARWith its FY26 results, BlueScope announced a 3 to 4 per cent increase in COLORBOND prices for FY27, and the research sees possible further increases in value-add steel prices across the COLORBOND and TRUECORE brands. It describes the resilience of the Australian business as encouraging, given the uncertainty around housing investment in the near term.
Institutional sell-side research made no material change to its forecasts for Coated Products Asia or New Zealand and Pacific Steel. Southeast Asia is benefiting from regional pricing strength, and East Asian HRC prices are up about 15 per cent in 2026.
Higher Forecasts, Stronger Cash Flow and a Path to 2030
Following the guidance update, institutional sell-side research lifted its first-half FY27 EBIT forecast to about A$1,090 million, from about A$900 million, and its second-half forecast to about A$910 million, from A$820 million. If steel prices held at spot levels, that second-half forecast would be about A$1.4 billion.
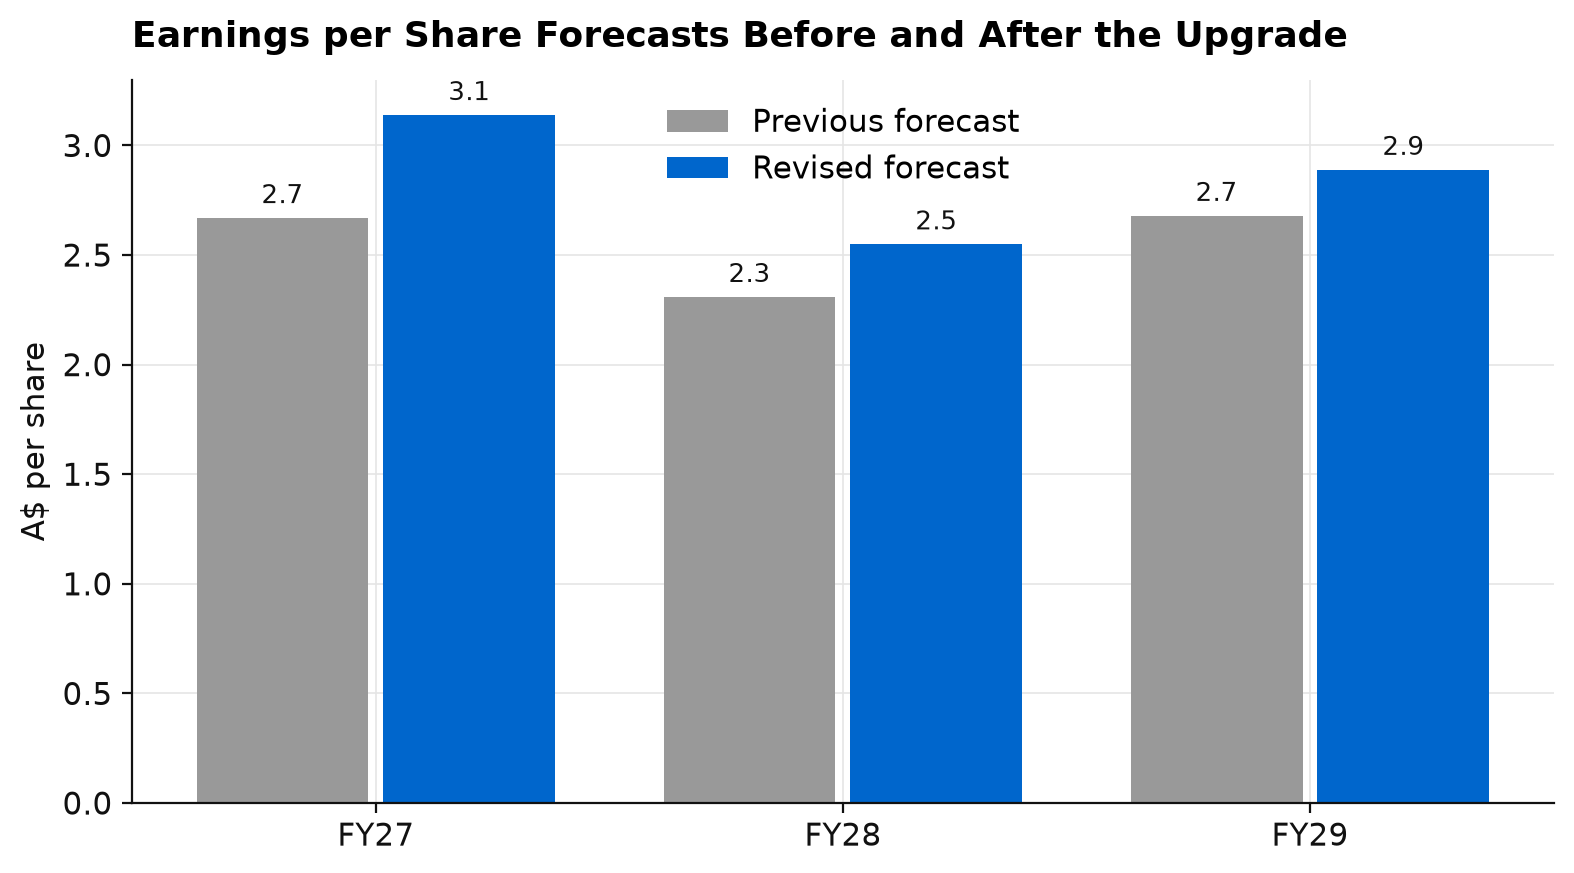
Forecasts for EBITDA, which is earnings before interest, tax, depreciation and amortisation and a rough measure of cash operating profit, were raised by 11 per cent for FY27, 5 per cent for FY28 and 4 per cent for FY29, reflecting higher US and Australian steel earnings and higher margins in later years. Earnings per share is now forecast at A$3.14 for FY27, up from A$2.67, A$2.55 for FY28, up from A$2.31, and A$2.89 for FY29, up from A$2.68, against A$1.94 in FY26. Revenue is forecast to rise from A$16,605.9 million in FY26 to A$18,401.0 million in FY27 and A$19,950.1 million by FY29.
Capital spending, or capex, the money spent on building and upgrading plant, peaked in FY26 at A$1.5 billion and is expected to fall to about A$0.7 billion a year over the medium run. With less going into projects, institutional sell-side research forecasts free cash flow, the cash left after running the business and paying for capex, of about A$700 million in FY27. BlueScope is also running a further A$150 million cost-out program, following the A$200 million it delivered in FY25, and selling parts of its surplus industrial land.
In February 2026 BlueScope set out a new financial framework that targets net debt, meaning borrowings minus cash, of A$1.5 billion through the cycle including leases, up from a prior target of A$400 million to A$800 million, and commits to returning at least 75 per cent of free cash flow to shareholders. The company is targeting another A$3 a share, or A$1.3 billion, of shareholder returns in calendar 2027, including its ongoing on-market share buyback, and it remains in only a slight net debt position.
Institutional sell-side research expects EBITDA of about A$3.0 billion and EBIT of about A$2.1 billion by FY30, at the lower end of BlueScope’s own EBIT target range of about A$2 billion to A$2.5 billion, on better volumes and steel margins across Australian Steel Products and North Star and growth in US painted steel volumes, prices and margins. BlueScope’s 2030 targets include volumes from its Coil Coatings business rising by about 60 per cent to 600 thousand tonnes a year, and more than A$200 million of extra EBIT from the North Star debottlenecking to 3.3 million tonnes and improvements at BCP, targets the research regards as conservative.
Valuation
Institutional sell-side research lifted its 12 month price target by 4 per cent to A$39.30, from about A$37.70, which is about 20.3 per cent above the share price of A$32.66 when this research was published. The target is mostly based on fundamental value, blending net asset value, an estimate of what the company’s assets are worth, with a multiple of EBITDA, and gives a smaller weight to what the business might be worth in a takeover.
According to the research, BlueScope trades at a discount to international steel peers and to painted and coated steel peers even though its group margins sit above those of US steel peers, and its share price implies a US steel price well below today’s spot level. The research also points to a strong balance sheet with only slight net debt, forecasts free cash flow of about A$700 million in FY27 and regards BlueScope’s 2030 targets as conservative. Over the past twelve months BlueScope has paid A$3.00 a share in dividends, a trailing dividend yield of 9.2 per cent, unfranked.
Key Risks
The research names three risks: a slowdown in the global economy, which would hit steel demand and prices, while higher Chinese steel exports would push down the East Asian HRC price that the Australian business references on a three to six month lag, and a stronger Australian dollar would lower earnings because BlueScope’s products are largely priced in US dollars; cost inflation in energy, metallurgical coal, iron ore, scrap, freight and labour, which could raise operating costs; and problems on key projects, including the North Star expansion, the Port Kembla blast furnace reline and the US midstream and painted steel strategy, which could mean more capex and lower returns.
Our View
BlueScope reaffirmed at its annual general meeting in November that first-half EBIT should be approaching A$1.1 billion, and the first-half result will show whether the US mini-mill spread averaged the US$810 a tonne now guided and whether Australian Steel Products reached about A$130 million.
If you would like to discuss BlueScope Steel, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR