

Sell
Commonwealth Bank is Australia's largest bank, offering home loans, business lending and everyday banking to customers in Australia and New Zealand.
Institutional sell-side research rates it Sell because costs are rising at a pace the bank cannot easily reduce, with cost growth forecast to average 3.8 per cent a year over the next three years. Capital is also tighter, with the CET1 ratio falling from 12.3 per cent to 12.0 per cent. The shares already assume the strong growth of FY26 will continue, so a faster slowdown in business credit could hurt earnings and the valuation.
- Sell-side rating
- Sell
- Sell-side target
- A$137.50
- Upside to target
- −19.9%
- Initial price
- A$154.9627 Aug 2026
- Last close
- A$171.6319 Nov 2026
Commonwealth Bank delivered a strong FY26 result. Cash earnings of A$10,982 million came in ahead of market expectations, and its Business Banking division grew loans 13 per cent while widening its margin. The risk for shareholders lies in the costs the bank has committed to over the next three years, and in what happens to the share price if the credit boom behind this year’s growth slows faster than expected. Institutional sell-side research has Commonwealth Bank rated Sell with a 12 month price target of A$137.50, about 11.3 per cent below the share price of A$154.96 when this research was published. The rating rests on costs rising at a pace the bank cannot easily reduce, tighter capital and a share price that assumes the growth of FY26 will continue.
Research published 27 August 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Commonwealth Bank
Commonwealth Bank of Australia is the largest bank in Australia. It is regulated by the Australian Prudential Regulation Authority, or APRA, as an authorised deposit-taking institution, the formal term for a bank licensed to take deposits from the public. It started in 1911 as a federal government owned and managed bank. In recent decades it has grown through a series of scale-changing deals, absorbing the State Bank of Victoria, the State Bank of NSW via Colonial, Auckland Savings Bank in New Zealand, and Bankwest. The group reports through divisions that include Retail, the Business Bank and New Zealand. It is listed on the Australian Securities Exchange under the code CBA. Its financial year ends on 30 June, so the FY26 result covers the twelve months to June 2026.
Business Banking Carried the Year
The Business Bank, the division that lends to and takes deposits from Australian businesses, grew loans 13 per cent over the year, 1.3 times the pace of the overall business lending market, and the division gained market share based on APRA data.
The net interest margin, or NIM, is the gap between what a bank earns on its loans and what it pays for deposits and other funding, expressed as a percentage of its lending assets, and it is a key measure of how profitable a bank’s core lending is. Margins are quoted in basis points, where one basis point is one hundredth of a percentage point. In the Business Bank, the NIM widened by 7 basis points to 3.39 per cent as lending grew, while the Retail division’s margin contracted by 1 basis point over the same period. More loans at a better margin lifted divisional revenue by 10 per cent, and the Business Bank contributed half of the group’s total revenue growth for the year.
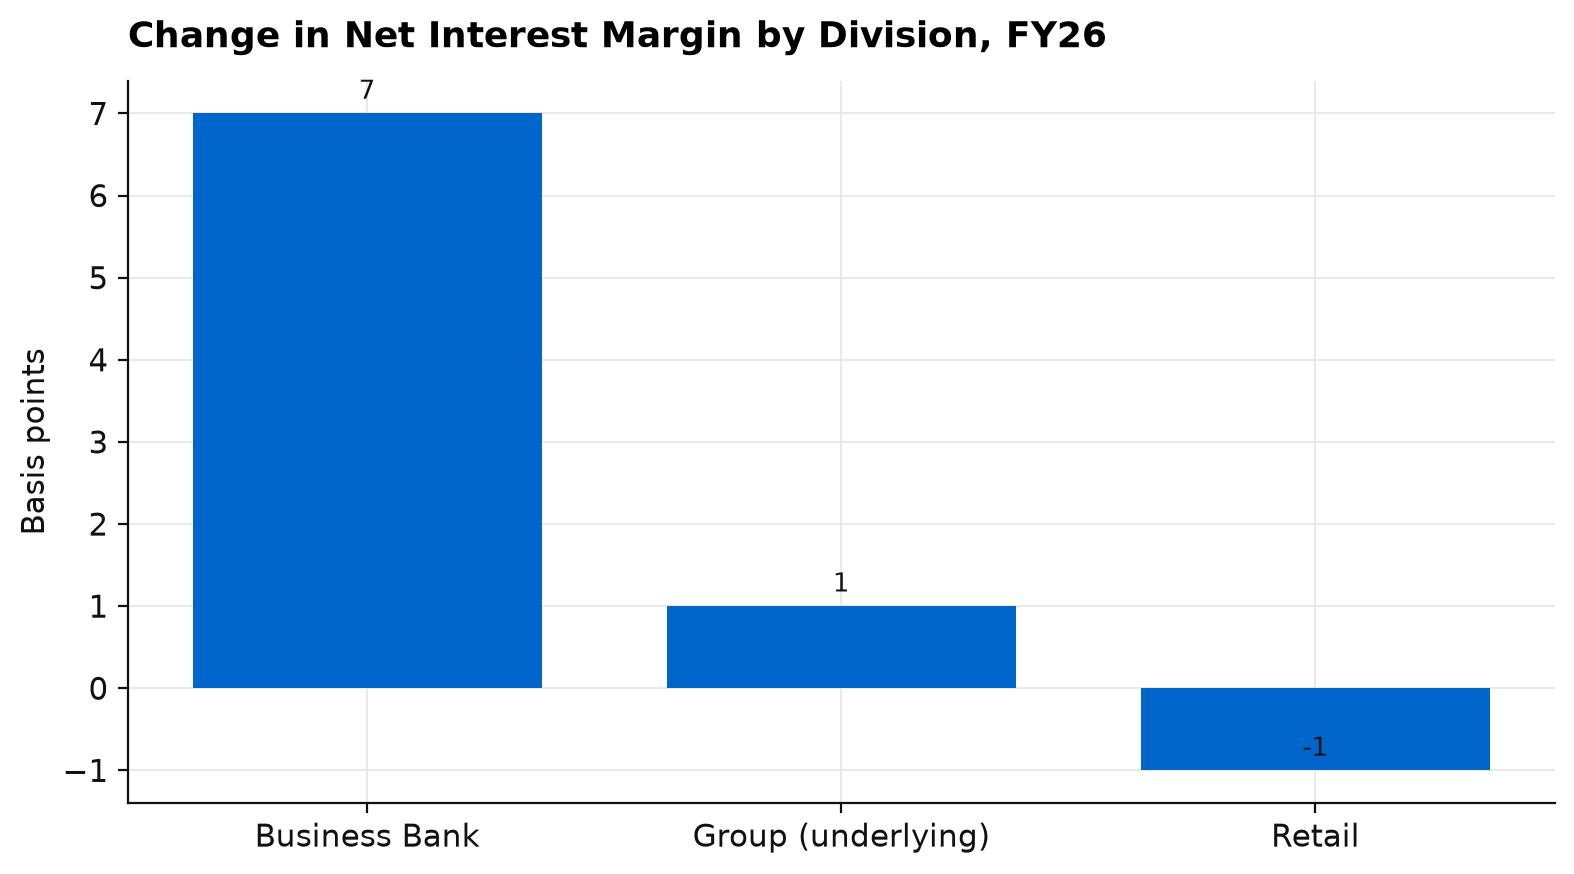
At a group level, revenue grew 6.2 per cent and pre-provision operating profit, or PPOP, rose 6.5 per cent, the strongest growth in both measures the bank has reported in three years. PPOP is profit before tax and before the bank sets money aside for bad loans. The group’s underlying NIM improved by 1 basis point to 2.06 per cent, and the bank grew at or above the market across four key product categories.
The bank also recorded modestly positive operating jaws for the first time since FY23. Jaws is banking shorthand for the gap between revenue growth and cost growth. When revenue grows faster than costs, the jaws are positive and profit margins widen, and when costs grow faster, the jaws are negative and margins shrink.
Cash earnings of A$10,982 million were 1.3 per cent ahead of consensus forecasts of A$10,845 million. At the PPOP line the result was in line with expectations, so the beat came lower down, from an unexpectedly small charge for bad and doubtful debts, the money a bank sets aside for loans that may not be repaid. The charge was 6 basis points in the fourth quarter, down from 12 basis points in the third. The final dividend of A$2.70 per share was 4 cents ahead of consensus.
Housing Is Cooling and the Bank Is Chasing Volume
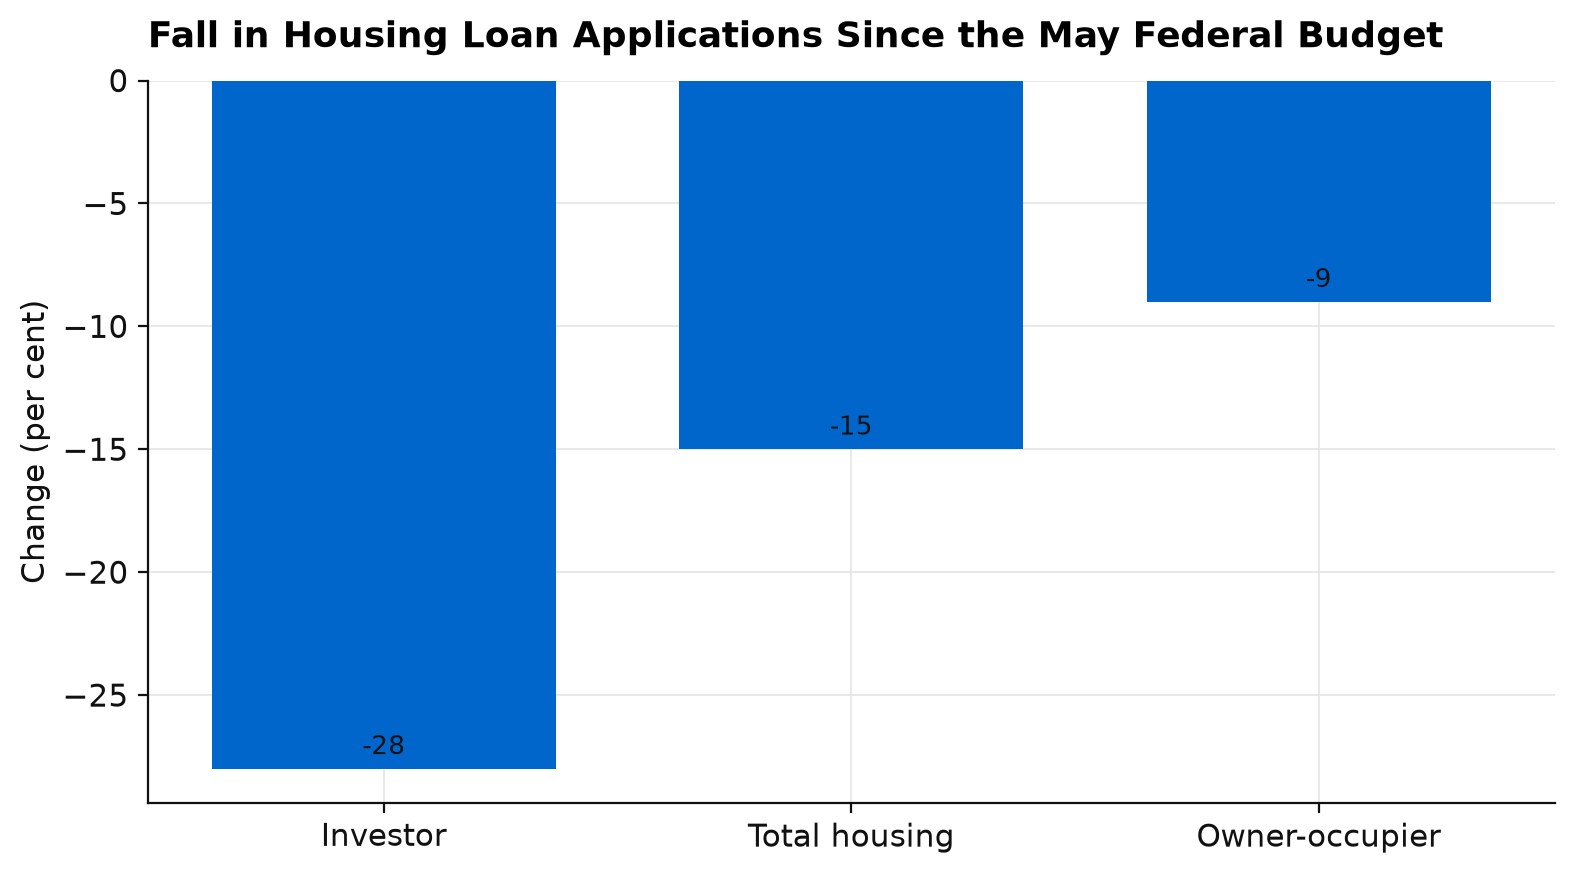
Heading into the result, investors were increasingly worried about a housing-led slowdown, and the data the bank disclosed showed why. Housing loan application volumes have fallen 15 per cent since the May Federal Budget. The fall was led by property investors, where applications dropped 28 per cent. Owner-occupier applications dipped a more modest 9 per cent. That slowdown closely matches what Westpac and NAB have recently reported.
Management described the shift as a healthy return to normal growth after an extraordinary FY26 and guided to sustainable mortgage credit growth of 4.0 to 5.0 per cent for the year ahead. That measured framing helped calm the more alarmist views that had pushed bank share prices around before the result. Westpac highlighted mounting pressure from mortgage competition and from customers moving savings into higher-yielding deposit accounts, while Commonwealth Bank management was characteristically reserved, pointing only to evolving pricing strategies across the industry.
Institutional sell-side research reads that reserve as a sign of a tactical advantage. The bank appears well placed to step up mortgage discounting in the competitive owner-occupier segment written through mortgage brokers, to offset slowing investor demand. That push is supported by a 6 basis point NIM tailwind expected over the next 12 months from the replicating portfolio, and by a shift in the lending mix toward higher-margin business credit. The replicating portfolio is the way a bank invests the money sitting in deposits that pay little or no interest, spreading it across fixed-rate investments of different terms so the income rolls over gradually. As older, lower-yielding pieces mature and are reinvested at higher rates, the income lifts. Together these give the bank a margin buffer that peers may struggle to match.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARThe mix benefit depends on business credit continuing to grow strongly. Business credit across the system was growing at 11.2 per cent a year in June 2026, with forward pipelines still strong, and institutional sell-side research expects that to slow only modestly, to a more sustainable 7.8 per cent by mid-2027. Credit growth above 8 per cent is unusual in an Australian context, though, and the research expects it to slow to more normal levels at some point. If business credit slows faster than expected, the mix benefit shrinks while the housing market is already cooling.
Costs and Capital
Costs are central to the Sell rating: operating costs rose 5.6 per cent over the year, and half of that growth came from higher amortisation. When a bank spends money building new technology, it can record much of that spending as an asset on its balance sheet, called capitalising it. The cost then reaches the profit and loss statement gradually over the following years as amortisation, which smooths the cost of big projects but turns today’s spending into a fixed expense in later years.
Commonwealth Bank’s capitalised investment balance has nearly doubled to A$3.0 billion since 1H22, reflecting record investment in technology and artificial intelligence, and amortisation expense has climbed 171 per cent over the same period. With technology changing quickly, the useful life of some of those assets may shorten, which would bring the expense forward. Despite years of heavy technology spending, the bank’s productivity savings of A$404 million are the lowest among the major banks. Management is deliberately reinvesting gross savings back into the business to drive revenue, and headcount rose 5 per cent in both the Business Bank and New Zealand divisions.
Institutional sell-side research forecasts cost growth above inflation for each of the next three years, averaging 3.8 per cent a year, driven by rising amortisation, a rising wage bill and continued reinvestment. With costs largely locked in, the bank needs revenue and lending volumes to keep growing at an above-average pace, and an unexpected slowdown in revenue would hit earnings harder.
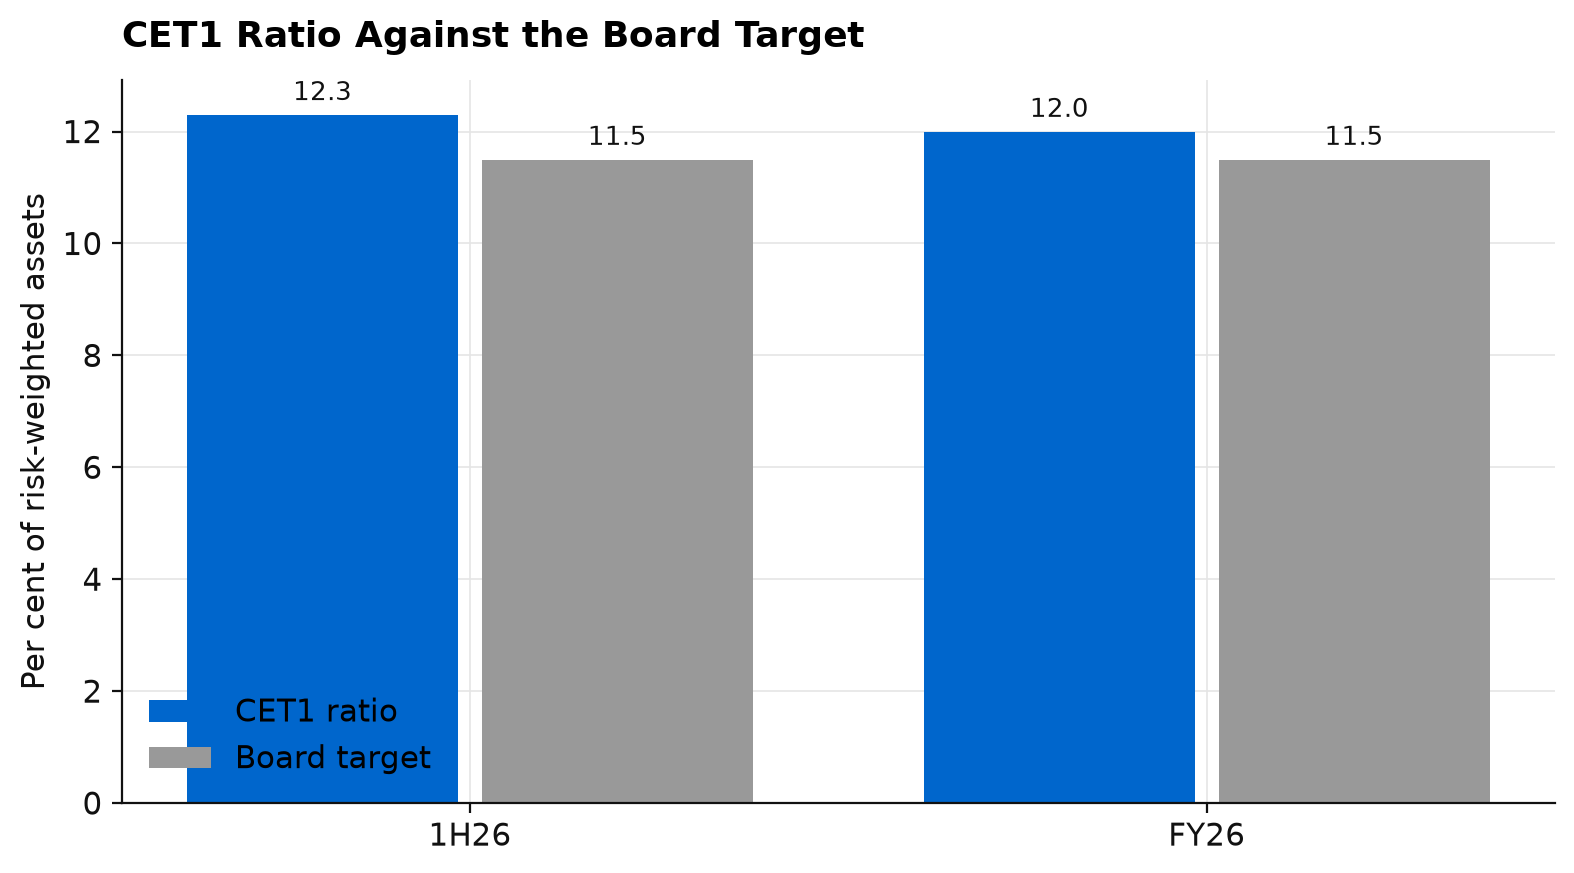
Common Equity Tier 1, or CET1, is a bank’s highest-quality capital, mainly shareholders’ equity, measured against the bank’s loans and other assets weighted by how risky they are. The CET1 ratio fell from 12.3 per cent at the half year to 12.0 per cent at year end, as new lending and dividend payments outpaced the capital generated by earnings. The board targets 11.5 per cent, and the bank wants to stay comfortably above that to defend its Unquestionably Strong status. In response, management confirmed the A$1 billion share buy-back will not be extended, and the dividend payout ratio has drifted lower to 77 per cent, within its 70 to 80 per cent target range.
Business lending adds to the pressure because it carries a higher risk weight than home lending, so the bank must hold more capital for each dollar lent, and business lending drove much of the growth in FY26. A cooling housing market frees up some capital, though less than a slowdown in commercial lending would, because home loans carry lower risk weights. The bank can move the payout ratio toward the lower end of its range, or reactivate its dividend reinvestment plan, which pays dividends to participating shareholders as new shares. A natural slowing in business credit demand would also ease the pressure, but that would come at the cost of revenue growth.
There were also early signs of strain in loan quality, despite the low bad debt charge in the fourth quarter. Corporate troublesome loans, meaning loans to businesses at higher risk of default over the next 12 months because of weaker profitability, rose to A$4.1 billion from A$3.5 billion at the half year. Troublesome and non-performing corporate exposures together also rose as a share of total committed exposures over the half, with most of the increase in the troublesome categories. Loans more than 90 days in arrears also climbed, most noticeably for personal loans, with smaller rises in home loans and credit cards.
Valuation and the Price Target
Institutional sell-side research has a 12 month price target of A$137.50, lifted from A$129.00 as the valuation was rolled forward a year and the longer-term outlook for business credit demand improved. Even after that increase, the target sits about 11.3 per cent below the share price of A$154.96 when this research was published. Earnings changes were modest, with cash earnings per share forecasts for FY27 and FY28 trimmed by 1 per cent and 2 per cent. Higher amortisation lifted forecast operating costs by 1 per cent, and bad debt charges were raised 2 to 4 per cent on more provisioning and a heavier tilt toward business lending.
On those forecasts, net profit rises from A$10,982 million in FY26 to A$11,402.4 million in FY27, A$11,791.9 million in FY28 and A$12,649.5 million in FY29. Earnings per share go from A$6.56 to A$6.81, A$7.04 and A$7.56, growth of 3.8 per cent, 3.4 per cent and 7.3 per cent. PPOP growth is expected to average 5.5 per cent over the next three years, more than double the 2.6 per cent average of the previous three.
The Sell rating reflects a historic rally in the shares, which has left Commonwealth Bank trading at a valuation premium to other banks that is at historic levels, both in Australia and globally. The research also expects the operating environment for banks to slow following RBA rate hikes and the May Federal Budget, despite the chance of positive jaws in the near term, and sees operating cost growth above inflation as hard to rein in if that environment slows faster than expected.
If business credit slows only gently and the bank holds its margin, the earnings path above is achievable and already in the share price. In a more pronounced slowdown, earnings growth would slow by more than revenue because costs are locked in, and the market would likely pull the valuation back toward more normal levels for a bank, so a modest earnings miss could become a much larger fall in the share price. The trailing dividend of A$5.05 per share gives a yield of 3.3 per cent, fully franked. With the share price at A$154.96 and the target 11.3 per cent below it, institutional sell-side research rates the shares Sell.
Key Risks
The main risks to the Sell rating are developments that could push the shares higher. On the macro side, a softer landing than expected, with business credit staying above the 7.8 per cent forecast for longer and the housing slowdown proving short-lived, would keep revenue growing and support the premium. On competition and pricing, a material recovery in revenue growth through further market share gains or better pricing outcomes than peers would strengthen the earnings path. On execution, stronger cost control that delivers clearly positive jaws even as revenue slows would weaken the Sell case, and FY26 showed the bank can get its jaws positive. On capital, if business lending slows just enough to ease the capital burden without hurting revenue much, the bank would have more room for capital returns. Cost growth that runs faster than forecast as the bank accelerates its technology transformation would add to the downside.
Our View
This was a good result from a well-run bank: the Business Bank gained share at a better margin, and management gave a calmer read on housing than Westpac. The bank has also chosen to invest for growth, which leaves it with a cost base forecast to keep rising for the next three years whatever the economy does. Those costs are manageable while credit grows above 8 per cent and harder to absorb as credit growth returns to more normal levels. The next test is whether Commonwealth Bank can keep revenue growing faster than costs as business credit slows.
If you would like to discuss Commonwealth Bank, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR