

Buy
Pro Medicus sells cloud-based software that hospitals and imaging clinics use over the internet to store, view and share medical scans, mainly in the United States.
Institutional sell-side research rates it Buy because revenue is forecast to grow 30 per cent in FY27 as large contracts already signed, including Trinity, UC Health and BayCare, move into full use. It also sees upside from a new AI-led reporting tool timed to the retirement of the legacy Nuance platform, and from a single software platform that lifts earnings per share from A$1.38 in FY26 to A$2.92 in FY29.
- Sell-side rating
- Buy
- Sell-side target
- A$222.00
- Upside to target
- +14.8%
- Initial price
- A$156.384 Oct 2026
- Last close
- A$193.3918 Nov 2026
Pro Medicus reported its FY26 result and is forecast to grow revenue faster in FY27 as several large hospital contracts move from implementation into full use. It has also brought forward a new AI-led reporting tool as the dominant US radiology reporting software is retired. Institutional sell-side research has Pro Medicus rated Buy with a 12 month price target of A$222.00, about 42.0 per cent above the share price of A$156.38 when this research was published. The research cites signed contracts and the low cost of adding products to a single software platform, and sees the reporting module as material upside.
Research published 4 October 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Pro Medicus
Pro Medicus is listed on the Australian Securities Exchange and sells cloud-native PACS (picture archiving and communication system) software, which hospitals and imaging clinics use over the internet to store, view and share medical scans. The core product is the Visage platform, and institutional sell-side research sees the latest version, Visage 7, as faster and more cloud-capable than competing products. The company’s operations are primarily in the United States, with a presence in Australia and Europe. Beyond radiology, it is expanding into adjacent areas including cardiology, digital pathology and AI tools, all built on the same single codebase. It reports on a financial year ending 30 June.
Large Contract Go-Lives Lift FY27 Growth
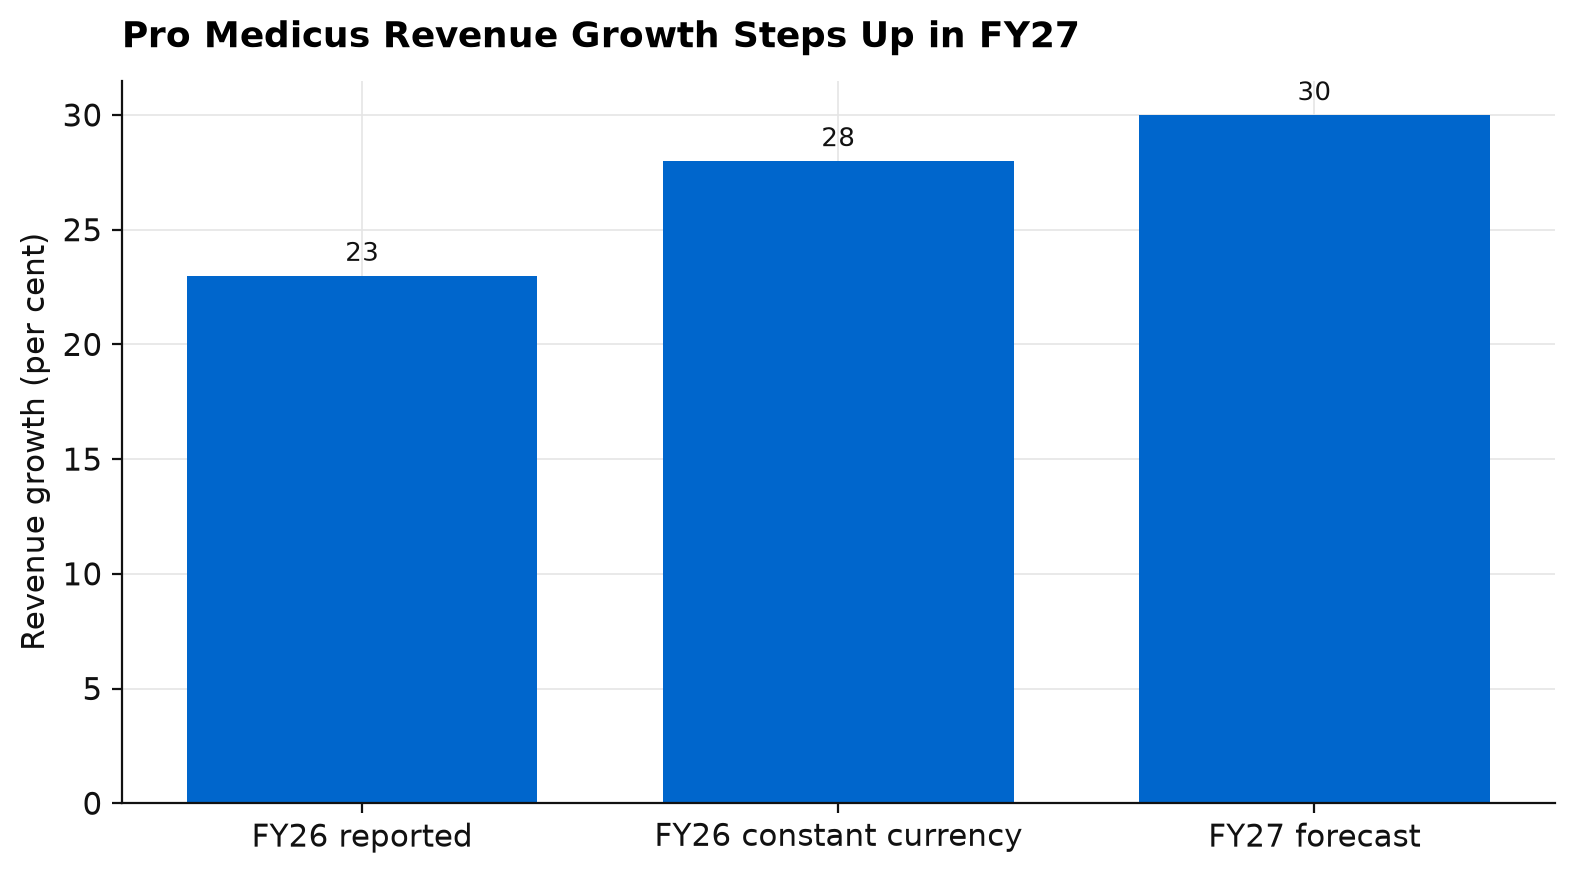
Revenue grew 23 per cent in FY26, or 28 per cent in constant currency, which is the growth rate with the effect of exchange rate movements stripped out. For FY27, institutional sell-side research forecasts revenue growth of 30 per cent, driven mostly by contracts the company has already signed and implemented.
Three contracts, Trinity, UC Health and BayCare, should alone add $45-55mn of incremental revenue, meaning revenue on top of what the company already earns. Alongside them, another 10 implementations were completed during FY26. An implementation is the period in which a hospital moves its imaging work across onto Visage. Pro Medicus is paid as customers use the software, with a price attached to each transaction, so revenue from a new customer builds once the system is live and scans are flowing through it. A year of completed implementations therefore tends to lift revenue the following year.
Many of these implementations landed late in the second half of FY26, and the seventh cohort of the Trinity rollout is scheduled for October 2026, so the research expects some skew toward the second half of FY27, the six months to June 2027. In its half-year forecasts, earnings per share of A$0.74 in the six months to June 2026 rises to A$0.86 in the six months to December 2026, A$0.94 in the six months to June 2027 and A$1.10 in the six months to December 2027.
Pro Medicus reports in Australian dollars, so a stronger Australian dollar reduces the value of its US earnings once they are converted, as the gap between 23 per cent reported growth and 28 per cent constant currency growth in FY26 shows. The research expects foreign exchange to remain a headwind and notes that the company may move to reporting in US dollars.
In US government health, the tender process for the VA’s remaining VISNs continues to progress. A tender, or request for proposal, is the formal process a large buyer uses to choose a supplier, and the VISNs are the separate buying units within the VA that will select a vendor. The VA is expected to structure the next round either by awarding the work to one enterprise vendor or by setting up a panel of two to three approved vendors from which each VISN can choose. Pro Medicus finished the cloud migration of VISN 23 in FY26, and that site is now a reference for other VISNs. In Europe, healthcare systems have been slower than the US to adopt cloud-native imaging, and management sees adoption starting to pick up. The company signed University Hospital Heidelberg, one of Germany’s largest academic medical centres, in October 2025 and plans to use it as a reference site for the broader European market.
A New AI Reporting Tool Aimed at a Forced Industry Switch
Pro Medicus is building a new AI-led reporting module. Once a radiologist has read the images, they produce a written report, and in the United States that step is dominated by one product. Nuance Powerscribe 360, which was acquired by Microsoft, holds around 80 per cent of the US radiology reporting market. Microsoft will be retiring the legacy, on-premises version of that platform, which runs on servers inside the hospital, by August 2027. The research expects that retirement to drive a churn event across the industry, which is a period when a large number of customers leave an existing supplier and look for an alternative at the same time.
Pro Medicus has brought forward development of its own reporting tool in response, and the module is set to headline at RSNA, a major radiology industry event, this year. Visage is already the main desktop viewer for its customers, and the new module lets a radiologist write the report inside the viewer, so a clinic replacing its reporting software anyway can do both jobs in one system.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARManagement expects to charge for the tool per scan and sees potential for a 30 per cent uplift on the transaction price. No FDA approvals are required to roll the product out in the United States, and the module is already live at University Hospital Heidelberg in Germany.
Cardiology is gaining strong momentum as a standard add-on, with 30 to 40 per cent of the sales pipeline, meaning the potential customers in active discussions, now looking at both radiology and cardiology together. Digital pathology, where tissue samples are scanned and read on screen, is at a much earlier and more expensive stage, with adoption in the US below 10 per cent, and digitising a single clinical site typically costs more than $250k.
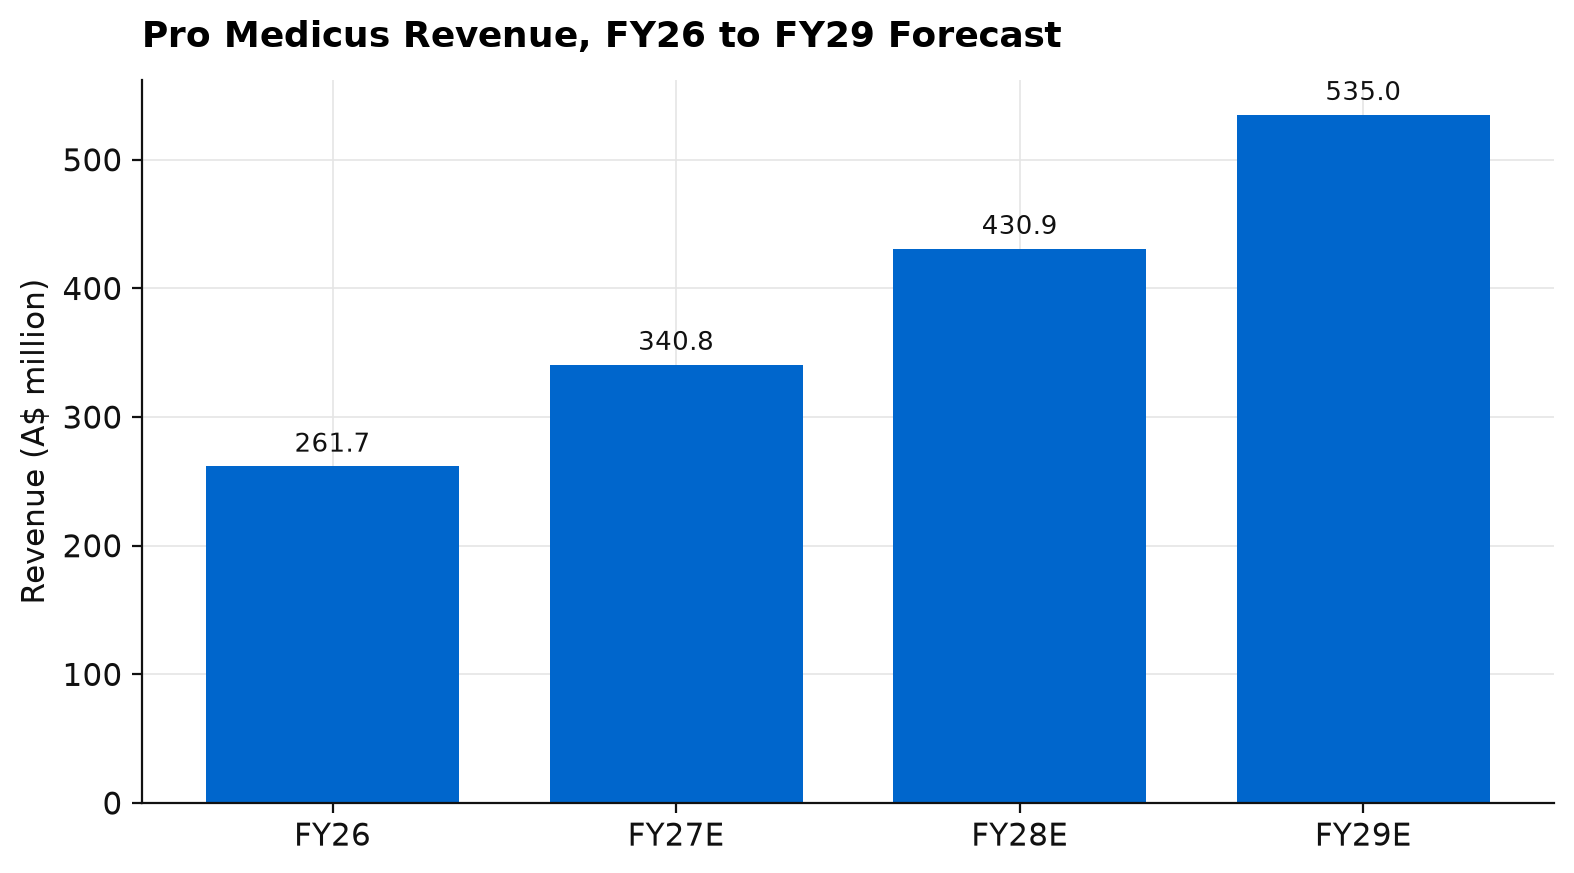
Revenue is forecast to rise from A$261.7 million in FY26 to A$340.8 million in FY27, A$430.9 million in FY28 and A$535.0 million in FY29. The research treats the reporting module as upside to these forecasts.
One Platform That Turns Revenue Into Earnings
Every product runs on one codebase, the Visage platform. Management reiterated that the single codebase gives strong operating leverage, with costs growing more slowly than revenue, and credits it with allowing the company to scale efficiently and expand quickly into adjacent products such as cardiology and the new reporting module.
Spending on research and development continues to grow in absolute terms as the company works to keep its product ahead of competitors. Research and development headcount grew 13 per cent in FY26 to 153, and is expected to grow by a similar magnitude in FY27 to support the product pipeline. The Visage platform is upgraded four times a year, with new releases integrating direct customer feedback without causing operational disruption for the hospitals using it. Even with that investment, research and development spending as a share of revenue remains low relative to peers.
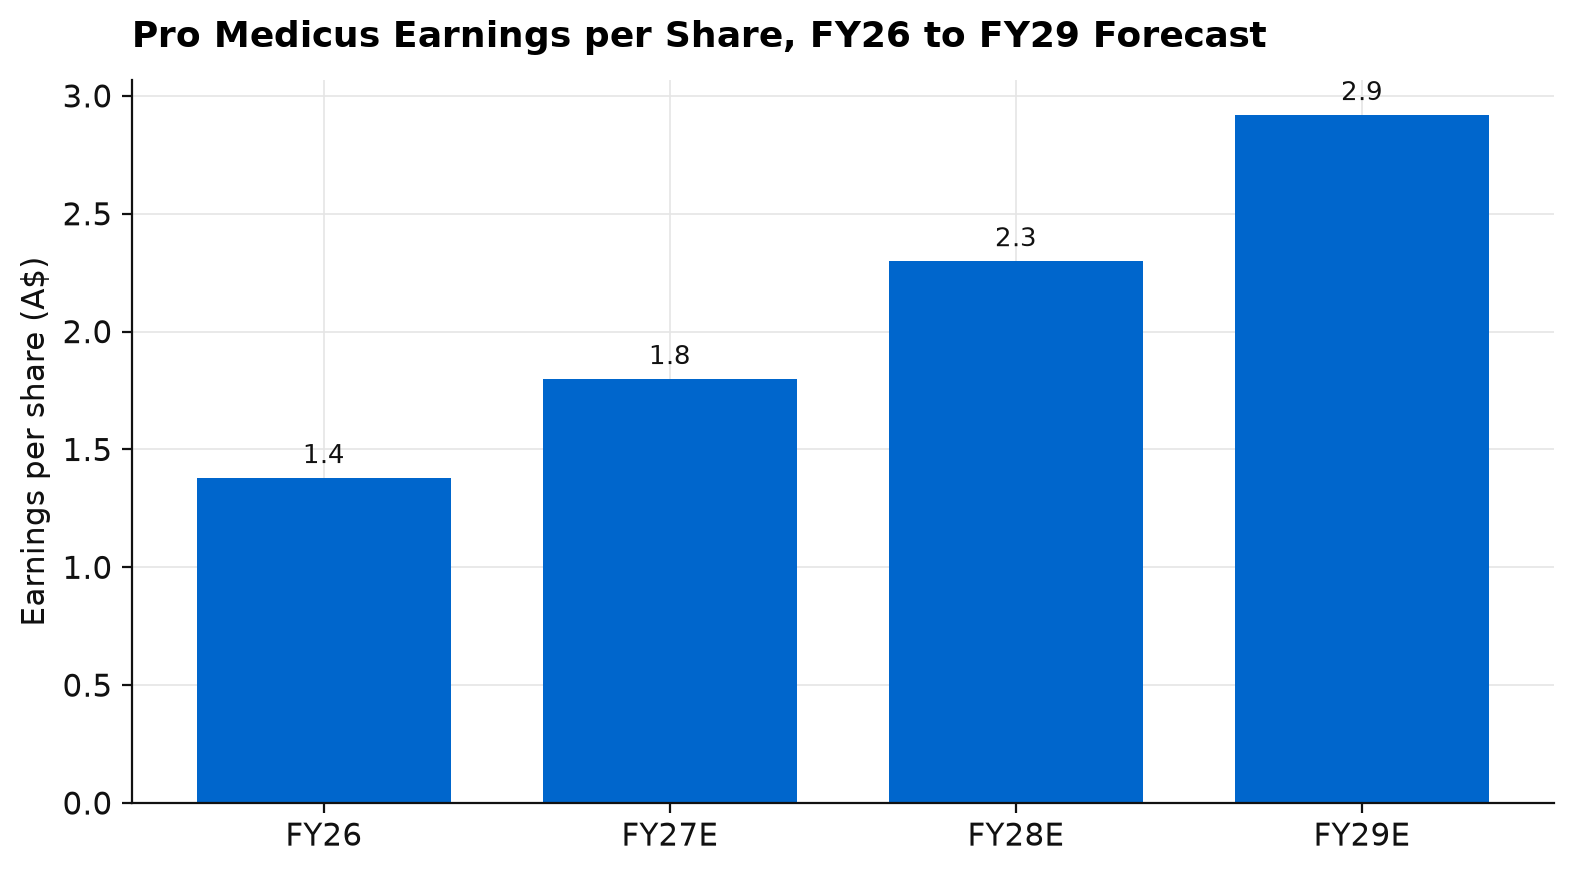
EBITDA, which is earnings before interest, tax, depreciation and amortisation and a common rough measure of operating profit, is forecast to rise from A$204.2 million in FY26 to A$264.8 million in FY27, A$338.5 million in FY28 and A$427.5 million in FY29. Earnings per share is forecast to climb from A$1.38 in FY26 to A$1.80 in FY27, A$2.30 in FY28 and A$2.92 in FY29. The forecasts also have the company holding net cash across the whole period.
The research also sees an industry network effect, because the speed and cloud advantages of Visage 7 have influenced which PACS vendor customers choose, and as more hospitals move to modern systems, new customers look to existing high-profile sites as references. Reference sites such as VISN 23 in the US and University Hospital Heidelberg in Europe help spread that effect into new markets.
Valuation and the Buy Rating
Institutional sell-side research has a 12 month price target of A$222.00 on Pro Medicus, about 42.0 per cent above the share price of A$156.38 when this research was published. Its Buy rating rests on faster growth from contracts already signed, with revenue forecast to rise 30 per cent in FY27 as Trinity, UC Health, BayCare and the 10 other completed implementations feed through. It also counts the new AI-led reporting module, timed to a market-wide switch as the legacy Nuance platform is retired, with the potential to lift transaction price by 30 per cent for customers who adopt it, and the economics of a single platform, with earnings per share forecast to rise from A$1.38 in FY26 to A$2.92 in FY29.
Pro Medicus trades on a high multiple of its earnings, reflecting fast growth, high profitability and a net cash balance sheet. The trailing dividend is A$0.69 per share, a fully franked yield of about 0.4 per cent at the current price.
Beyond the FY27 contract ramp, the research sees further growth from the reporting module, cardiology, the VA tender and Europe.
Key Risks
Pro Medicus is paid per transaction, so a decrease in imaging rates or lower pricing power would slow revenue growth directly, and a stronger Australian dollar would reduce reported earnings. Rival vendors could narrow the speed and cloud advantages that have helped the company win its recent contracts. The forecasts also rely on new contract wins continuing, and a slower pace or smaller size of wins, including in the VA tender, would weigh on growth beyond FY27. A failure to scale AI adoption, or slower uptake of the reporting module as clinics move off Nuance Powerscribe 360, would remove much of the upside described above. The second half skew in FY27 may also make near-term results look uneven.
Our View
The FY27 growth forecast rests mostly on contracts that are already signed and largely implemented, with the lift weighted to the second half. Uptake of the reporting module is less certain, though a good reception at RSNA and wins among clinics that must move off the legacy platform by August 2027 would add a new revenue stream. Our watch points are the reaction to the module, the seventh Trinity cohort in October 2026, and how the VA structures its next round of procurement.
If you would like to discuss Pro Medicus, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR