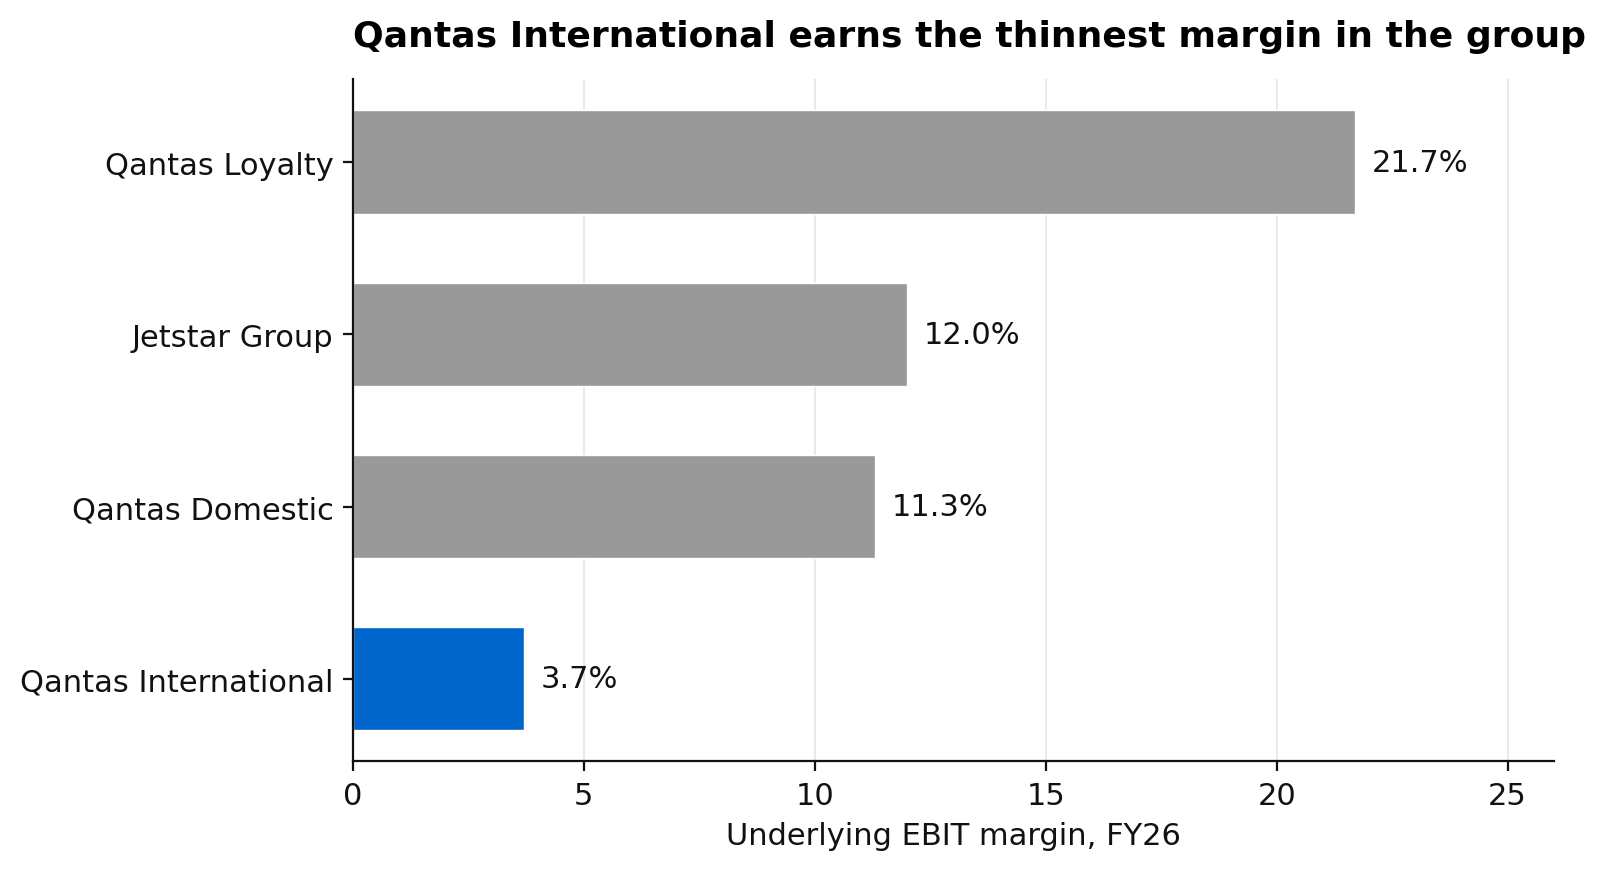
Qantas spent FY26 being read as a fuel story, and the fuel story was real enough. A $610 million increase in the fuel bill and $420 million of net earnings impact from the conflict in the Middle East took underlying profit before tax down $330 million to $2.06 billion. What got less attention in the same set of numbers was the clearest statement the company has made about where its international business is going. Qantas International earned a 3.7 per cent operating margin in FY26, against 11.3 per cent for the domestic airline and 21.7 per cent for Loyalty, and Qantas now expects that segment to run at 10 to 12 per cent from FY32 as the fleet turns over. That is the argument for owning the stock, and it is a fleet argument rather than a demand one. Institutional sell-side research has Qantas rated Buy with a 12 month price target of A$12.45, implying around 32.6 per cent upside from the recent close of A$9.39.
Research published 7 September 2026. Price target and upside based on prices at time of publication.
About Qantas
Qantas Airways is Australia’s largest airline group, with a market capitalisation of about A$14.2 billion. It runs four businesses. Qantas Domestic is the full service domestic airline and turned over $8.0 billion in FY26. Qantas International and Freight flies the long haul network and the cargo operation, and turned over $9.9 billion. Jetstar Group is the low cost carrier across Australia, New Zealand and short haul Asia, at $6.0 billion. Qantas Loyalty runs the frequent flyer program, Qantas Business Rewards and the associated retail and travel businesses, at $2.9 billion. The group carried 18.9 million frequent flyer members at June and ended the year with $13.3 billion of liquidity against $6.2 billion of net debt. Company disclosure is available through the investor centre and its ASX filings, including the FY26 full year result released on 27 August.
The International Business Earns the Thinnest Margin in the Group
Qantas International grew revenue 8 per cent to $9.9 billion on 7 per cent more capacity in FY26, and still saw underlying earnings before interest and tax fall 38 per cent to $371 million. The operating margin came in at 3.7 per cent, or 4.0 per cent before entry into service costs for new aircraft. Demand was not the problem. Premium cabin revenue grew 15 per cent, twice the rate of economy, the final A380 came back into service and let the airline pivot 787 capacity into Europe when travellers moved away from the Middle East, and the combined seat factor on the London, Paris and Rome connections reached 90 per cent in the fourth quarter. The problem was that the fuel bill landed disproportionately on the oldest and thirstiest aircraft in the fleet, and that those aircraft carry the wrong cabins.
Set that 3.7 per cent against the rest of the group and the shape of the business becomes obvious. Qantas Domestic made an 11.3 per cent margin, Jetstar Group made 12.0 per cent, and Loyalty made 21.7 per cent on $2.9 billion of revenue. International is the largest revenue line in the group and contributes the least to earnings, which means it is also the only division where a structural fix is worth a material amount of money to shareholders. Group operating margin for the year was 9.2 per cent, down from 11.1 per cent, and the international result is the largest single piece of that deterioration.
The fuel move behind it was extreme rather than gradual. Jet refining margins went from around US$20 a barrel in February to a peak of roughly US$120, and the group’s total fuel cost for the year reached $5.7 billion. Hedging on Brent crude returned a $400 million benefit and fare and capacity adjustments did the rest, which is how a $610 million cost increase became a $420 million hit to earnings. Statutory profit after tax was $1.29 billion and underlying earnings per share came in at 96 cents, down 14 cents. For a business with this much operating leverage, holding the decline to that level while still spending $4.0 billion on fleet is a reasonable year.
What the New Aircraft Change
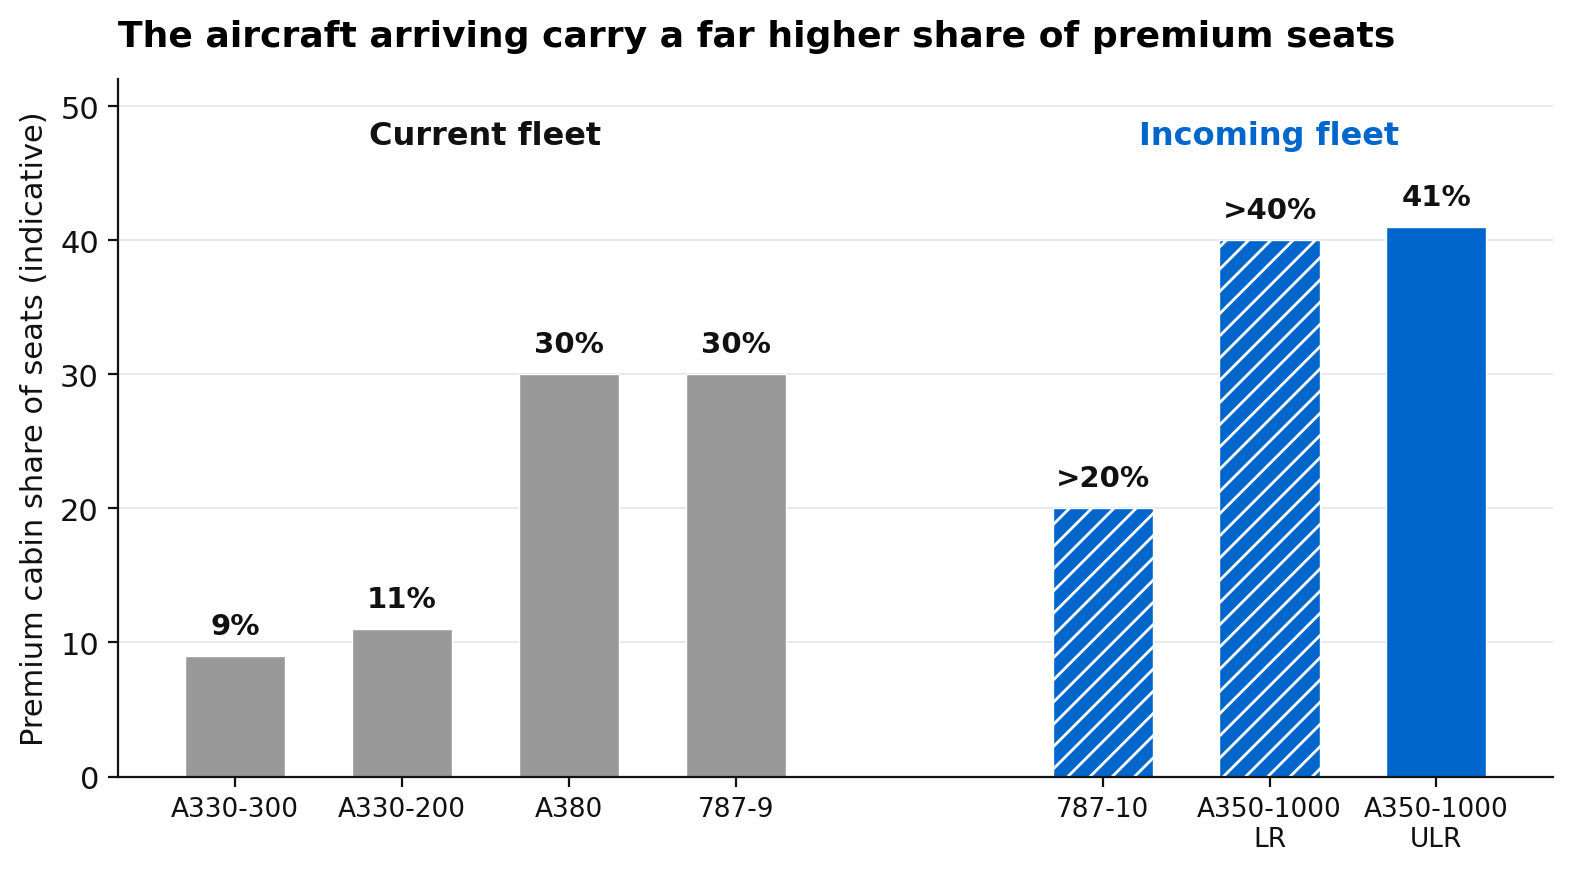
The cabin mix on the aircraft Qantas is retiring and the aircraft replacing them is not a small difference. The A330-300s that carry a lot of the current international network run about 9 per cent premium seating, and the A330-200s about 11 per cent. The A350-1000ULRs arriving for Project Sunrise are configured at 41 per cent premium, the A350-1000LRs at more than 40 per cent, and the 787-10s at more than 20 per cent. On the company’s own figures a premium seat on the international network generates roughly 3.8 times the unit revenue of an economy seat, so shifting a third of the cabin from one to the other is a revenue mix change before it is anything else. Premium cabin yields were already up 5 per cent in FY26.
The cost side moves in the same direction. Newer airframes burn materially less fuel per seat than the aircraft they replace, they need less maintenance, and a simplified fleet reduces the cost of training, spares and crewing that comes with running several types at once. Qantas has a live proof point in the London to Perth non-stop service, where on the network as it ran before the Middle East conflict forced rerouting, unit revenue was more than 20 per cent above the one stop alternative and premium cabin seat factors sat above 95 per cent. The 787-9 point to point long haul routes already deliver the strongest contribution margins in the network, which is the same aircraft argument made with the fleet the airline already owns.
The delivery schedule is now firm enough to plan against. Seventeen new aircraft arrived in FY26 and up to 31 are due in FY27, the majority of them for Qantas rather than Jetstar. The first A350-1000ULR arrives in April 2027, the first non-stop Sydney to London service follows later that year, and the A380 fleet begins phasing out from calendar 2028 once those aircraft are flying. Beyond the 12 Project Sunrise aircraft the group holds firm orders for another 12 A350s and 12 787s, and it is in discussions with Airbus and Boeing about converting roughly 20 existing purchase right options to firm orders from 2030. This is a decade long program, not a step change in one year.
The Margin Target and What Has To Happen
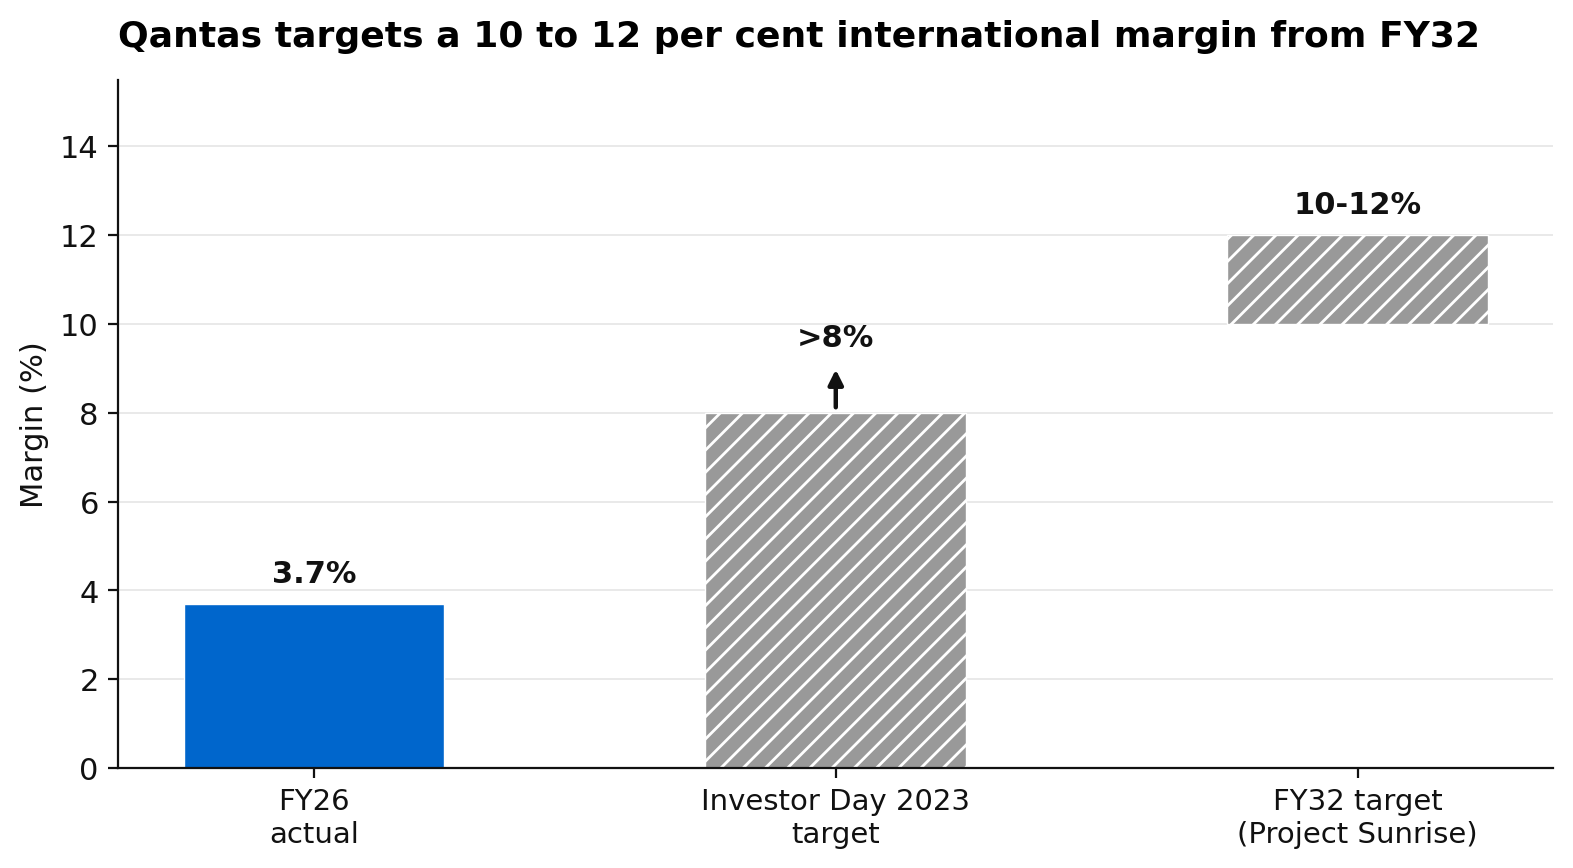
Qantas set segment margin targets at its 2023 investor day and has restated its commitment to them. The international target is more than 8 per cent, and the company now describes a future state target of 10 to 12 per cent including Project Sunrise, expected from FY32. Against 3.7 per cent today that is a very large gap, and the honest way to read it is as an outcome of the fleet program rather than a forecast of trading conditions. The company describes it as a future state and has dated it to the year the bulk of the new international fleet is flying, which is another way of saying the margin arrives when the aircraft do.
What makes the target credible is that the mechanism is largely contracted rather than hoped for. The aircraft are ordered and the delivery profile runs out to the back half of the decade, although Qantas is careful to describe the cabin configurations as indicative and still to be finalised. What is not contracted is everything else. Fuel has to behave, the premium travel market has to keep absorbing the seats being added to it, and the retirements have to happen on the timetable that offsets the deliveries. Qantas has also been clear that entry into service costs rise before the benefits arrive, at about $165 million in FY27 against $150 million in FY26, with the increase weighted towards the first Sunrise aircraft. The margin gets worse before it gets better, and any investor buying this today is buying a schedule.
There is a second, less discussed benefit in the same program. A fleet with smaller average gauge and a higher premium share is less exposed to the discount end of the market, which is where demand elasticity and competitive pricing pressure are greatest. The cheapest economy fares are where competitive pricing pressure lands hardest, so an earnings stream weighted further towards the front of the aircraft should be steadier as well as larger. That matters for how the market is prepared to value the airline, which for most of the last decade has been at a discount that reflects how violently airline earnings can swing.
Loyalty Does Not Care About the Fuel Price
Qantas Loyalty grew underlying earnings before interest and tax 12 per cent to $625 million on revenue of $2.9 billion, at a 21.7 per cent margin, in the same year the flying businesses were absorbing record fuel costs. Frequent flyer members rose 7 per cent to 18.9 million and members earning across two or more categories rose 8 per cent. Qantas Business Rewards now covers one in four Australian small and medium businesses, with membership up 11 per cent and earnings up close to 30 per cent. Points earned and points redeemed both grew 9 per cent, Uber was the fastest growing partner with more than a million members earning on rides and deliveries, and Bunnings joined the program in July.
Guidance is for another 5 to 7 per cent of earnings growth in FY27, and the segment remains on track for its 2030 target of $800 million to $1.0 billion. The risk that had been hanging over it was the Reserve Bank’s review of card payment costs and surcharging, given how much of the points economy runs through credit card partners. Qantas has since agreed revised commercial terms and extended agreements with its largest banking and financial services partners, which takes the acute version of that risk off the table for now. For a shareholder, Loyalty is the part of the group that keeps compounding while the airline waits for its aircraft.
The Base Dividend Grew and the Specials Did Not Repeat
The board declared a fully franked final base dividend of 19.8 cents per share, worth $300 million, payable on 14 October. With the 19.8 cent interim paid in April that makes 39.6 cents for FY26, or $600 million, all of it fully franked. The headline payment is smaller than last year and the reason matters before anyone writes this off as a fading income name. FY25 distributions included special dividends on top of the base and FY26 carried none. The base itself went the other way, rising from $250 million a half to $300 million a half, and Qantas has said it intends to maintain fully franked base dividends of $300 million each half as sustainable through the cycle, subject to board approval. Specials are separately described as sized from surplus capital, which is precisely what is being absorbed by aircraft.
At A$9.39 the 39.6 cents is a 4.2 per cent yield, and because it is fully franked it is worth roughly 6.0 per cent grossed up to an Australian resident who can use the credits. That is a payout of about 41 per cent of the 96 cents of underlying earnings per share, struck against a Moody’s leverage ratio of 1.6 times and an investment grade Baa2 rating held stable. The other half of the capital return story went the other way. The $150 million on-market buy-back announced with the first half result will not proceed. We would rather see that than a company borrowing to buy back stock in the middle of the largest fleet renewal in its history, but it is a withdrawal of a promise and it should be read as one. Net capital expenditure was $4.0 billion in FY26 and is guided to $4.3 billion to $4.6 billion in FY27, and net debt of $6.2 billion sits in the middle of the $5.5 billion to $6.9 billion target range but is expected to reach the top of it by June 2027. Fleet has first call on the cash for the next several years, and the base dividend is what is being protected around it.
Valuation
The 12 month price target carried by institutional sell-side research is A$12.45, about 32.6 per cent above A$9.39 before the dividend, and the size of that gap is not the argument in itself. The stock trades under 10 times the 96 cents of underlying earnings it delivered in what was close to a worst case year for the input it cannot control. Three things anchor the target. The first is the international margin path, from 3.7 per cent today towards a 10 to 12 per cent target the company has now put a date on, driven by aircraft that are already ordered and scheduled. The second is Loyalty, growing at a double digit rate with a 2030 earnings target and no exposure to the fuel price, which underwrites a meaningful share of group earnings regardless of what flying does. The third is the near term revenue setup, with total unit revenue guided up 8 to 10 per cent in the first half of FY27 across both domestic and international on flat group capacity.
The risk and reward is asymmetric here because the downside case is a year of poor trading in a business that just proved it can absorb a $610 million fuel shock and still earn $2.06 billion before tax, while the upside case is a structural repricing of the largest division in the group. You are paid 4.2 per cent fully franked to wait, and the wait is long. The margin target is dated FY32 and the aircraft arrive over the years in between, so this is a position to size for patience rather than for a catalyst.
Key Risks
Fuel is the first and largest risk, and FY26 showed why. The group is highly hedged on Brent crude with favourable participation if prices fall, but it was largely exposed to jet refining margins, which is exactly the part that moved. Fuel costs in the first half of FY27 are expected to be about $3.6 billion and are assumed to stay elevated. The second risk is demand, and specifically corporate and government demand, which contracted through the final four months of FY26 as business confidence fell. Leisure held up and Jetstar was strong, but the premium end of the domestic and international networks is where the margin lives and it is the part most sensitive to a business cycle.
Execution on the fleet is the third. Aircraft delivery schedules slip industry wide, entry into service costs are rising before the benefits land, and the margin target depends on retirements happening in step with arrivals so the group is not carrying two fleets at once. The A380 phase out from 2028 has no disclosed completion date. Beyond that, capital intensity limits flexibility, with net debt guided to the top of its target range by June 2027 and capital expenditure running above $4 billion a year. The buy-back was withdrawn against that backdrop, and dividends could be constrained too if trading deteriorates. Competition on the domestic network, industrial relations, regulatory attention to the loyalty and card economics, and the airline’s own history of reputational problems all remain live.
If you would like to discuss Qantas or how Australian equities might fit within your portfolio, request a callback or call us on 1300 889 603.