

Buy
Metcash is an Australian wholesaler that supplies independent supermarkets, liquor stores and hardware stores through its food, liquor and hardware segments.
Institutional sell-side research rates it Buy because earnings per share are forecast to dip to A$0.23 in FY27 and then climb to A$0.27 in FY28 and A$0.31 in FY29, with EBITDA rising every year to A$934.7 million. Revenue forecasts were raised after the AGM update, and the recent forecast trims were not seen as material. Metcash also paid A$0.18 per share in dividends over the past twelve months, a trailing yield of 6.2 per cent, fully franked.
- Sell-side rating
- Buy
- Sell-side target
- A$3.90
- Upside to target
- +13.4%
- Initial price
- A$2.893 Oct 2026
- Last close
- A$3.4418 Nov 2026
After Metcash‘s AGM trading update, institutional sell-side research trimmed its earnings per share forecasts by around 1 per cent for FY27, 1 per cent for FY28 and 2 per cent for FY29, while nudging its revenue forecasts higher in each of those years. It described the changes as not material and left both the investment thesis and the price target unchanged. Institutional sell-side research has Metcash rated Buy with a 12 month price target of A$3.90, about 34.9 per cent above the share price of A$2.89 when this research was published. The trailing dividend yield is 6.2 per cent, fully franked, on A$0.18 of dividends per share over the past twelve months.
Research published 3 October 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Metcash
Metcash is an Australian wholesaler listed on the Australian Securities Exchange under the code MTS. It supplies independent supermarkets, liquor stores and hardware stores through its food, liquor and hardware segments. Its financial year ends in April, so FY26 covers the twelve months to April 2026 and FY27 covers the twelve months to April 2027. In FY26 the company reported revenue of A$19,628.4 million and EBITDA of A$761.7 million. EBITDA stands for earnings before interest, tax, depreciation and amortisation, and is a rough measure of the profit a business makes from its day-to-day operations before financing costs and accounting charges. Earnings per share for FY26 came in at A$0.24. Institutional sell-side research lists the company’s Project Horizon program among its key risks.
Forecast Changes After the AGM Update
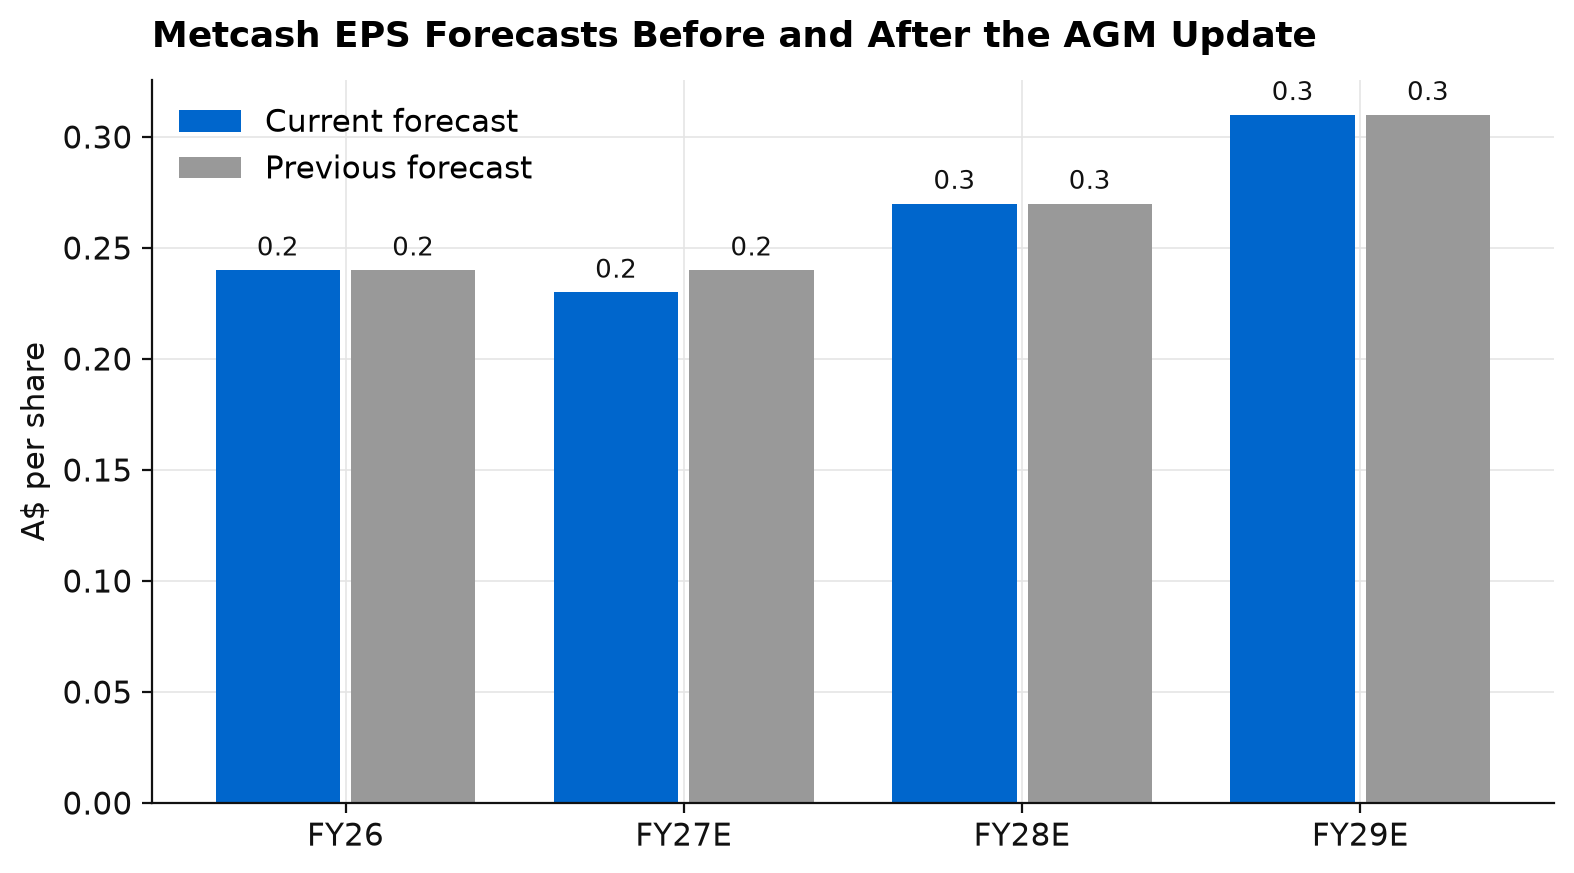
The AGM trading update showed how the current year is tracking, and institutional sell-side research has now worked it into its forecasts. The headline measure here is earnings per share, or EPS, which is the company’s profit divided by the number of shares on issue. The FY27 EPS forecast is now A$0.23, down from A$0.24 previously. The FY28 forecast stays at A$0.27 and the FY29 forecast stays at A$0.31 once rounded to the nearest cent, even though the underlying cuts to those two years were around 1 per cent and 2 per cent.
The research does not view the changes as material and kept its investment thesis, Buy rating and A$3.90 target.
On a half-year view, Metcash earned A$0.12 per share in the six months to October 2025 and A$0.13 in the six months to April 2026. For FY27, the research forecasts A$0.11 for the six months to October 2026, then A$0.13 for the six months to April 2027 to match the second half of FY26.
After the dip to A$0.23 in FY27, EPS is forecast to reach A$0.27 in FY28 and A$0.31 in FY29, a path the AGM update left almost unchanged.
Revenue Forecasts Moved the Other Way
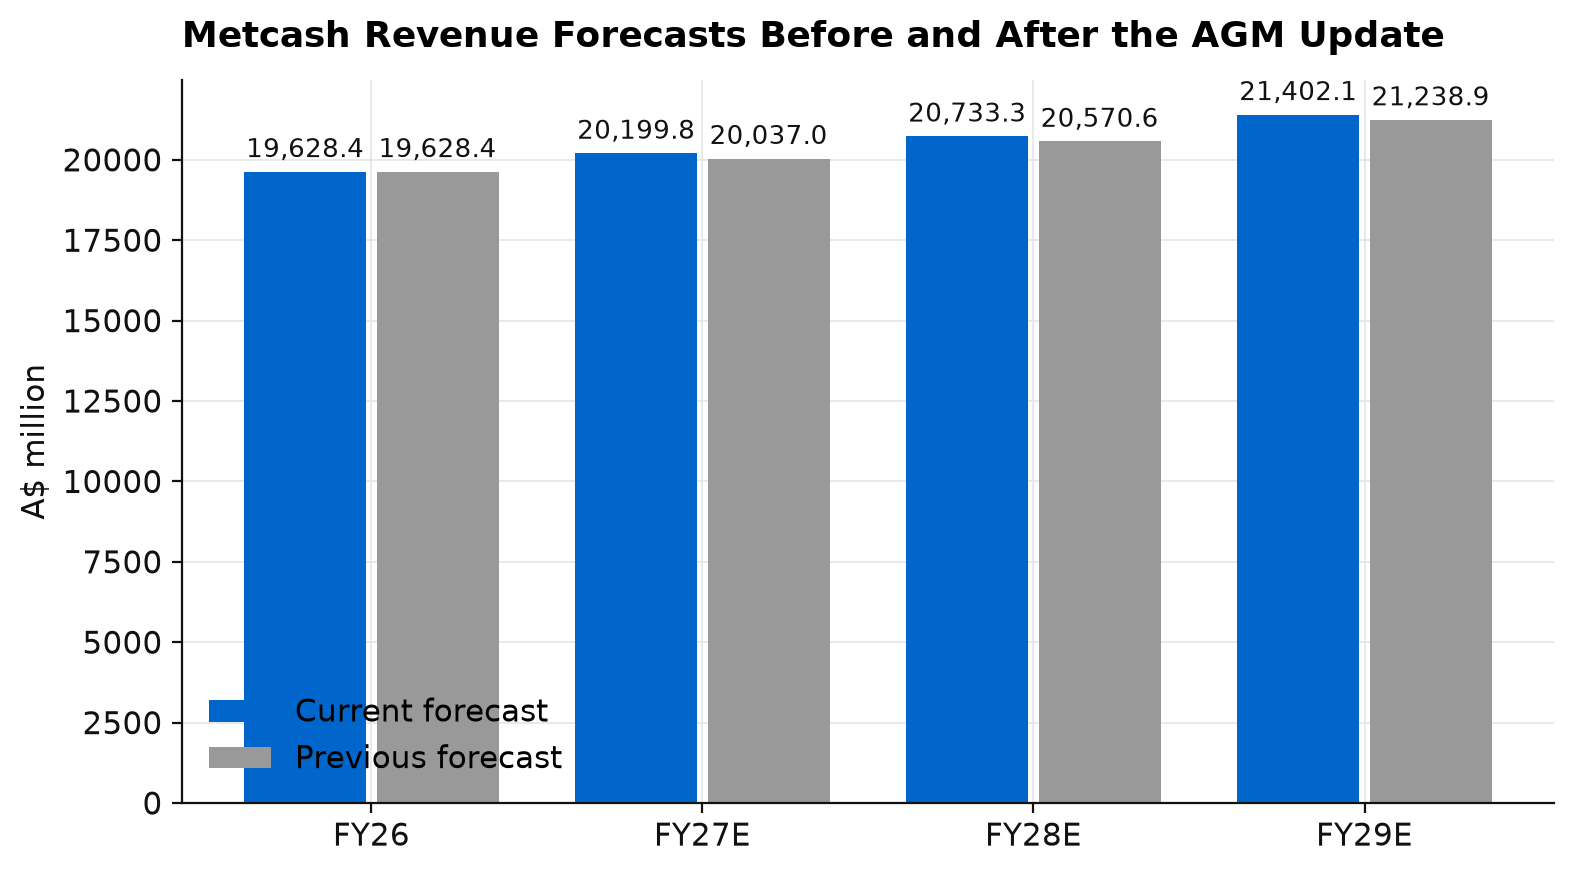
While EPS forecasts drifted lower, revenue forecasts went up in every year. FY27 revenue is now forecast at A$20,199.8 million, up from A$20,037.0 million. FY28 moves to A$20,733.3 million from A$20,570.6 million, and FY29 moves to A$21,402.1 million from A$21,238.9 million. Revenue is the total value of the goods the company sells before any costs come out.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARForecast revenue grows each year from A$19,628.4 million in FY26. Higher sales alongside slightly lower EPS means a slightly smaller share of each dollar of sales is now expected to end up as profit, and the research does not say why.
Tighter margins, meaning a smaller share of each sales dollar kept as profit, can come from cost pressure or from competition, and increased competition in supermarkets is one of the risks the research names.
Operating Earnings Build Toward FY29
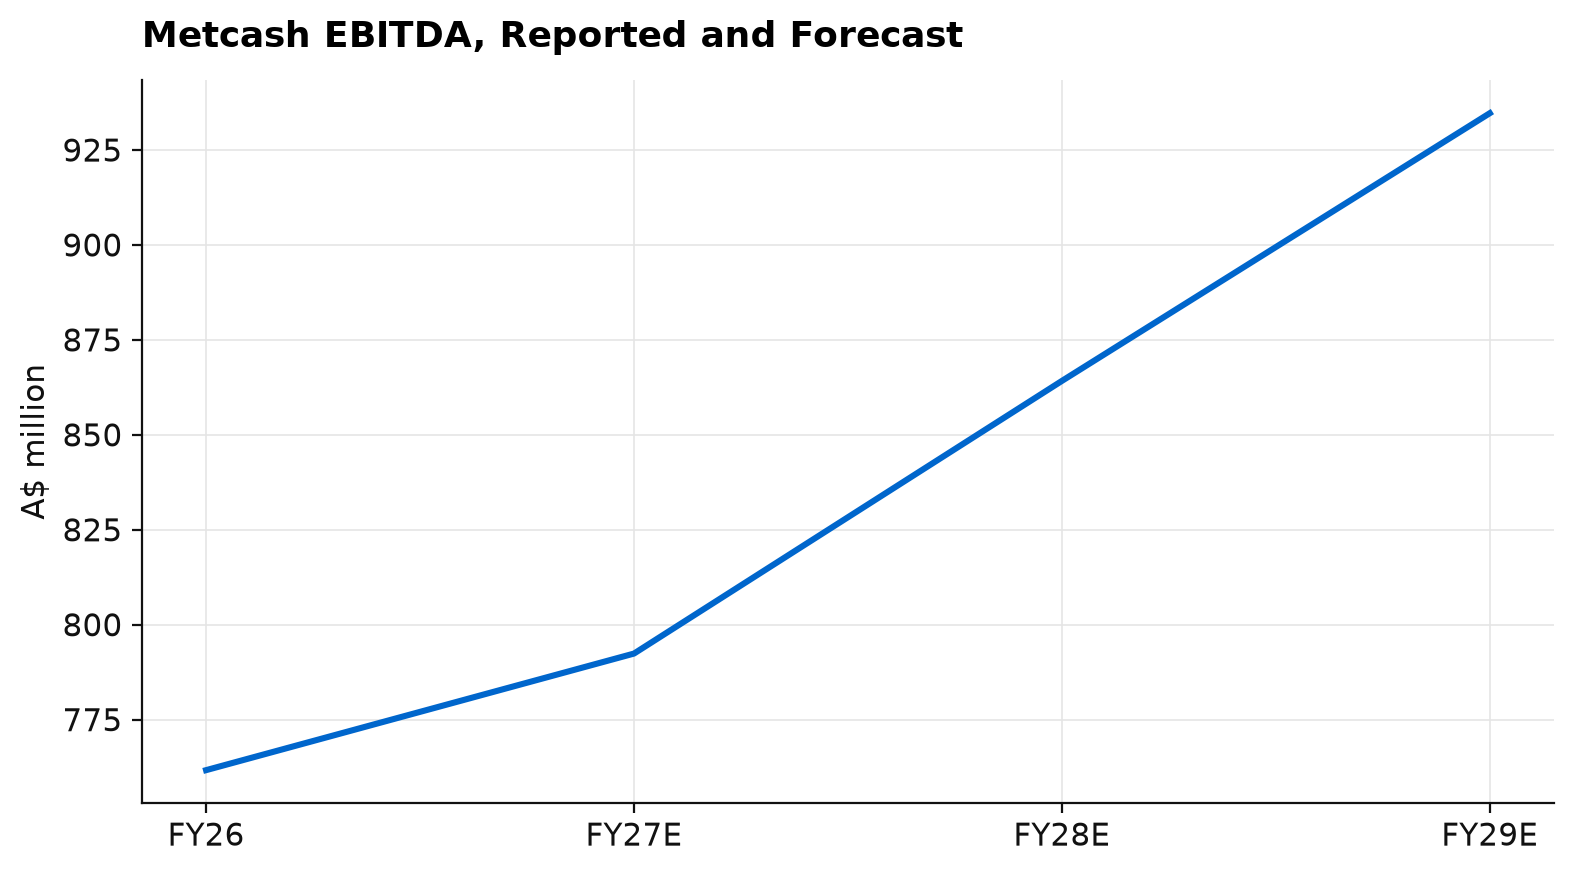
Below revenue, the research forecasts EBITDA rising from A$761.7 million reported in FY26 to A$792.4 million in FY27, A$864.2 million in FY28 and A$934.7 million in FY29, with the biggest increases in FY28 and FY29.
EBITDA is forecast to rise in FY27 even though EPS is forecast to dip from A$0.24 to A$0.23, with the difference made up by costs that sit below EBITDA, such as depreciation, interest and tax. In FY28 and FY29 both measures are forecast to rise together.
The research also tracks cash return on cash invested, which compares the cash the business generates each year with the cash that has been put into it. That measure was 13.4 per cent in FY26 and is forecast at 12.6 per cent in FY27, 12.6 per cent in FY28 and 12.5 per cent in FY29, so returns are forecast to hold broadly steady in the low teens. Capital allocation, meaning how management chooses to spend the company’s cash, is one of the risks the research names, alongside financial leverage.
Valuation and Income
The 12 month price target of A$3.90 was left unchanged after the AGM update. It sits about 34.9 per cent above the share price of A$2.89, while earnings forecasts were trimmed by around 1 to 2 per cent.
Three points in the forecasts support the Buy rating: EPS is forecast to dip to A$0.23 in FY27 and then climb to A$0.27 in FY28 and A$0.31 in FY29, with EBITDA rising every year to A$934.7 million; revenue forecasts were raised after the AGM update; and Metcash paid A$0.18 per share in dividends over the past twelve months, a trailing dividend yield of 6.2 per cent, fully franked.
Fully franked means the company has already paid Australian company tax on the profits those dividends come from, and the franking credits can reduce the tax an Australian investor pays, or be refunded to some low-tax investors. The research’s forecasts also show the dividend yield rising in each year to FY29 as earnings grow, although dividends are set by the board and can change.
Key Risks
A weaker macro environment, the first of five key risks the research names, would hurt the hardware business and the company’s other segments, and with them the forecast earnings recovery. More competition in supermarkets could squeeze both sales and margins. Project Horizon carries execution risk, and a setback there would weigh on the earnings path. Financial leverage could increase, meaning more debt relative to earnings and higher interest costs. Capital allocation is also a risk, since poor choices about how to spend the company’s cash could reduce cash returns that are already forecast to hold steady.
Our View
The research forecasts A$0.11 per share for the first half of FY27 and A$0.13 for the second, with earnings per share rising from FY28.
If you would like to discuss Metcash, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR