Hold
Sims recycles scrap metal in North America, Australia and New Zealand, and also recycles and repurposes computer equipment decommissioned from large data centres.
Institutional sell-side research rates it Hold because a strong US scrap business and an expected free cash flow improvement are balanced against a guided step down in first half FY27 data centre recycling earnings. Forecast EBITDA falls from A$837.4 million in FY27 to A$607.0 million in FY29, and net debt of A$358 million finished FY26 above expectations. Weak seaborne ferrous scrap markets add to the caution.
- Sell-side rating
- Hold
- Sell-side target
- A$24.80
- Upside to target
- +22.4%
- Initial price
- A$24.3317 Sep 2026
- Last close
- A$20.2629 Oct 2026
Sims reported underlying group EBIT of A$468 million for FY26, ahead of its own guidance range of A$420 million to A$435 million. Underlying group EBITDA, which also adds back depreciation and amortisation, came in at A$728 million. Both figures were above the research’s forecasts and market consensus, by about 6 per cent for EBITDA and about 10 per cent for EBIT, and the beat was mostly driven by the Sims Adams joint venture in the Southern US. Alongside the result, management guided to first half FY27 EBIT of A$75 million to A$90 million from Sims Lifecycle Services, its data centre recycling arm, down 30 to 40 per cent on the second half of FY26. Institutional sell-side research has Sims rated Hold with a 12 month price target of A$24.80, about 1.9 per cent above the share price of A$24.33 when this research was published.
Research published 17 September 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Sims
Sims is a metals and electronics recycler listed on the Australian Securities Exchange, reporting on a financial year that ends in June. Its scrap operations collect, process and sell ferrous scrap, meaning iron and steel, and non-ferrous scrap, meaning other metals. These operations run through North America Metals, which recently acquired Houston-based Tri Coastal Trading, the Sims Adams joint venture in the Southern US, and an ANZ business covering Australia and New Zealand, with a global trading arm alongside them. Total group scrap sales rose about 2 per cent in FY26. The other major business, Sims Lifecycle Services, repurposes and recycles computer equipment such as racks and memory chips that large data centres have decommissioned. It is adding a new facility in Ireland that is expected to contribute more to volumes in the second half of FY27.
Sims Adams Drove a Result Ahead of Guidance
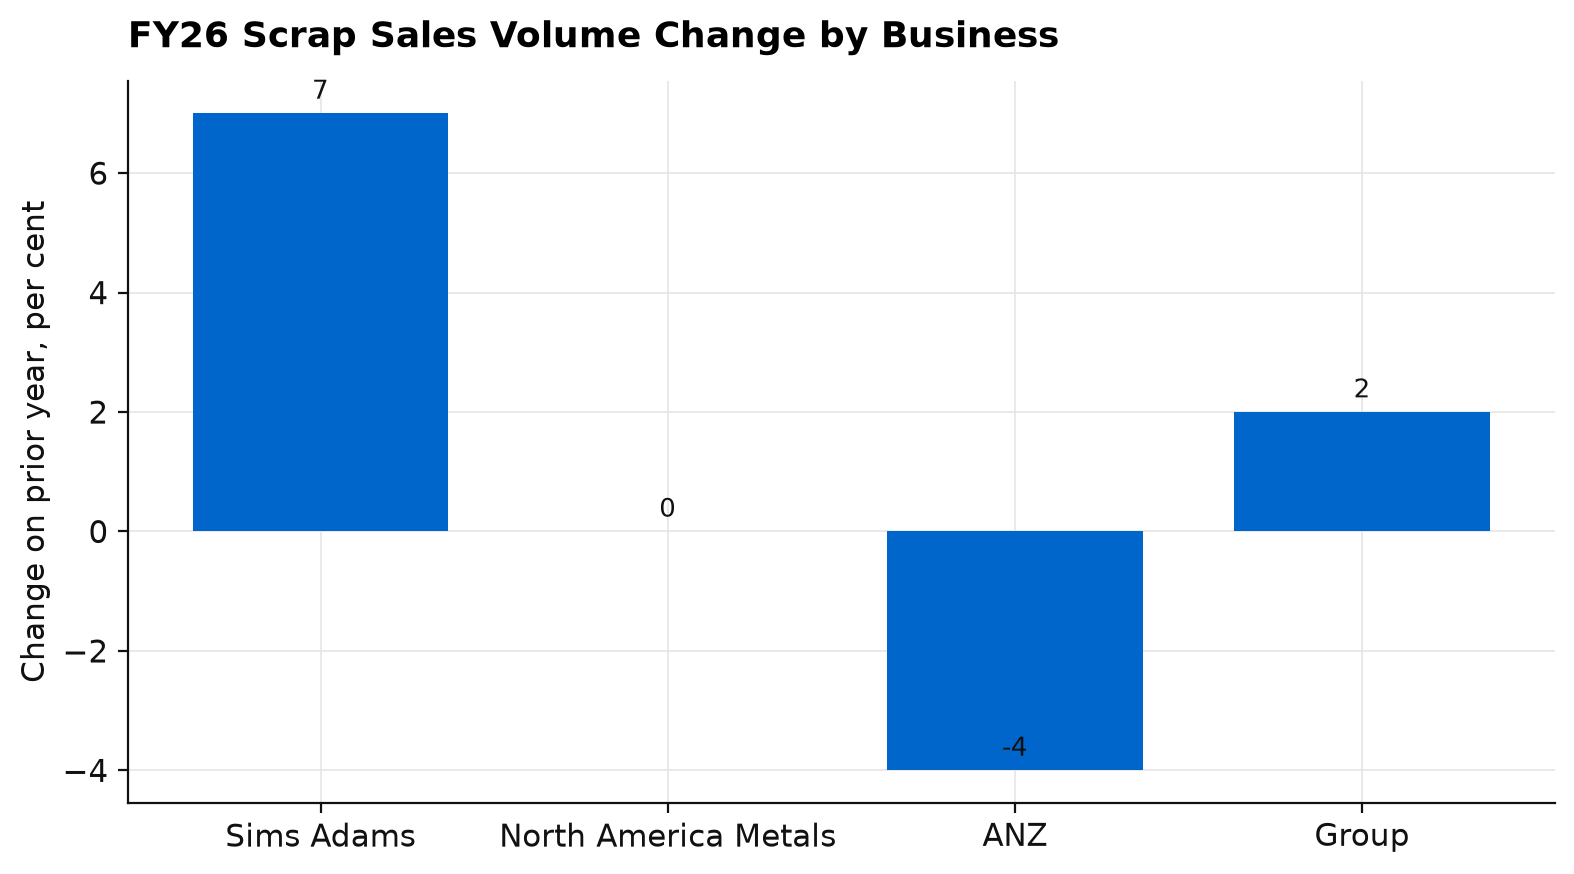
The Sims Adams joint venture delivered higher than expected volumes and margins in FY26, helped partly by acquisitions. Sims Adams lifted its scrap sales volumes by 7 per cent on the prior year. North America Metals volumes were flat and ANZ volumes fell 4 per cent, so total group scrap sales rose only about 2 per cent.
Group EBITDA margin, the share of each dollar of revenue that is left over as EBITDA, rose from 6 per cent to 9 per cent in FY26, a much larger move than the lift in volumes. Sims Lifecycle Services reported EBIT of A$190 million, above its guidance of A$170 million to A$175 million, so both of the businesses that beat expectations also lifted the group’s overall profitability.
North America Metals missed the research’s margin estimate, even though its ferrous scrap volumes benefited from the recent acquisition of Tri Coastal Trading. Management’s commentary on scrap markets described strong demand in the US for both non-ferrous and ferrous scrap, the same picture the research reports. The Sims Adams joint venture also added 12 sites through bolt-on acquisitions over the year.
The final dividend came in above the research’s estimate. Over the trailing twelve months Sims has paid dividends of A$0.27 a share, a yield of about 1.1 per cent on the share price of A$24.33, fully franked. SMSF trustees can use the attached franking credits to offset tax.
Data Centre Recycling Faces a Softer First Half
Sims Lifecycle Services repurposed 11.5 million computer racks and chips in the June half, double the previous level. Industry pricing data from TrendForce shows that the price of DDR4 memory, a widely used type of computer memory chip, remains strong.
Even so, management expects first half FY27 EBIT from Sims Lifecycle Services of A$75 million to A$90 million. That range is down 30 to 40 per cent on the second half of FY26, and well below the A$121 million the research had previously forecast for the half. Management attributes the drop to a temporary memory mix issue, meaning a shift in the blend of chip sizes coming through the business, which affects how much each unit earns.
The timing of data centre decommissioning by the roughly seven hyperscalers remains variable. The retirement schedules of these large cloud computing companies decide how much equipment, and what type, flows through Sims Lifecycle Services. The new facility in Ireland is expected to contribute more to volumes in the second half of FY27.
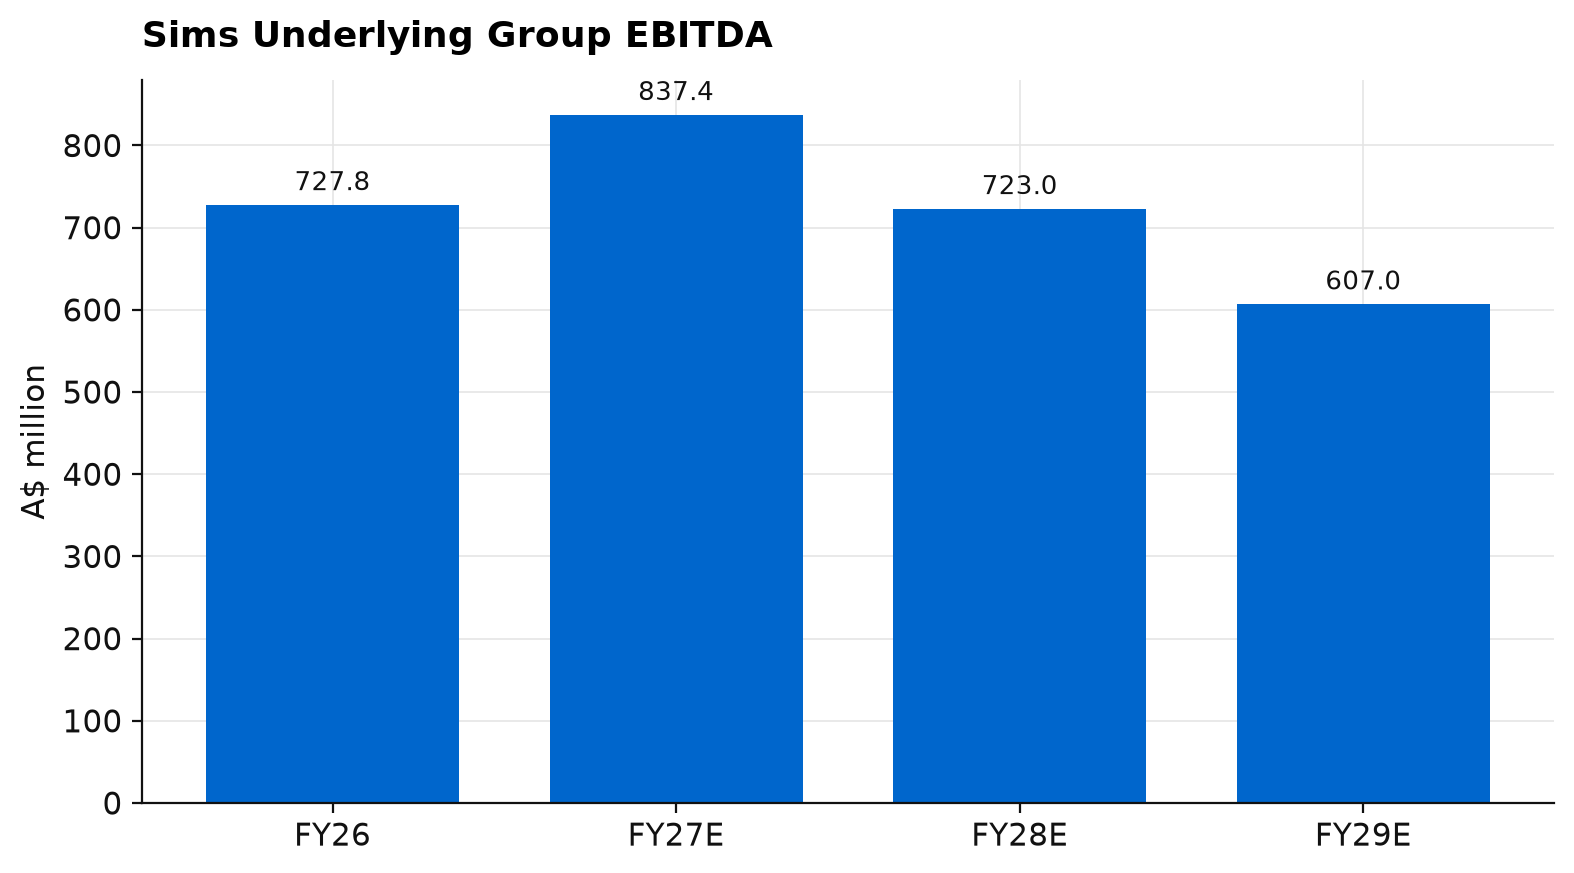
The research has raised its FY27 EBITDA forecast, upgrading its Sims Adams earnings after the strong result and assuming Sims Lifecycle Services earnings increase again in the second half of FY27. It now forecasts group EBITDA rising about 15 per cent in FY27 to around A$840 million, or A$837.4 million in its detailed forecasts, with about 70 per cent of that driven by the Sims Adams scrap businesses. Further out, it has cut FY28 and FY29 EBITDA after moderating earnings from Sims Lifecycle Services and North America Metals over the medium term. Forecast EBITDA falls to A$723.0 million in FY28 and A$607.0 million in FY29, both below the A$727.8 million reported for FY26.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARThe research describes Sims Lifecycle Services as earning a high return on capital employed, or ROCE, meaning a lot of profit on the money tied up in it, so a recovery in its earnings tends to flow through to cash.
US Scrap Demand Holds Up as Export Markets Stay Weak
High levels of Chinese steel exports and low global steel prices continue to suppress seaborne ferrous scrap markets, where scrap is shipped overseas to steel mills in other countries. The research expects this to keep affecting North America Metals, Sims Adams and ANZ. Management’s commentary on export markets was consistent with that, describing them as challenging because of competition from sustained high Chinese steel exports.
North America Metals and Sims Adams continue to sell more of their ferrous volumes to US domestic steel mills, which reduces their reliance on those weaker export markets. Non-ferrous pricing in the US is also a tailwind for the scrap business.
In ANZ, where volumes fell 4 per cent in FY26, management thinks earnings are close to a bottom because of growth from future electric arc furnaces. Among its upside risks, the research lists positive long-term scrap industry trends and volume growth from more EAF capacity, since electric arc furnaces make steel by melting scrap with electricity and so lift local scrap demand.
Net debt, excluding leases, rose to A$358 million at year end, considerably higher than the research’s estimate of about A$200 million. The increase came from bolt-on acquisitions by the Sims Adams joint venture across 12 sites, a build in receivables associated with non-ferrous volumes, and higher cash capital expenditure. The research expects the scrap business to generate strong positive free cash flow in the first half of FY27, helped by a working capital unwind and dividends from Sims Adams.
Sims sees ongoing consolidation in the US and Australian scrap industries, with acquisition opportunities. It sees no further need to invest in new shredders, as its existing facilities are running at 60 to 70 per cent utilisation.
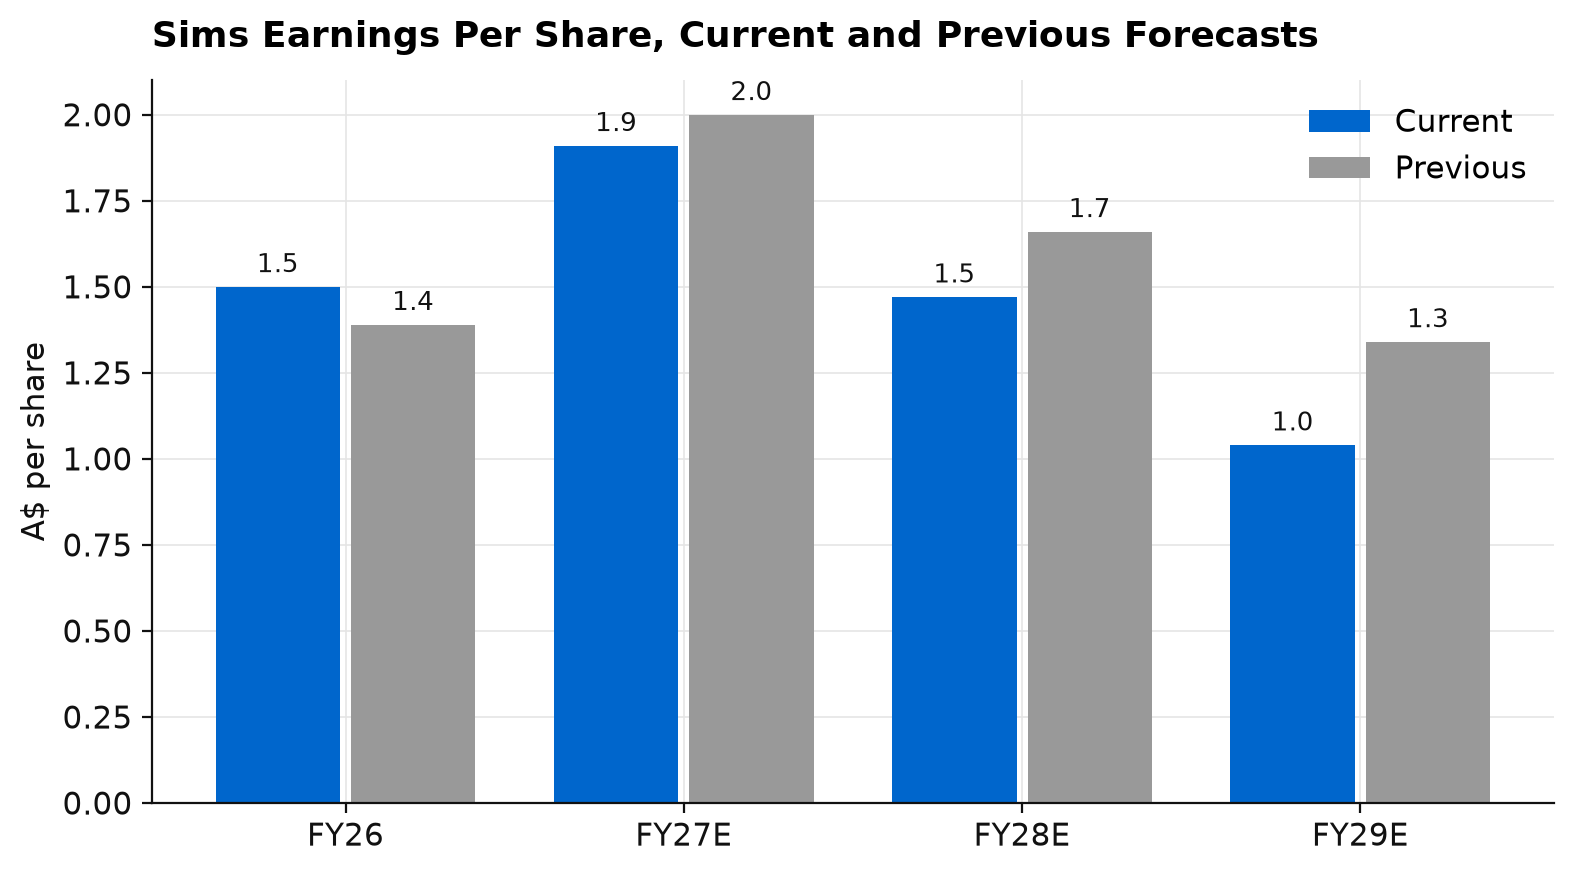
Forecast earnings per share, or EPS, is now A$1.50 for FY26, A$1.91 for FY27, A$1.47 for FY28 and A$1.04 for FY29, against previous figures of A$1.39, A$2.00, A$1.66 and A$1.34. Revenue forecasts have also been lowered, with FY27 now at A$8,626.5 million against A$9,243.0 million before, and FY28 at A$8,844.9 million against A$9,150.9 million. The research forecasts ROCE rising from 11.2 per cent in FY26 to 14.2 per cent in FY27, then easing to 11.1 per cent in FY28 and 8.1 per cent in FY29.
Valuation and Why the Rating Is Hold
The 12 month price target of A$24.80 sits about 1.9 per cent above the share price of A$24.33 when this research was published. The target was lowered 4 per cent from A$25.90 after the FY26 result, reflecting the moderated medium-term outlook for Sims Lifecycle Services and North America Metals. On trailing dividends of A$0.27 a share, the yield is about 1.1 per cent, fully franked.
Group EBITDA is forecast to rise about 15 per cent to around A$840 million in FY27, which is the first support for the target. Sustaining capital expenditure, the spending needed just to keep existing plants running, is low in the scrap business, and Sims Lifecycle Services earns a high return on capital, so the research expects free cash flow to improve significantly in FY27 and FY28. The second support is the US domestic scrap market, where demand for both ferrous and non-ferrous scrap is strong and Sims Adams has added 12 sites. Sims has estimated, from a desktop review only, that its land portfolio could be worth about A$1.5 billion above book value, with about A$500 million attributable to ANZ and about A$1 billion to North America Metals.
EBITDA is forecast to drop from A$837.4 million in FY27 to A$607.0 million in FY29, and EPS from A$1.91 to A$1.04, as the research moderates earnings in Sims Lifecycle Services and North America Metals. Seaborne ferrous scrap markets remain weak, the first half of FY27 carries a guided step down in data centre recycling earnings, and net debt finished FY26 at A$358 million, well above what the research had expected.
Existing holders have reasons to stay, including a strong US scrap franchise, an expected free cash flow improvement and the possibility of a second-half recovery in Sims Lifecycle Services. Anyone considering a new position at A$24.33 has little room to the A$24.80 target, and we would wait for the first half FY27 result to confirm the recycling business is recovering before adding exposure.
Key Risks
On the macro side, a slowdown in the global economy, cost inflation such as higher freight and labour rates, and continued pressure on seaborne ferrous scrap from high Chinese steel exports could all weigh on scrap earnings. Developments in Iran and the neighbouring region add a further downside risk, as they may affect the Suez Canal, freight costs and Turkish scrap prices and demand. On the competitive side, the timing of data centre decommissioning by around seven hyperscalers remains variable, and a less favourable memory mix could keep Sims Lifecycle Services earnings lower for longer than management expects. On execution, Sims carries project execution risks, and ongoing industry consolidation brings the possibility of value-dilutive acquisitions. Net debt of A$358 million is also higher than the research expected, which leaves less room if the first half free cash flow recovery is slower than forecast. Upside risks include increased scrap availability, improving scrap prices, higher Sims Lifecycle Services earnings, more EAF capacity and asset sales.
Our View
We think the FY26 result showed the US scrap business, and Sims Adams in particular, is in good shape, with bolt-on acquisitions adding volume in a market where domestic steel mills are taking more ferrous scrap. We would watch Sims Lifecycle Services most closely, because it depends on the decommissioning schedules of a small group of hyperscalers, which makes its half-to-half earnings hard to predict. We would rather see the first half FY27 result land inside the A$75 million to A$90 million guidance range, and the Ireland facility start lifting volumes, before treating the second-half recovery as settled. The expected working capital unwind is the other near-term check, because it is the clearest path to bringing net debt back down from A$358 million.
If you would like to discuss Sims, request a callback or call us on 1300 889 603.
Financial Summary
Learn to trade with a plan
Our free 5-day course covers entries, exits and risk management.
Start the free courseBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR