

Hold
Woolworths is a large Australian retailer whose core is its supermarkets and online grocery business, alongside New Zealand food, Big W and the Cartology advertising arm.
Institutional sell-side research rates it Hold because the shift to everyday low pricing cuts margin now and only pays back if sales respond. Online growth is also running into store capacity limits, and Cartology's profit contribution is not broken out. Against that, earnings per share are forecast to rise from A$1.13 in FY25 to A$1.69 in FY28E.
- Sell-side rating
- Hold
- Sell-side target
- A$41.00
- Upside to target
- −2.4%
- Initial price
- A$38.4725 Sep 2026
- Last close
- A$41.9918 Nov 2026
Woolworths has told the market what it is now aiming for: sales growth, with margin a secondary concern. At its FY26 sell-side briefing, the company said it would use its scale to grow sales, expected EBIT dollars to follow, and would accept whatever margin that growth produces. That reset comes with a shift toward everyday low pricing, a store-led online model that is starting to bump into capacity limits, and a retail media arm, Cartology, that management believes is chasing a $9 billion addressable market. Institutional sell-side research has Woolworths rated Hold with a 12 month price target of A$41.00, about 6.6 per cent above the share price of A$38.47 when this research was published.
Research published 25 September 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Woolworths
Woolworths Group is a large Australian retailer listed on the Australian Securities Exchange under the code WOW. Its core is the Australian food business, which runs the group’s grocery stores and an online grocery operation that picks most orders in those stores. The group also includes the New Zealand food business, the discount department store chain Big W, and Cartology, the group’s retail media arm, which sells advertising to the brands whose products appear in Woolworths stores and online. It also runs a customer rewards program that supports its pricing offer. Woolworths reports on a financial year ending in June, so FY26 refers to the year to June 2026, and the latest briefing followed that full-year result.
Sales First and a Move to Everyday Low Pricing
At the briefing, Woolworths said it has refocused on using its scale to drive better outcomes for all stakeholders. Management expects growth in EBIT dollars to follow from higher sales. EBIT stands for earnings before interest and tax, a measure of the profit a business makes from its operations before financing costs.
The main tool for lifting sales in the Australian food business is pricing. Woolworths is moving more toward EDLP, or everyday low pricing, and rebalancing away from what the industry calls High Low promotions. Under a High Low approach, shelf prices sit higher most of the time and are cut sharply for short promotional windows, while everyday low pricing keeps prices steadier and lower across the week. Woolworths gave two reasons for the shift. The first is that High Low has reduced customer trust in pricing, because shoppers learn to wonder whether the price they see today is the real one. The second is that it creates volatility in volumes, with demand spiking during a promotion and falling away afterwards, and that volatility makes the supply chain less efficient.
Every promotional spike forces a retailer to line up extra stock, labour and transport for a few days before demand drops back again, so smoother volumes should mean steadier ordering and fewer gaps on the shelf. The company acknowledged that some suppliers are reluctant to shift toward EDLP. Woolworths expects them to see the value as the sales results come through.
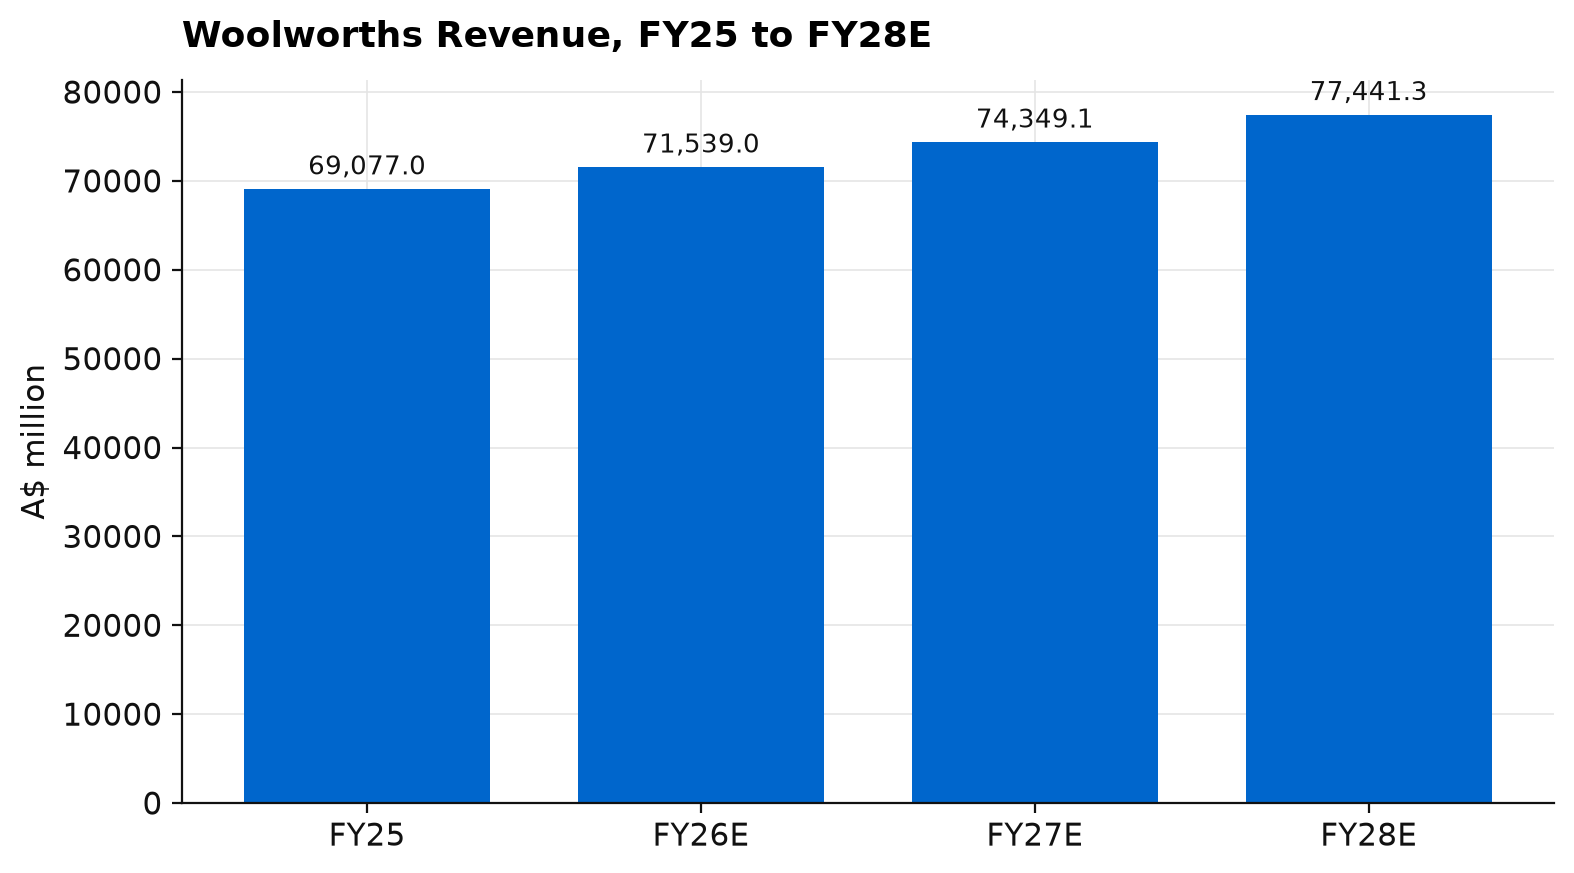
Woolworths expects to hold a margin advantage over rivals over the medium term, though it noted that competitors are taking differing investment approaches, and how hard they push on price is outside its control. The research forecasts revenue rising from A$69,077.0 million in FY25 to A$71,539.0 million in FY26E, A$74,349.1 million in FY27E and A$77,441.3 million in FY28E.
Online Capacity and the Cartology Advertising Opportunity
Woolworths fulfils most of its online grocery orders from its stores, with staff picking items off the shelves. The alternative is a large dedicated warehouse, known as a customer fulfilment centre, or CFC. The company remains confident in its mostly store-based model. It says picking orders close to where people live gets them to customers sooner, and that the model is more profitable, because the savings on the last mile, the final step of getting an order from the store to the customer, offset picking costs that are slightly higher in a store than in a CFC.
Close to 200 stores are running online penetration of more than 20 per cent, meaning online orders make up more than 20 per cent of their sales. Some of those stores are becoming capacity constrained, since each has only so much space and so many staff to handle pick-up and delivery on top of the shoppers walking its aisles. Woolworths is freeing up capacity with direct to boot, where customers drive in and have their order loaded straight into the car. Store renewals are also being used to reset how space is allocated inside each store.
Woolworths has begun charging Sunday surcharges, because Sunday is a peak demand day and Sunday wage rates make orders more expensive to fulfil.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARThe second growth engine discussed was Cartology, the group’s retail media business, which sells advertising to brands through Woolworths’ own channels so their products reach shoppers as they decide what goes in the trolley. Cartology revenue grew around 10 per cent in FY26, and Woolworths expects that growth rate to accelerate as it begins to capture advertising market revenue from suppliers, in effect winning share from the likes of Google and Meta. To get there, the company will invest more in advertising technology and expand its self-service offering, so brands can set up and run campaigns themselves.
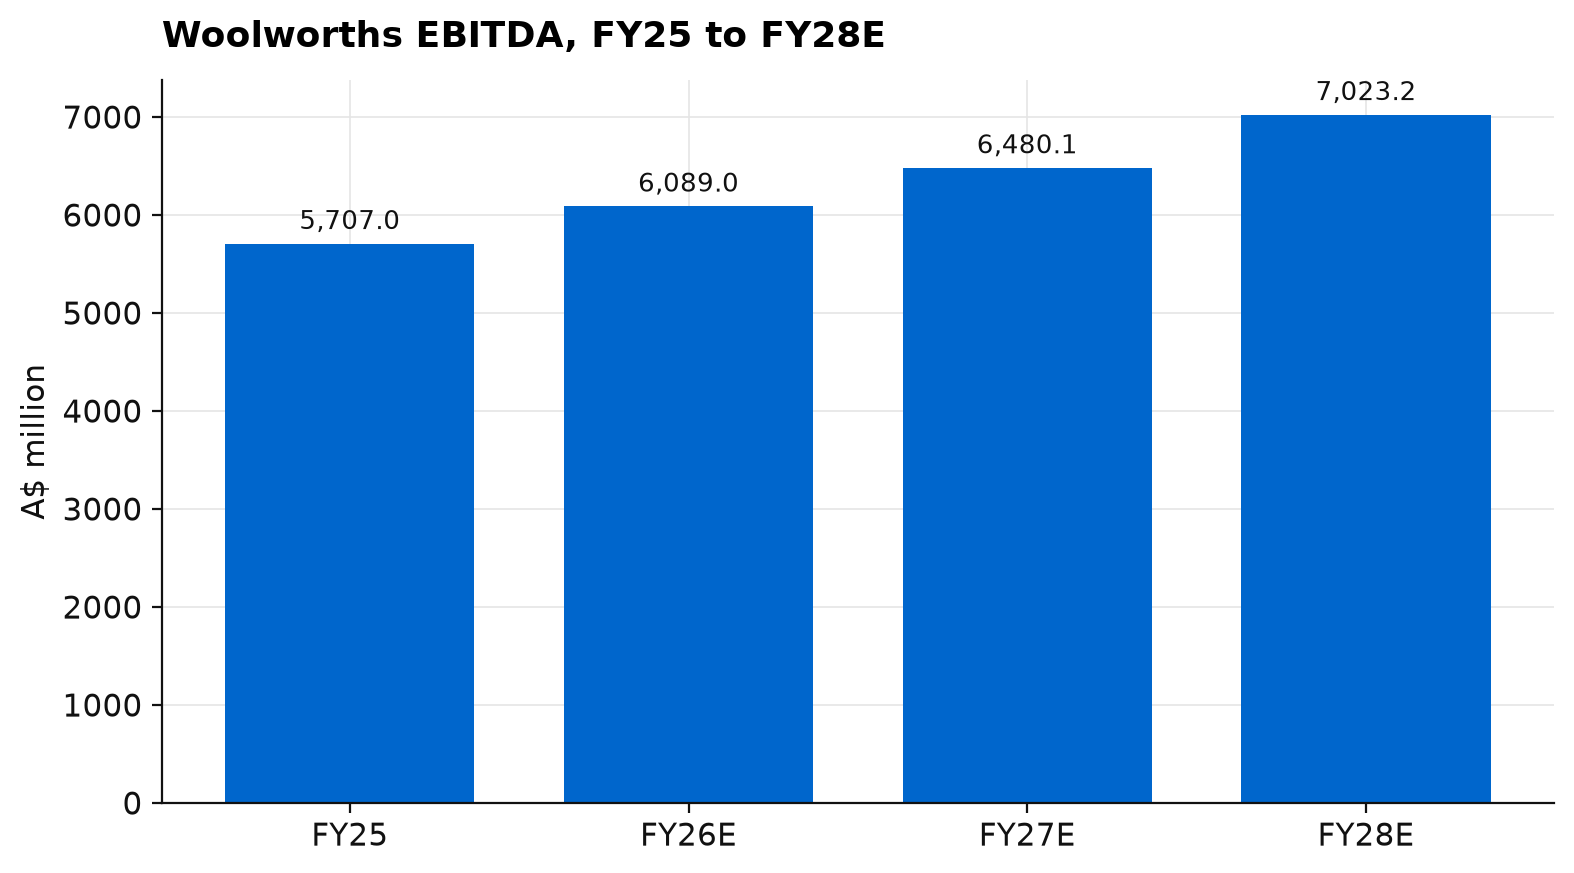
Woolworths puts the Australian addressable market for branded advertising across food and everyday needs at $9 billion. At group level, the research forecasts EBITDA, which is earnings before interest, tax, depreciation and amortisation, rising from A$5,707.0 million in FY25 to A$6,089.0 million in FY26E, A$6,480.1 million in FY27E and A$7,023.2 million in FY28E.
Margin Pressures, New Zealand Lessons and the Big W Reset
Gross margin is what is left from sales after paying for the goods themselves, before running costs such as wages and rent. In the second half of FY26, the share of sales made on yellow ticket promotions, the familiar shelf discounts, declined slightly compared with a year earlier, so more was sold at regular prices and gross margin benefited.
Margin was held back by more investment in meat prices than a year earlier, as meat was a key pricing focus. Woolworths also ran an additional continuity program (a collectable offer over several weeks to keep shoppers coming back, this time featuring saucepans), put more into the rewards program and faced higher fuel costs.
Prior to Christmas in 2025, Woolworths changed its store operating model in New Zealand, rationalising store manager headcount, and it did not go to plan. More staff in key roles, such as bakery, accepted redundancy than expected, and learning curves in e-commerce affected availability, meaning products were not always there when customers wanted them, which ultimately hurt sales. The company says the changes are now embedded and performance is back to prior levels. Woolworths will consider bringing this model to Australia, but wants to make sure it understands the benefits first.
Big W has now been reset, and management says growth from here should come from getting more sales out of the existing business. Management named four levers, starting with a bigger own brand range, as own brand penetration is still well below Kmart. The second is a focus on hero brands as part of its budget offering, well-known names such as Apple, Lego and small appliance brands. The third is an improved online experience, with on demand delivery enabled in the last few weeks. The fourth is a new store format, which management says is lifting sales.
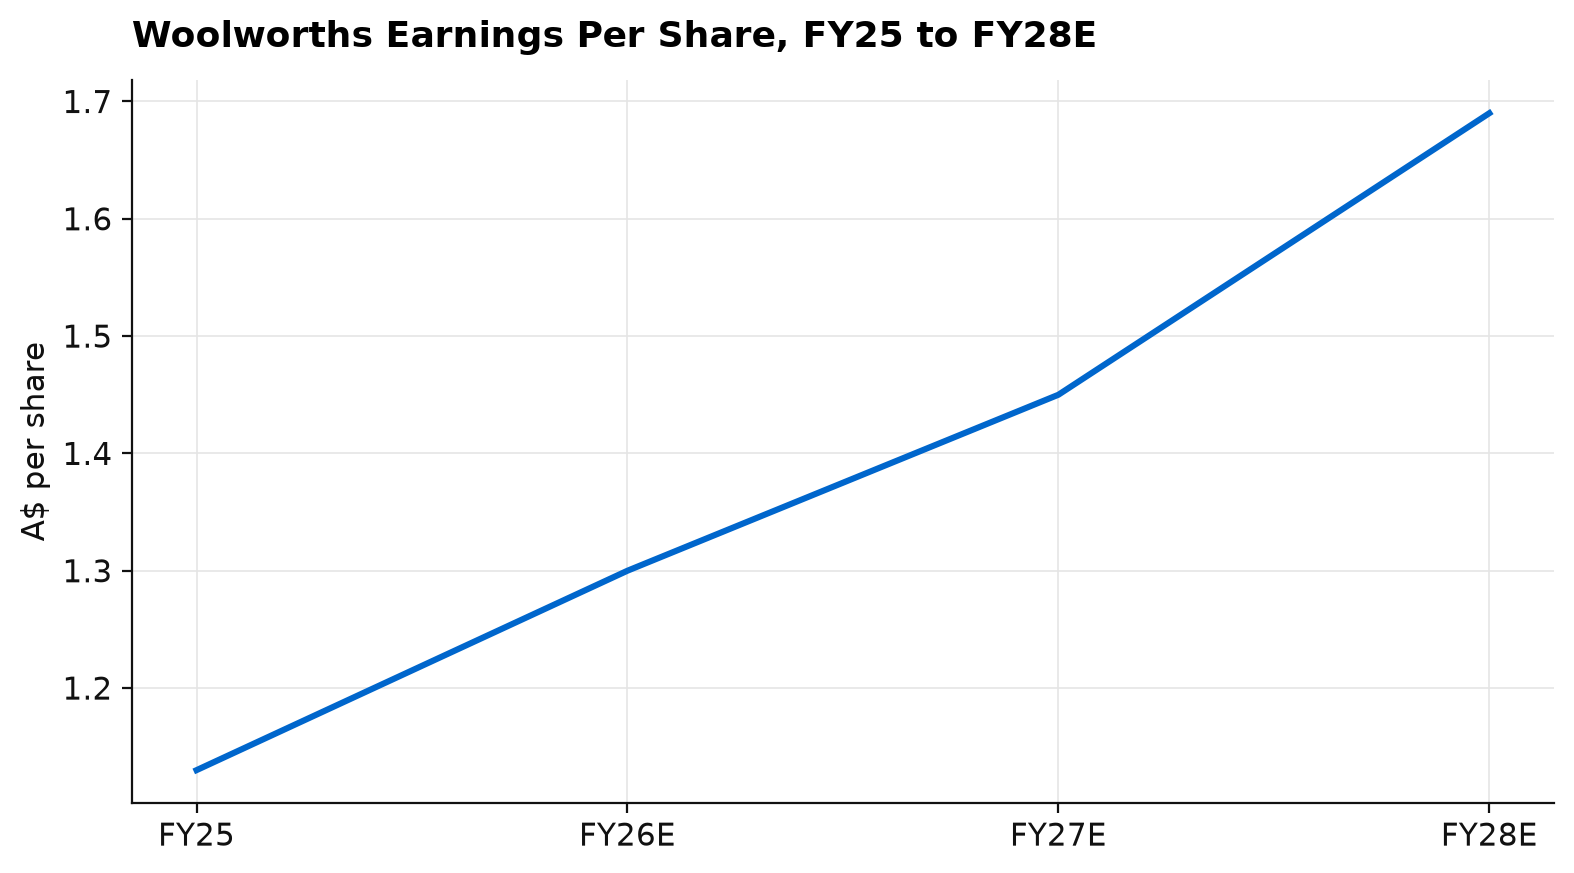
The research forecasts earnings per share of A$1.13 in FY25, rising to A$1.30 in FY26E, A$1.45 in FY27E and A$1.69 in FY28E. Split into halves, the research shows A$0.70 for the half to December 2025 and A$0.60 for the half to June 2026, which together make up the A$1.30 for the year.
Valuation and Why the Gap Is Narrow
Institutional sell-side research sets a 12 month price target of A$41.00 for Woolworths, about 6.6 per cent above the share price of A$38.47 when this research was published. The shares also pay a trailing dividend of A$0.97 per share, a trailing yield of 2.5 per cent, fully franked. Full franking means the company has already paid Australian tax on the profits behind the dividend, and eligible investors, including many SMSF trustees, can use the attached credits against their own tax.
On the positive side, the pricing reset could rebuild customer trust and smooth volumes through the supply chain, the company believes its store-led online model is more profitable than the warehouse alternative, and Cartology is expected to grow faster against a $9 billion addressable market. The research forecasts earnings per share moving from A$1.13 in FY25 to A$1.69 in FY28E.
On the negative side, price investment costs margin today and only pays back if sales respond, online growth is starting to run into store capacity, and Cartology’s profit contribution is not broken out.
Key Risks
If the move to everyday low pricing and the investment in areas like meat fail to sustain sales momentum against Coles, Woolworths will have given up margin without the extra volume to justify it. Rivals are taking differing investment approaches, and a more aggressive response on price could lead to further margin declines. Benefits from supply chain investment may arrive more slowly than expected, while online capacity constraints add pressure in the busiest stores. Availability deteriorated in New Zealand after the operating model change and would hurt sales quickly if it slipped in Australia. On the upside, a stronger than expected payoff from price investment, or faster supply chain benefits, could take the shares above the target.
Our View
We think it helps investors that Woolworths has set out the margin cost of its sales push up front. Moving away from High Low promotions also makes sense to us, because shoppers who do not trust shelf prices are easier for a competitor to win. The caution on New Zealand looks sensible too, and we would want the operating model proven there before it reaches Australian stores, so the availability problems are not repeated at home. Our main concern is timing, because price investment shows up in the accounts straight away while the payback in sales, supplier support and supply chain efficiency arrives over time. We will be watching the next few trading updates for signs that volumes are holding up under the new pricing.
If you would like to discuss Woolworths, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR