

Sell
Domino's Pizza Enterprises runs Domino's pizza stores across Australia, New Zealand, Japan and other countries under licence from the global brand owner, Domino's Pizza Inc.
Institutional sell-side research rates it Sell because the brand owner has named the company a primary drag on International same-store sales and cut its international guidance to flat. Franchisee profits are down, limiting new stores, and the network shrank by a net 10 stores in the first quarter of fiscal 2027. Forecast earnings per share rise only from A$1.28 to A$1.34 by fiscal 2029, so the research sees a recovery already priced in.
- Sell-side rating
- Sell
- Sell-side target
- A$18.00
- Upside to target
- −27.7%
- Initial price
- A$22.459 Nov 2026
- Last close
- A$24.9119 Nov 2026
Domino’s Pizza Enterprises is the largest listed operator of Domino’s stores outside the United States, and the company that owns the global brand has once again singled it out as a primary drag on its international sales. On its latest investor call, Domino’s Pizza Inc, the US-listed brand owner and master franchisor, said the operational results at Domino’s Pizza Enterprises continue to weigh on International same-store sales. It cut its international guidance to flat, and said that if results do not recover in the markets Domino’s Pizza Enterprises operates, it could consider shifting to another franchisor. A new chief executive, Andrew Gregory, started at Domino’s Pizza Enterprises in August 2026, and the turnaround he has inherited looks likely to take time. Institutional sell-side research has Domino’s Pizza Enterprises rated Sell with a 12 month price target of A$18.00, about 19.8 per cent below the share price of A$22.45 when this research was published.
Research published 9 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Domino’s Pizza Enterprises
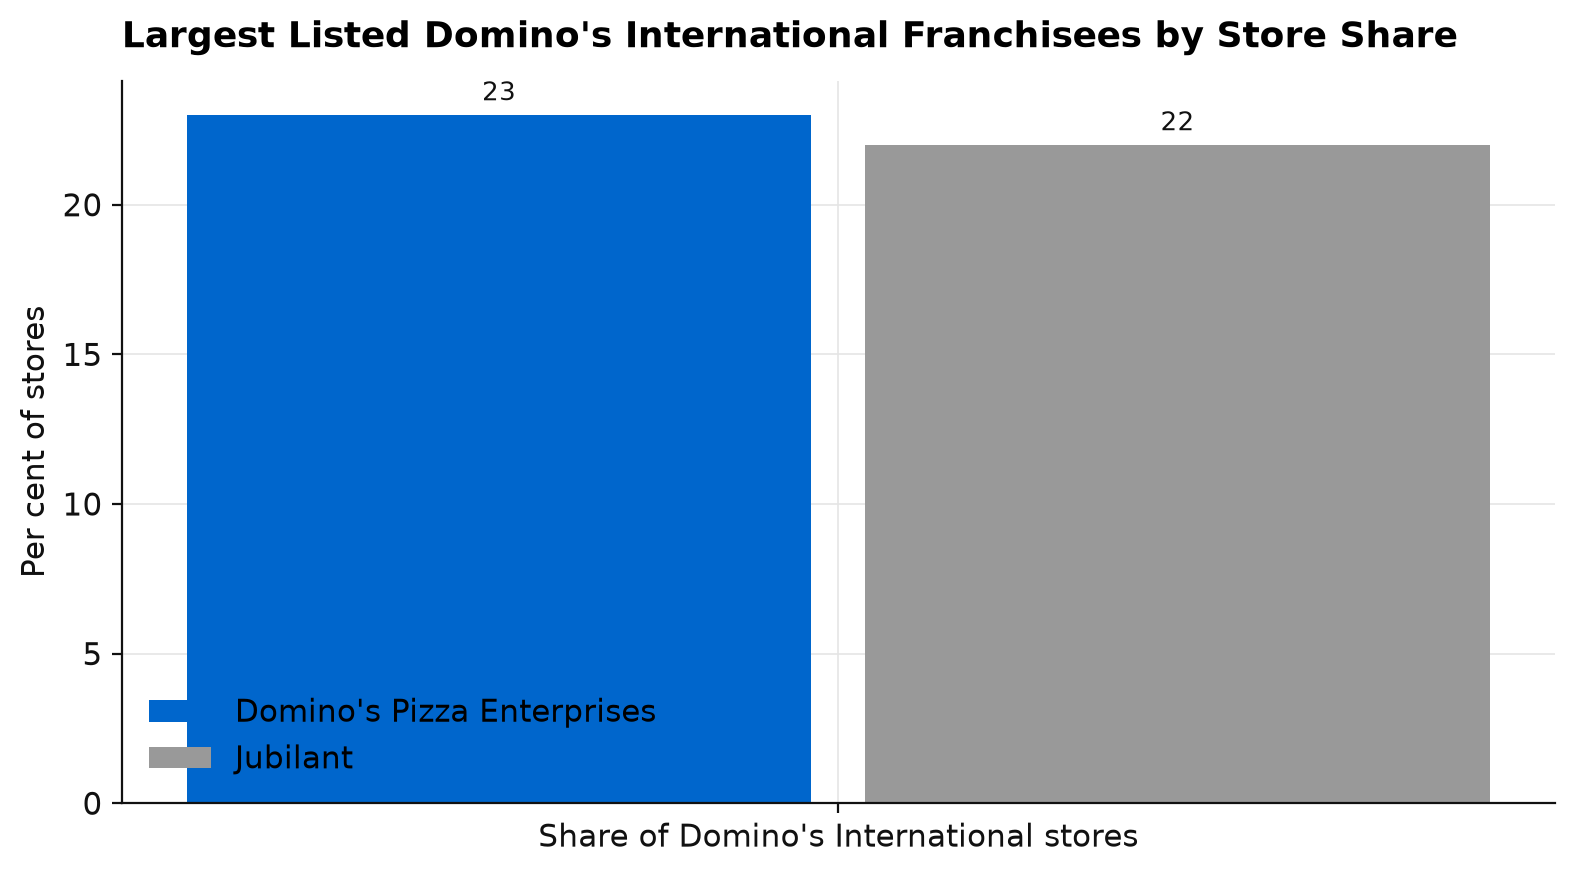
Domino’s Pizza Enterprises is listed on the Australian Securities Exchange under the code DMP. It is a franchisee of the Domino’s brand, which means it runs Domino’s stores across a group of countries under licence from the global brand owner, Domino’s Pizza Inc. It is the largest of the listed Domino’s International franchisees, holding 23 per cent of Domino’s International stores, just ahead of Jubilant on 22 per cent. The company reports its store network by geographic segment, with Australia and New Zealand and Japan among them. The global brand owner sets the brand, technology and menu strategy that Domino’s Pizza Enterprises deploys in its own markets, while day-to-day execution and the country mix are its own. The company reports on a June financial year, and Andrew Gregory became chief executive in August 2026.
The Brand Owner Flags a Drag on International Sales
Domino’s Pizza Inc, the global brand owner and master franchisor, holds the name, the technology and the menu playbook, and licenses large franchisees in each region to run the stores. Domino’s Pizza Enterprises is the largest of these, with 23 per cent of Domino’s International stores, ahead of Jubilant on 22 per cent, so its results have a large effect on the international numbers the brand owner reports to its own shareholders every quarter.
Because the brand owner sets the global brand, technology and menu strategy that the Australian-listed franchisee rolls out, what it says about international sales, digital and loyalty trends, and franchisee health is an early signal for Domino’s Pizza Enterprises. Results at the franchisee can still differ, given its own mix of countries and the way it runs its stores.
On the latest call, the brand owner again singled out Domino’s Pizza Enterprises as a primary detractor from International same-store sales growth. It said it has become more positive on the franchisee’s management team, but that the operational results continue to drag, and that if results do not recover in the markets Domino’s Pizza Enterprises operates, it could consider shifting to another franchisor.
The brand owner’s new chief executive, Joe Jordan, commenced in October 2026, and Andrew Gregory became chief executive of Domino’s Pizza Enterprises in August 2026. Institutional sell-side research expects the strategic turnaround at Domino’s Pizza Enterprises to take time. The research is looking for evidence of improved same-store sales growth, feeding through to franchisee profitability and supporting demand for new stores, before turning more positive.
Fewer Orders by Design Is Weighing on Sales
Same-store sales growth is the change in sales at stores that were already trading a year earlier. It leaves out the effect of new store openings, so it is the cleanest gauge of whether existing restaurants are doing more business. For a franchise system it matters twice over, because franchisee profits depend on it, and franchisee profits drive the appetite to open new stores.
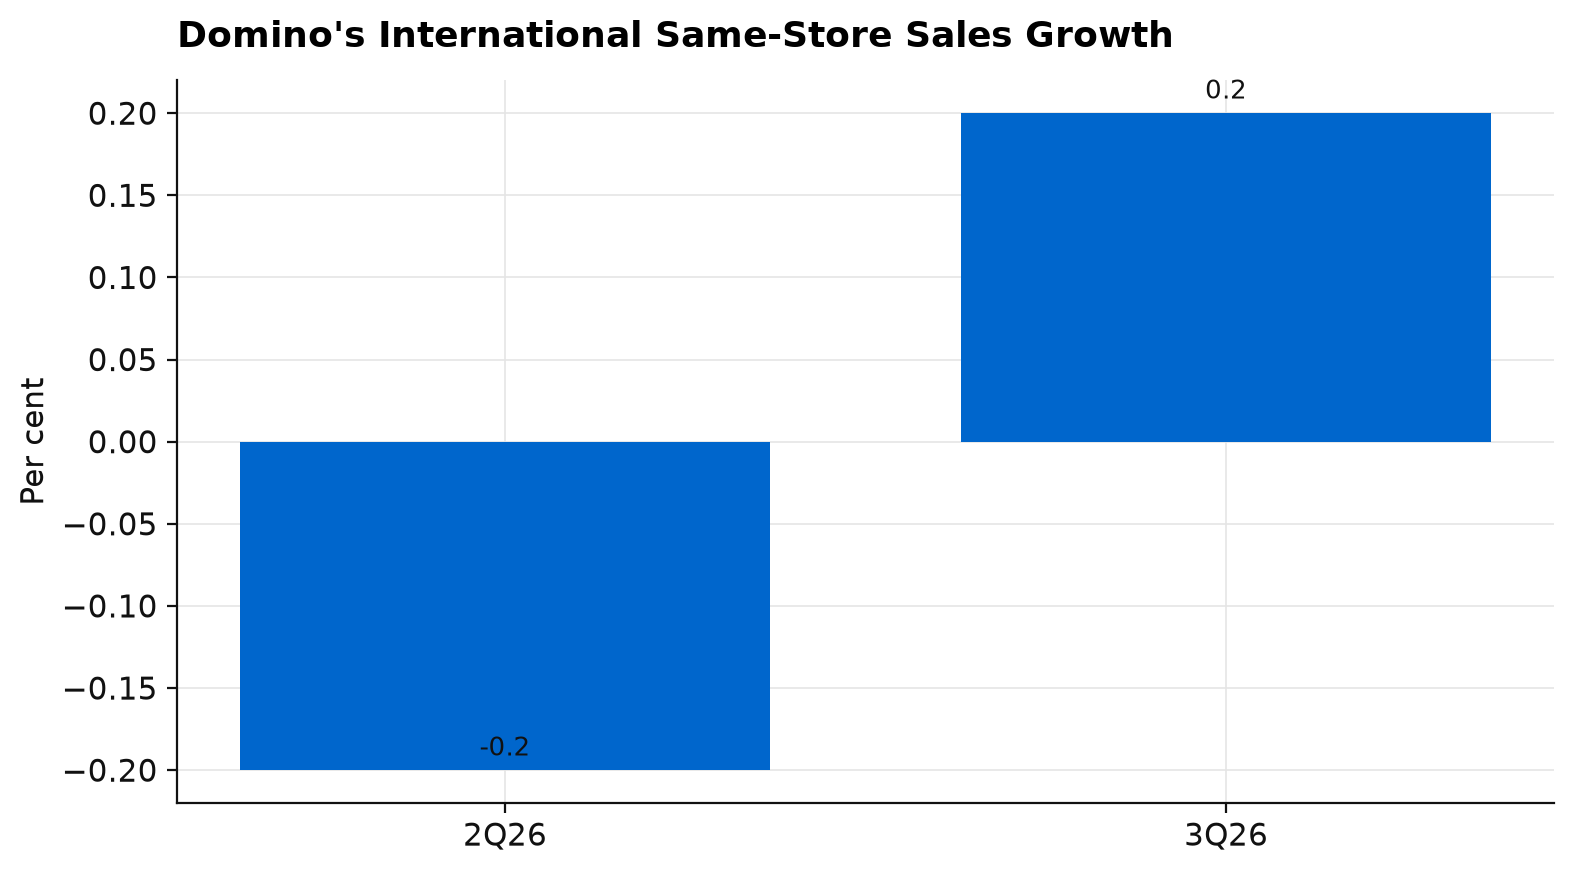
Across Domino’s International, same-store sales growth was 0.2 per cent in 3Q26, a slight improvement on the 0.2 per cent decline in 2Q26. The brand owner said Domino’s Pizza Enterprises held the figure back, and that it continues to work closely with the franchisee. Same-store sales have been variable and largely weak across the largest Domino’s International franchisees, and Domino’s Pizza Enterprises remains a drag within that group.
Management at Domino’s Pizza Enterprises is deliberately cutting lower-margin transactions, giving up orders that earn little for the store. Fewer but more profitable orders can leave franchisees better off, but the lower order count shows up directly in same-store sales, and the brand owner’s figures do not yet show the trade-off paying off.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARThe brand owner also lowered its 2026 guidance. It now expects US same-store sales growth to land at the low end of its low-single-digit range, and International to be flat, down from a prior expectation of low-single-digit growth. It said the change to the international outlook was driven by challenges at Domino’s Pizza Enterprises.
The brand owner’s general consumer comments were also incrementally negative, and management expects pressure on the consumer to linger through the balance of the year as the macro environment changes. Traffic, the number of customers placing orders, has tended to be positive, while ticket size, measured through items per order, has been the main drag on same-store sales. Management attributed this to the macro environment and saw no direct impact from GLP-1 medicines, the class of weight-loss and diabetes drugs that has been discussed as a possible threat to food demand.
Franchisee Profits and Store Openings
A franchise system grows when franchisees want to open more stores, and they want to open more stores when the ones they already run make good money. The brand owner said franchisee profitability is down on a year earlier and is limiting demand for new store openings, and it expects continued pressure until profitability growth returns, after which store growth can turn quickly.
Across Domino’s International, 2Q26 brought 200 gross store openings, largely in China and India, which together added 175, against 51 store closures, at least 10 of them in the Domino’s Pizza Enterprises network. Net international openings in 3Q26 were 49 stores. For Domino’s Pizza Enterprises itself, website store numbers imply a net 10 stores closed across its network in 1Q27, the first quarter of its 2027 financial year. That was driven by 10 store closures in Japan, with the Australia and New Zealand network steady.
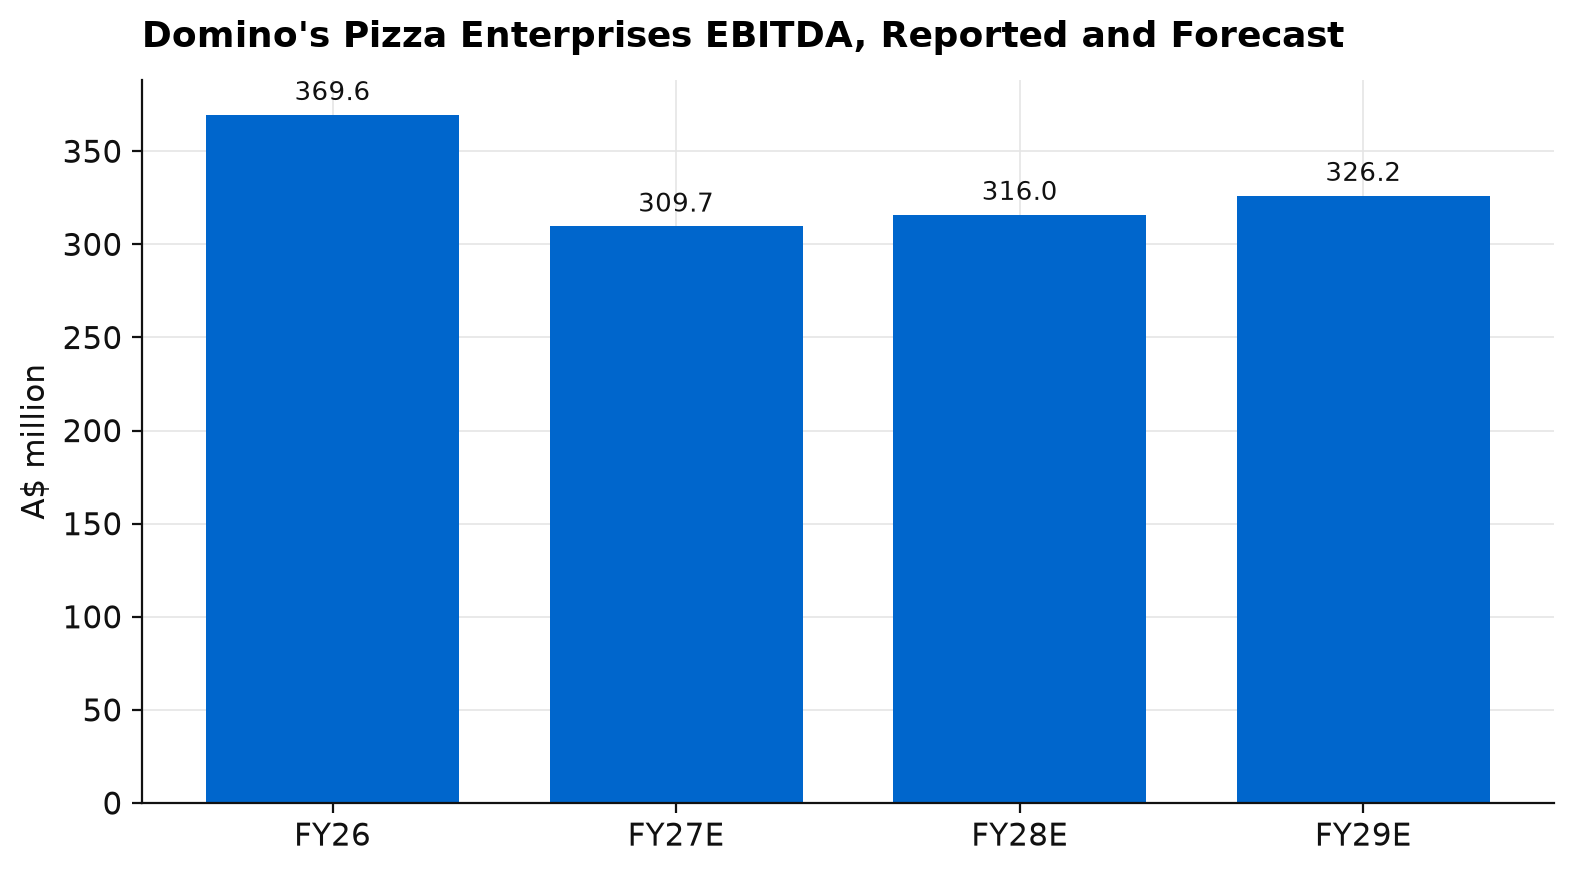
Revenue was A$2,046.1 million in the 2026 financial year, and institutional sell-side research forecasts it to fall to A$1,940.6 million in fiscal 2027, before recovering to A$1,970.8 million in fiscal 2028 and A$2,037.0 million in fiscal 2029. EBITDA, short for earnings before interest, tax, depreciation and amortisation, is a rough measure of operating profit before financing and accounting charges. It was A$369.6 million in fiscal 2026 and is forecast to drop to A$309.7 million in fiscal 2027, then edge up to A$316.0 million in fiscal 2028 and A$326.2 million in fiscal 2029. On those forecasts, EBITDA is still below its fiscal 2026 level in fiscal 2029.
Earnings per share are forecast to grow only slightly, from A$1.28 in fiscal 2026 to A$1.29 in fiscal 2027, A$1.30 in fiscal 2028 and A$1.34 in fiscal 2029. For the half years, the research has A$0.70 of earnings per share for the December 2026 half and A$0.59 for the June 2027 half, against A$0.65 for the June 2026 half.
Valuation and Why the Target Sits Below the Price
The 12 month price target of A$18.00 sits about 19.8 per cent below the A$22.45 share price. Institutional sell-side research thinks the share price already reflects a recovery that the numbers do not yet show, given weak sales, falling franchisee profits and flat forecast earnings.
International same-store sales growth was only 0.2 per cent in 3Q26, the brand owner has cut its international outlook to flat because of Domino’s Pizza Enterprises, and the company’s own strategy is shrinking its order count. Franchisee profitability is down on a year earlier and is limiting demand for new stores, and the network shrank by a net 10 stores in the first quarter of fiscal 2027. Forecast earnings per share move only from A$1.28 to A$1.34 between fiscal 2026 and fiscal 2029, and forecast EBITDA stays below the fiscal 2026 level of A$369.6 million throughout.
In the past twelve months the company paid A$0.575 a share in dividends, a trailing dividend yield of 2.6 per cent, unfranked, so Australian investors, including SMSF trustees, get no franking credits.
At A$22.45, the share price already allows for positives that are still unproven, such as the margin-first strategy and new leadership at both companies.
Key Risks
Better consumer trends, or falling input costs, meaning what it costs to make and deliver each order, would lift both sales and franchisee margins faster than the research assumes. Improved performance in the international markets Domino’s Pizza Enterprises runs would likely change the brand owner’s tone and ease the threat of a franchisor switch. If same-store sales momentum improves, or cost cuts deliver more than expected, earnings could beat forecasts that currently show little growth, and the brand owner has noted that store growth can turn quickly. Any of these would narrow the gap between the share price and the A$18.00 target.
Our View
Cutting lower-margin orders is a reasonable strategy, the brand owner says it has grown more positive on management, and both companies now have new chief executives. Against that, international guidance has been cut to flat because of Domino’s Pizza Enterprises, and franchisee profits are down.
The next tests are the brand owner’s quarterly International same-store sales figures and what it says about Domino’s Pizza Enterprises, the store counts on the company’s own network, and any sign that franchisee profitability has started to grow again.
If you would like to discuss Domino’s Pizza Enterprises, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR