

Hold
QBE Insurance is an ASX-listed general insurer that collects premiums, pays claims and invests the funds it holds, with International and North American businesses.
Institutional sell-side research rates it Buy because QBE's International business is still writing profitable insurance, with pricing declining only modestly over the half and a combined operating ratio of 91.6 per cent. Returns on equity are estimated at 17.4 per cent in FY26 and 15.4 per cent or better through FY28, while earnings per share are expected to grow again from FY27. The main risk is the pricing cycle softening faster than claims costs rise.
- Sell-side rating
- Buy
- Sell-side target
- A$27.00
- Upside to target
- +2.8%
- Initial price
- A$23.3920 Sep 2026
- Last close
- A$26.2719 Nov 2026
Initial Buy based on A$23.39. Now Hold since 30 Oct 2026: the price reached within 5% of the A$27.00 target.
The first-half 2026 results from Lloyd’s of London give QBE Insurance investors an early read on the company’s International business and on pricing across the wider insurance market. The Lloyd’s market grew premium by a strong 6.9 per cent and earned a return on capital of 21.6 per cent, even as prices fell 6.7 per cent and the cost of everyday claims rose. Institutional sell-side research has QBE Insurance rated Buy with a 12 month price target of A$27.00, about 15.4 per cent above the share price of A$23.39 when this research was published. The research notes that QBE’s own International pricing declined only modestly over the half, and that business is still writing profitable insurance. On the income side, QBE has paid A$1.11 a share in dividends over the past year, a trailing yield of 4.7 per cent, partly franked at 30 per cent.
Research published 20 September 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About QBE Insurance
QBE Insurance Group is a general insurer listed on the Australian Securities Exchange under the code QBE. Its operations include an International business and a North American business, and its earnings are exposed to commercial insurance pricing. QBE’s financial year ends in December, and its dividends are partly franked. Like any general insurer, QBE collects premiums from customers up front, pays claims as they arise, and invests the money it holds in the meantime. Its profit comes from underwriting, the gap between the premiums it collects and the cost of claims and expenses, and from investment income on the funds it holds, which is why the research lists lower interest rates and yields as a risk.
Premium Growth Is Coming From Volume
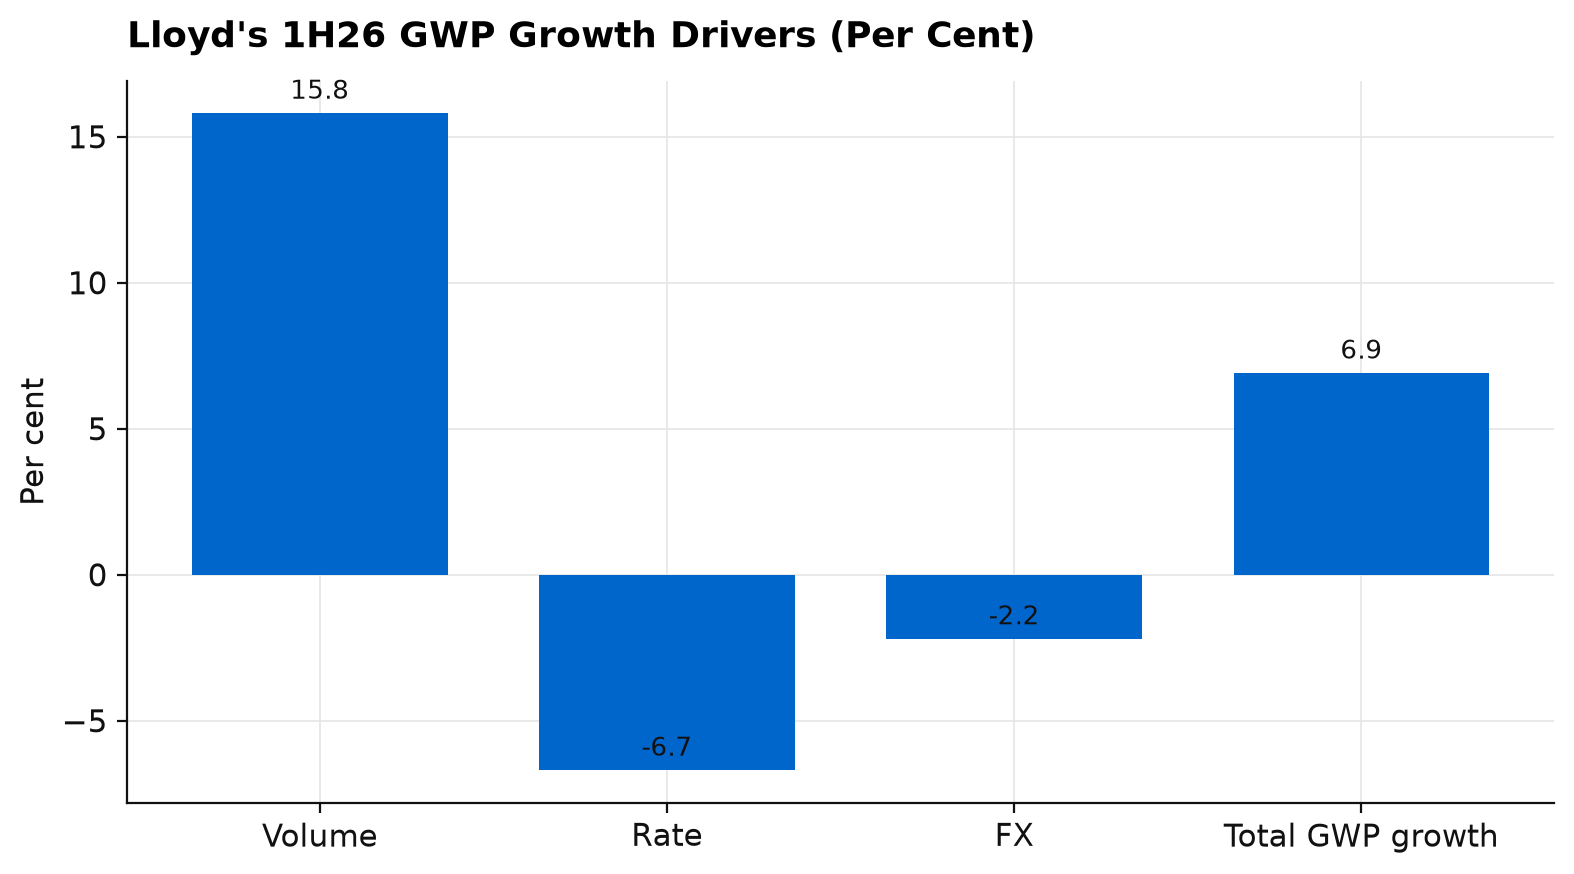
Gross written premium, or GWP, is the total value of insurance policies an insurer sells in a period, before any of it is passed on to reinsurers, the companies insurers buy their own cover from. Lloyd’s wrote £34.7 billion of GWP in the first half of 2026 (1H26), up 6.9 per cent on the previous corresponding period, meaning the same half a year earlier.
Volume rose 15.8 per cent across new and existing syndicates, the underwriting groups that do business inside the Lloyd’s market, with new syndicates joining helping to lift it. Most of the growth came from reinsurance, casualty, and marine and aviation. Lloyd’s said the growth was driven by structured products and portfolio solutions, which are larger, packaged arrangements that bundle many policies together.
Two things pulled the other way. Prices fell 6.7 per cent on a risk-adjusted basis, meaning after allowing for any change in the cover itself, with the pressure heaviest in property and reinsurance. Currency movements took off another 2.2 per cent, and together the three drivers produce the 6.9 per cent headline.
Lloyd’s described its growth as rate adequate, meaning the business it is adding is still priced to earn a profit, and said rates remain adequate relative to a 95 per cent combined operating ratio, a measure explained in the next section. It also said rate adequacy is declining, and the research describes the 6.7 per cent fall as gradually eroding it.
The market’s response has been a greater focus on active cycle management, which includes looking for new areas of growth, with the aim of keeping returns sustainable. Lloyd’s also flagged market facilities as an opportunity, while saying it is monitoring expense creep, meaning costs that drift higher over time.
For QBE, the research notes that its own International rate declined modestly over 1H26, in line with the direction of the wider market. Our read of the Lloyd’s figures is that pricing is softening slowly and that insurers with discipline are still finding business to write.
Underlying Claims Costs Are Edging Higher
The main measure of insurance profitability is the combined operating ratio, or COR, which adds the cost of claims to the cost of running the business and writing policies and shows the total as a share of premium. When claims and costs add up to less than the premium collected, the insurer has made an underwriting profit before counting any investment income, so a lower COR is better.
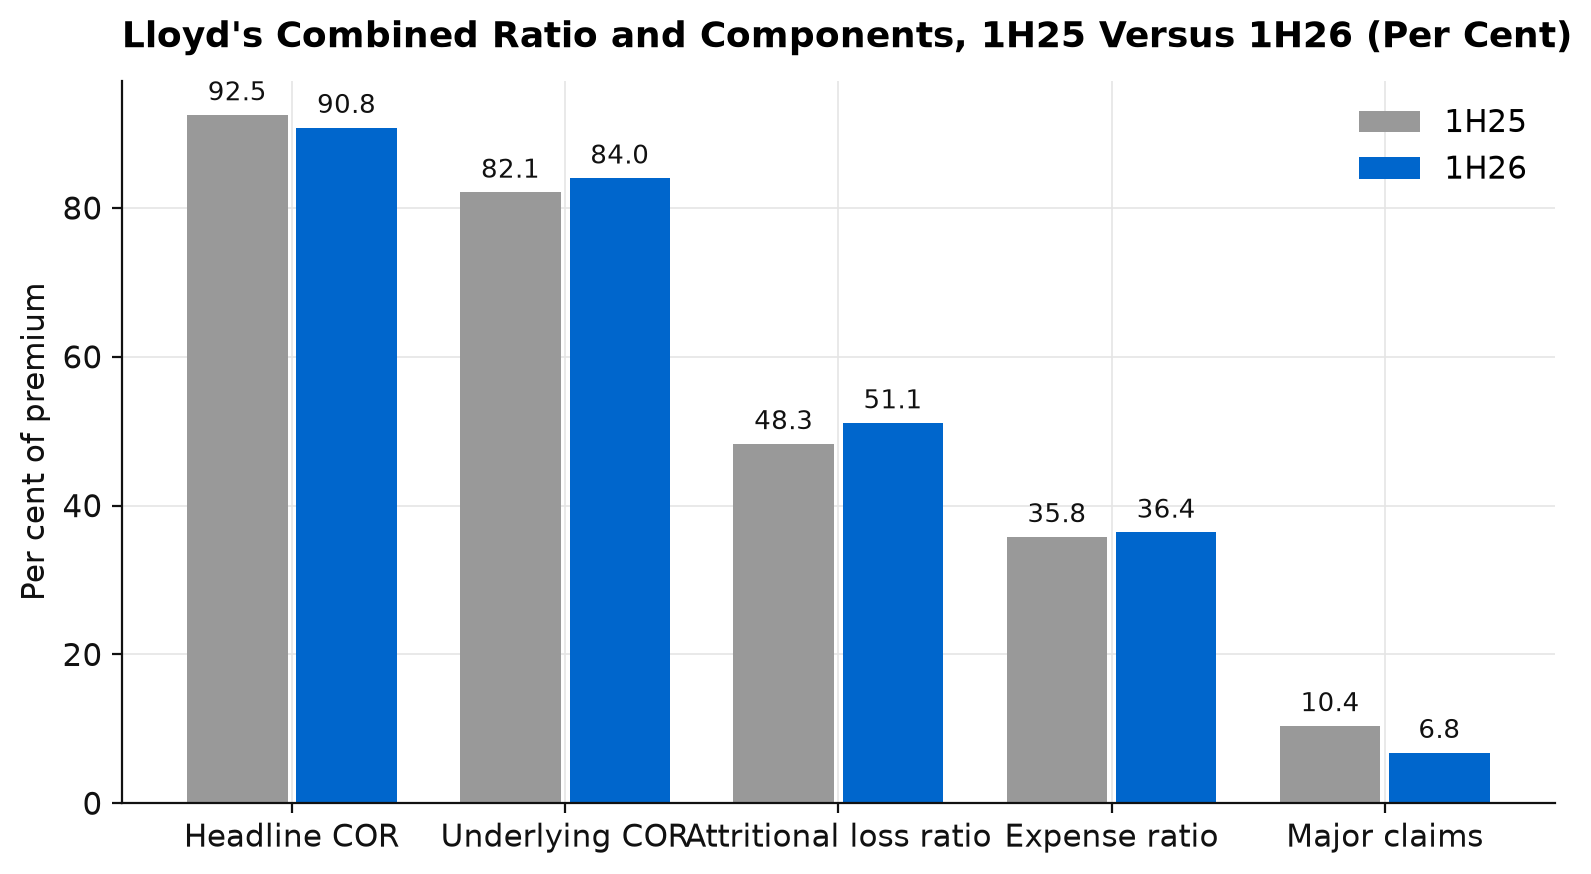
Lloyd’s reported a headline COR of 90.8 per cent for 1H26. That was better than 92.5 per cent in the previous corresponding period, mostly thanks to a quieter half for large events, but slightly elevated relative to recent halves. Catastrophe losses and major claims added 6.8 percentage points to the ratio, against 10.4 percentage points a year earlier. The result also included £1.4 billion of costs relating to the Middle East war.
The underlying picture is weaker. Take out major claims and the underlying COR was 84 per cent, against 82.1 per cent in the previous corresponding period, a deterioration of about 2 percentage points with three moving parts behind it.
The first is the attritional loss ratio, which rose 2.8 percentage points to 51.1 per cent from 48.3 per cent, a move the research calls a negative read. Attritional losses are the steady flow of smaller, everyday claims, and because they are less random than storms and other large events, they are a better guide to whether prices are keeping up with the true cost of risk. Lloyd’s attritional loss ratio has been gradually increasing more recently, which fits with falling rates, since this ratio goes up when prices fall while claims costs do not.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARThe second is reserve releases, which helped. Insurers set money aside as reserves for claims that have happened but are not yet settled. When those claims end up costing less than expected, the surplus is released back into profit. Releases were about 3.5 per cent of premium, better than 2 per cent a year earlier, driven by better catastrophe and attritional claims experience. Lloyd’s flagged that property releases were partially offset by strengthening in aviation and casualty, which means reserves in those classes had to be topped up. There was also some reserve strengthening relating to the Baltimore Bridge loss.
The third is the expense ratio, the cost of running the business and acquiring policies as a share of premium, which rose 0.6 percentage points to 36.4 per cent from 35.8 per cent. Lloyd’s put this down to increased profit commissions and higher acquisition and commission costs driven by business mix. Profit commissions are payments to partners who bring in business, linked to how profitable that business turns out to be.
QBE’s International business reported a COR of 91.6 per cent over 1H26, slightly higher than the Lloyd’s headline of 90.8 per cent and still a clear underwriting profit.
Returns Stay High as Earnings Level Out
Return on equity, or ROE, measures how much profit a company earns for each dollar of shareholders’ money tied up in the business. For an insurer it is the best single test of whether underwriting and investing together are producing a good result on the capital it must hold. Lloyd’s said return on capital was strong at 21.6 per cent over 1H26, so the market as a whole was still earning high returns in 1H26 even as prices softened.
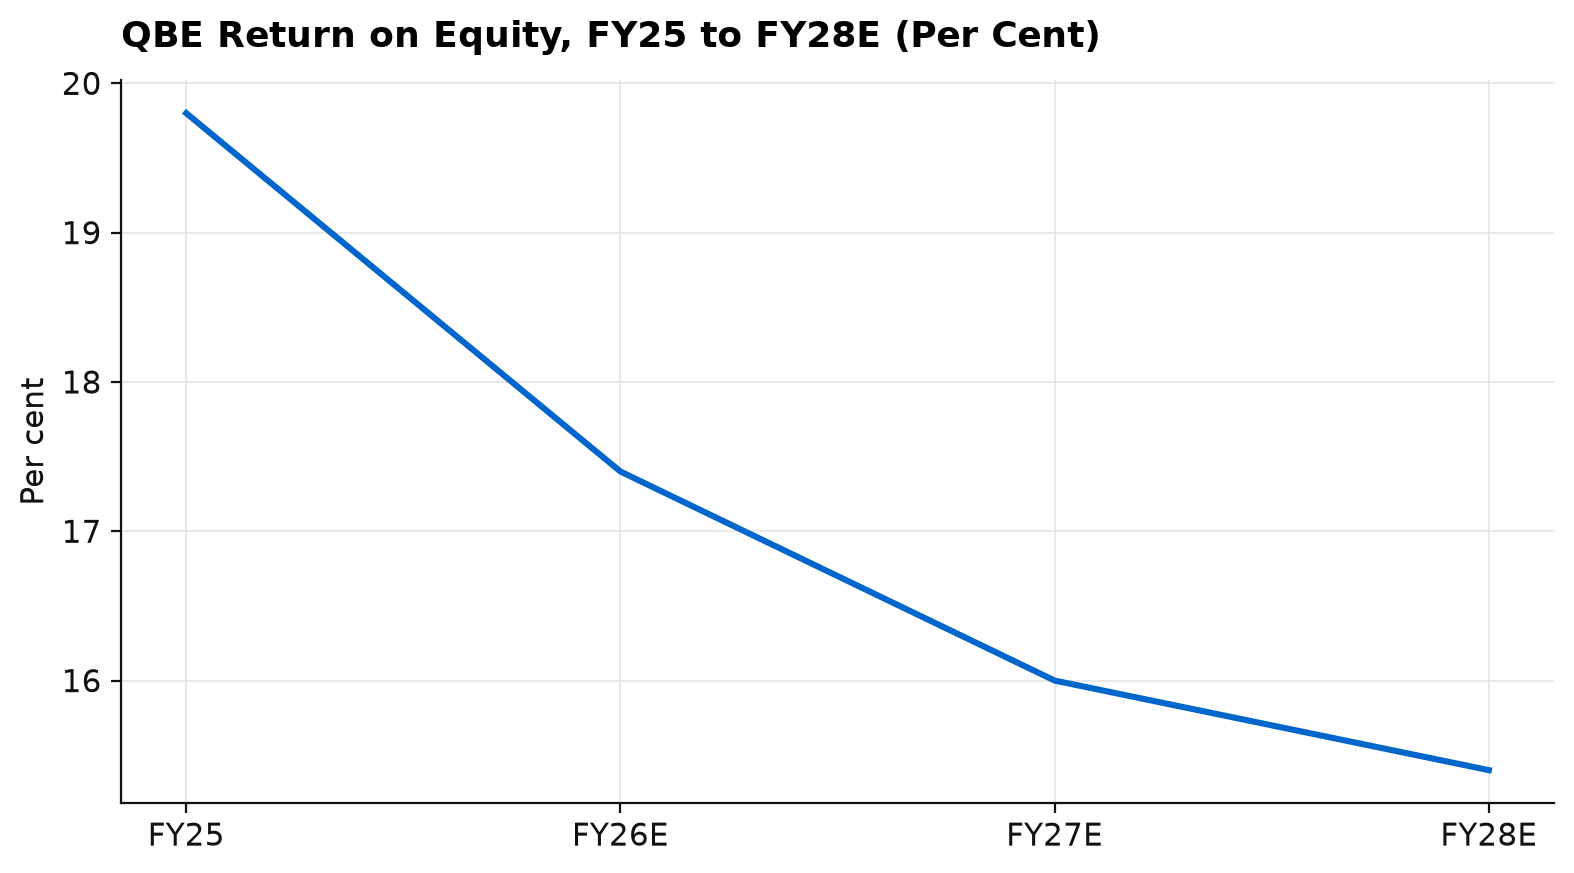
QBE’s returns are also high, with ROE of 19.8 per cent for the year to December 2025. The research estimates 17.4 per cent in FY26, 16.0 per cent in FY27 and 15.4 per cent in FY28, a gradual decline that fits a softer pricing cycle while staying in the mid-teens through FY28, which we regard as a good return for a large insurer.
In US dollars, the currency the research uses for QBE’s earnings, net income was US$2,157.0 million in FY25. The research expects US$2,098.8 million in FY26, then US$2,155.9 million in FY27 and US$2,247.4 million in FY28. Earnings per share, or EPS, follow the same path, going from US$1.40 in FY25 to US$1.39 in FY26, a 0.8 per cent dip, then growing 2.9 per cent to US$1.43 in FY27 and 4.2 per cent to US$1.49 in FY28. EPS growth in FY25 was 22.6 per cent, so FY26 is a pause after a very strong year.
On a half-year basis, the research has EPS of US$0.75 in the second half of 2025, US$0.68 in the first half of 2026, US$0.71 in the second half of 2026 and US$0.70 in the first half of 2027, a broadly flat profile.
Dividends follow the same shape, with the research showing US$0.73 a share for FY25, then US$0.72 in FY26, US$0.74 in FY27 and US$0.77 in FY28. Franking is forecast at 30 per cent from FY26, up from 28.6 per cent in FY25. The Lloyd’s focus on sustainable returns suggests the wider market is putting returns ahead of growth through the softer patch, and QBE’s mid-teens ROE forecasts fit that approach.
Valuation and What the Target Implies
Institutional sell-side research has a 12 month price target of A$27.00 on QBE. That is about 15.4 per cent above the A$23.39 share price when this research was published. QBE has also paid A$1.11 a share in dividends over the past twelve months, a trailing yield of 4.7 per cent, partly franked at 30 per cent. Partly franked at 30 per cent means 30 per cent of the dividend carries franking credits for Australian company tax already paid, and the rest does not. For an SMSF trustee in a low-tax fund, those credits can add to the value of the income.
On growth, the Lloyd’s results show a market still adding business at a good pace, with GWP up 6.9 per cent even as prices ease, and Lloyd’s says that new business is still priced adequately.
On underwriting, QBE’s International COR of 91.6 per cent means claims and costs took up less than the premium it collected, and the research says International rates declined only modestly over 1H26.
On returns, QBE’s ROE is estimated at 17.4 per cent in FY26 and stays at 15.4 per cent or better through FY28. EPS is expected to grow again from FY27, and the dividend is forecast to rise from US$0.72 in FY26 to US$0.77 in FY28.
The soft spot is a slight dip in FY26 earnings before growth resumes. Set against that are a target 15.4 per cent above the share price and a trailing yield of 4.7 per cent, partly franked at 30 per cent. At A$23.39, the research’s Buy case over the next 12 months rests on QBE’s returns holding up as prices soften.
Key Risks
The biggest risk is the pricing cycle, because if momentum in the commercial premium rate cycle weakens materially below loss cost inflation, meaning the pace at which claims costs themselves are rising, margins would shrink. Lower-than-expected interest rates and yields would also cut the income QBE earns on the money it holds before claims are paid. On the competitive side, the Lloyd’s results show pricing pressure in property and reinsurance. Greater-than-expected reinsurance costs at renewal would raise the price QBE pays for its own protection. Claims are another risk, since persistent claims inflation and catastrophes could push loss ratios higher, and the rising attritional trend at Lloyd’s shows how this can build. Continued poor profitability in the North American business would also weigh on group results.
Our View
We think the Lloyd’s numbers are more reassuring than the headline rate decline suggests. Prices are coming down, but gradually, and Lloyd’s still describes them as adequate. Premium is growing because insurers are finding new business to write, with volume up 15.8 per cent. The attritional loss ratio is the figure we would watch, because if everyday claims keep rising while prices fall, margins compress, and that is the trend most likely to show up in QBE’s International results over the next few halves.
For now, QBE’s International COR of 91.6 per cent leaves a clear underwriting profit, and the group’s ROE is estimated to stay at 15.4 per cent or better through FY28. In our view, an insurer that stays profitable and keeps paying a partly franked dividend through a gradual softening is in good shape for this stage of the cycle. Second-half International margins will be the next test of the research’s A$27.00 target.
If you would like to discuss QBE Insurance, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR