Buy
American Tower owns communications towers and data centers and leases the space to wireless carriers and cloud customers.
Institutional sell-side research rates it Buy because American Tower has a diversified revenue base, with Latin America, Africa and Asia Pacific and data centers all beating expectations in a quarter when US leasing stalled. CoreSite data center growth guidance has been raised twice this year to about 16 per cent. Buybacks of US$300 million in the quarter and a new US$2.0 billion repurchase plan lift per share results now.
- Sell-side rating
- Buy
- Sell-side target
- US$215.00
- Upside to target
- +14.8%
- Initial price
- US$187.294 Nov 2026
- Last close
- US$187.293 Nov 2026
In American Tower‘s third quarter of 2026, the core US tower leasing business barely grew, and management cut its services revenue outlook because customer projects slipped. The same result delivered an earnings beat, a sharp step up in share buybacks and another lift in growth guidance for the CoreSite data center business. Institutional sell-side research has American Tower rated Buy with a 12 month price target of US$215.00, about 14.8 per cent above the share price of US$187.29 when this research was published. The research backs its Buy with a diversified revenue base, data center exposure that adds value and flexibility in how the company uses its cash.
Research published 4 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
- 1. About American Tower
- 2. An Earnings Beat With Buybacks Doing More of the Work
- 3. US Leasing Paused but the Full Year Plan Still Stands
- 4. CoreSite Data Center Growth Guidance Rises Again
- 5. Satellite Operators Could Become a New Class of Tenant
- 6. Selling Canada and the Road to a 2027 Inflection
- 7. Valuation and the Buy Case
- 8. Key Risks
- 9. Our View
- 10. Financial Summary
About American Tower
American Tower owns communications towers and leases space on them to wireless carriers, which rent room on each site for their antennas and equipment. Its property business is reported across four tower regions, US/Canada, Latin America, Africa and Asia Pacific, and Europe, plus a fifth segment, data centers, run through CoreSite. In the third quarter of 2026, property revenue was US$2.73 billion out of total revenues of US$2.79 billion, with US/Canada the largest single region at US$1.28 billion. The company directs about 85 per cent of its discretionary capital toward developed markets, and it has agreed to sell its Canadian tower business. American Tower is listed on the New York Stock Exchange under the ticker AMT and sits within the real estate investment trust (REIT) sector, a group of listed property owners whose valuations tend to be sensitive to interest rates.
An Earnings Beat With Buybacks Doing More of the Work
The headline numbers came in better than the market expected. Adjusted EBITDA, which is earnings before interest, tax, depreciation and amortisation and a rough guide to the operating cash profit a business generates, came in at US$1.83 billion for the third quarter of 2026, just ahead of consensus at US$1.82 billion. Total revenues of US$2.79 billion beat consensus of US$2.76 billion, driven by property revenue of US$2.73 billion against expectations of US$2.70 billion. Property revenue is the rent American Tower collects from tenants on its towers and in its data centers, and it is the biggest line in the results.
Latin America property revenue of US$460 million was above consensus of US$440 million. Africa and Asia Pacific came in at US$428 million against US$409 million, and data center property revenue reached US$313 million against US$305 million. US/Canada property revenue of US$1.28 billion was in line. Europe property revenue of US$258 million was just below consensus of US$261 million.
On adjusted funds from operations per share, known as AFFO per share, the company reported US$2.87. AFFO is the cash earnings measure that tower and property companies use, roughly the cash left over after recurring costs and maintenance spending. The US$2.87 beat consensus of US$2.79, although it was slightly below the institutional sell-side research estimate of US$2.89.
American Tower bought back US$300 million of its own shares in the third quarter, well above the US$100 million institutional sell-side research had expected, and a newly approved US$2.0 billion repurchase plan now sits behind that. Fewer shares on issue means each remaining share gets a bigger slice of the cash flow, which is why the midpoint of AFFO per share guidance ticked up while the midpoint of total AFFO guidance was unchanged.
Full year guidance moved as follows. Property revenue guidance is now US$10.785 to US$10.865 billion, up from US$10.695 to US$10.845 billion. Domestic property revenue guidance is US$5.085 to US$5.095 billion, a narrower range than the prior US$5.060 to US$5.120 billion. International property revenue guidance rose to US$4.482 to US$4.542 billion from US$4.435 to US$4.505 billion. Adjusted EBITDA guidance is US$7.248 to US$7.303 billion against US$7.240 to US$7.310 billion before, and AFFO guidance is US$5.148 to US$5.203 billion against US$5.135 to US$5.215 billion, with the midpoint of both unchanged.
US Leasing Paused but the Full Year Plan Still Stands
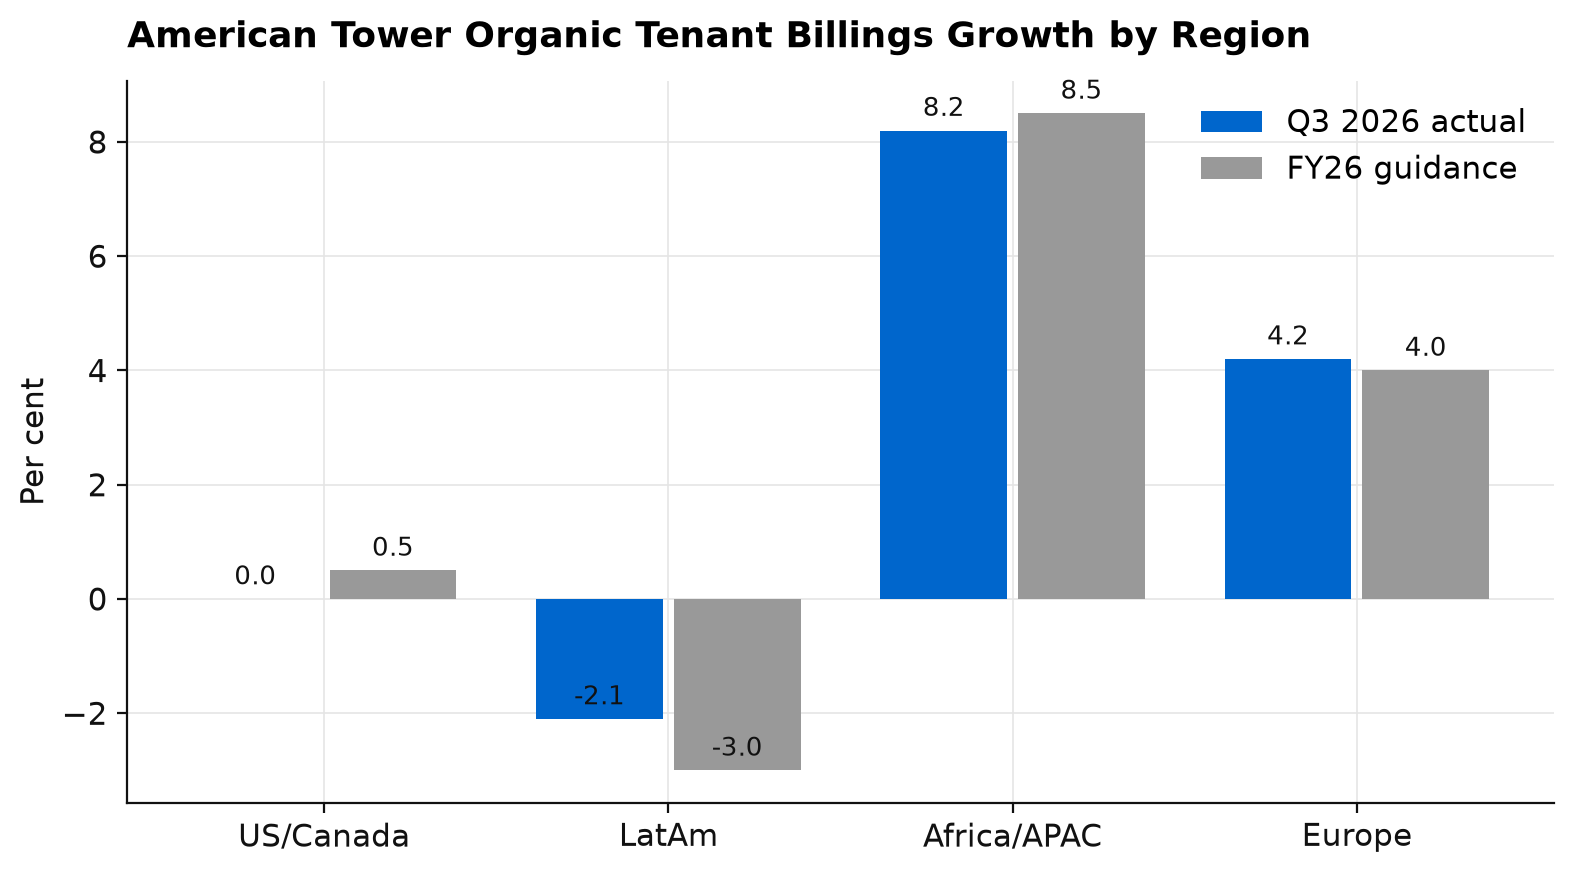
The US was where the result disappointed. Organic tenant billings growth measures how much more rent the company is collecting from its existing sites once acquisitions and currency effects are stripped out. For US/Canada it came in at 0.0 per cent. Consensus had expected 0.5 per cent and institutional sell-side research had expected 0.4 per cent. The miss was in colocation, which is when an additional carrier adds its equipment to a tower that already has tenants. Because the tower is already built, an extra tenant adds rent without the cost of a new site.
Management did not change its full year view. American Tower reiterated its outlook of about 0.5 per cent US organic tenant billings growth for 2026, a figure that already absorbs a headwind of about 400 basis points from DISH churn. Churn is rent lost when a tenant leaves, and DISH’s exit is the main drag on US growth this year. A basis point is one hundredth of a percentage point, so 400 basis points is four percentage points.
The company attributed the third quarter step down in new business to timing. It called 2026 a front-end-loaded year and said not all carriers were currently active. New business in the fourth quarter is expected to stay around the third quarter level of US$25 million, against consensus of US$33 million for the fourth quarter. American Tower still expects new business to contribute about 250 basis points to 2026 US organic tenant billings growth, consistent with 2025 once DISH is excluded. The research notes that a fourth quarter at that level puts pressure on reaching it.
Services revenue, which is project fee income as distinct from the recurring rent the towers collect, was the other negative. The company cut its 2026 services revenue outlook to about US$220 million from US$245 million because certain customer projects were delayed out of the third quarter, and they could slip beyond the fourth quarter as well. Management stressed that services and organic new business are decoupled, and described the delay as a matter of timing, with expectations unchanged. It still expects both the services work and the associated rental revenue once the customer builds.
In dollar terms, the roughly US$15 million services reduction was offset by about US$10 million of data center outperformance and about US$5 million of other benefits, leaving the midpoint of Adjusted EBITDA guidance unchanged at about US$7.28 billion.
Looking further out, American Tower expects US organic growth to normalise once the DISH churn headwind laps, meaning it drops out of the year-on-year comparison, and as carrier activity increases. It named densification, which means adding more sites so networks can carry more traffic in busy areas, along with new spectrum, 6G and AI as sources of potential upside beyond 2026.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARCoreSite Data Center Growth Guidance Rises Again
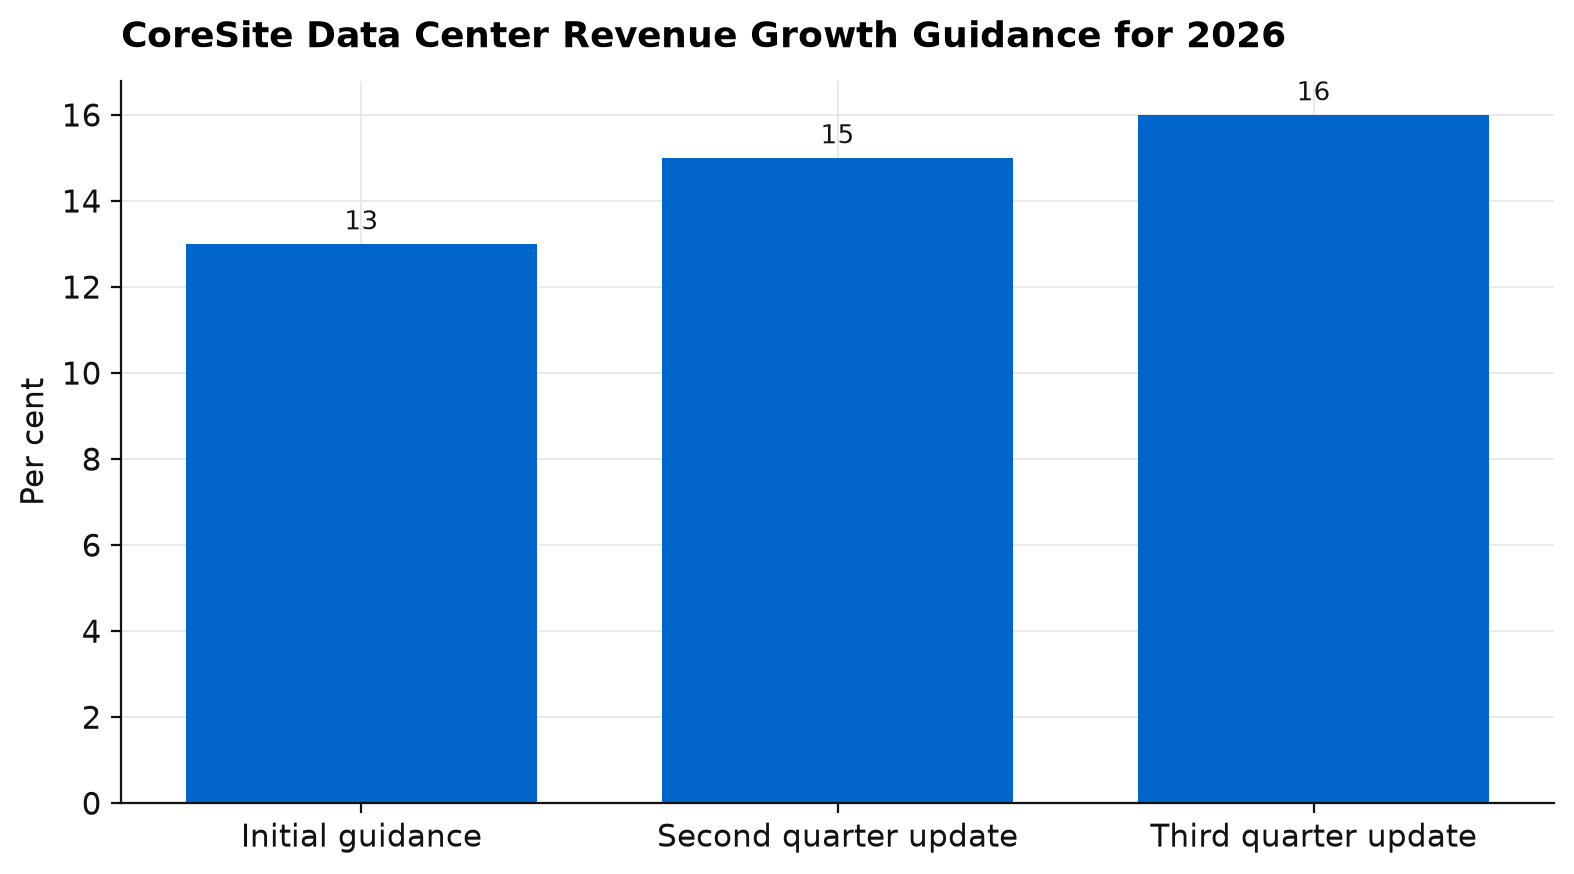
American Tower raised its 2026 data center revenue growth outlook to about 16 per cent, from 15 per cent last quarter and 13 per cent initially, the second raise this year. Demand has been broad-based across cloud, network, enterprise and AI customers, and the company said it accelerated into the fourth quarter. Customer demand, pricing and interconnection activity all remained strong.
American Tower continues to underwrite returns in the mid-teens or better on new development once a facility is stabilised, meaning built and leased up. Renewal pricing has been stronger still, with contracts that came up for renewal in the second and third quarters of 2026 resetting to a double-digit cash mark-to-market, which is the uplift in rent when an expiring contract is re-signed at current market rates. A more typical outcome is 3 to 4 per cent. Interconnection, the fees customers pay to link directly to each other inside a facility, is another part of the revenue that kept growing.
The company expects double-digit CoreSite revenue growth for the foreseeable future, sees the potential to nearly triple current capacity, and is exploring new organic market entries, meaning entering new cities by building its own facilities there. Permitting could constrain the pace of development.
AI customers are part of that data center demand. The research describes this exposure as value-accretive, which in plain terms means each dollar invested in it should add more to per share value than it costs. It also lifts the group’s growth rate over time, because a segment growing at double digits, inside a company whose largest region grew at 0.0 per cent this quarter, makes up a larger share of group revenue each year.
Satellite Operators Could Become a New Class of Tenant
Management said it was encouraged by Starlink’s public statements about a planned terrestrial build and its acquisition of 800MHz spectrum from Grain. Spectrum is the set of radio frequencies a network operator is licensed to use. A terrestrial network is built on the ground, so it needs antennas on sites, and sites are what American Tower leases.
The company said it is in discussions with all parties with wireless ambitions, and the research describes a potential terrestrial build from Starlink and other satellite providers as incremental upside, with no figure attached.
There is a related development from DISH. Following the DISH bankruptcy abandonment order, American Tower confirmed that it owns the DISH equipment remaining on its towers and is free to make that equipment available to interested parties. A new entrant looking to stand up a network could find equipment already sitting on sites. That could turn part of the DISH problem, which is costing the company about 400 basis points of US growth this year, into a way to attract a replacement tenant.
So while it waits for the large carriers to lift spending, American Tower has sites, equipment already on them and open talks with new wireless players.
Selling Canada and the Road to a 2027 Inflection
American Tower has agreed to sell its Canadian tower business for about US$202 million. The portfolio contributed about US$13 million of revenue, about US$8 million of EBITDA and about US$8 million of AFFO to 2026 guidance, so it is a small piece of the group. Management expects the sale to be immediately accretive to AFFO per share, meaning it lifts that figure straight away, and to improve the longer-term AFFO per share growth profile as the proceeds are recycled into share repurchases, debt reduction and other higher-growth investments. The company continues to allocate about 85 per cent of its discretionary capital toward developed markets.
Revised 2026 AFFO per share guidance of US$11.04 to US$11.16, up from US$11.00 to US$11.17, implies more than 3 per cent growth, with the increase primarily reflecting share repurchases. On an FX-neutral basis, meaning with currency movements stripped out, management framed 2026 AFFO per share growth as approximately flat. That flat result already absorbs about 400 basis points from DISH churn, about 100 basis points from refinancing and about 100 basis points from the services step down.
Management’s focus is 2027. American Tower reiterated that it expects AFFO per share growth to inflect in 2027, meaning the growth rate turns up. Its case rests on developed-market revenue growth in the mid-single digits, higher growth in emerging markets and double-digit CoreSite growth. Once DISH drops out of the comparison, one of the largest drags on this year’s numbers disappears.
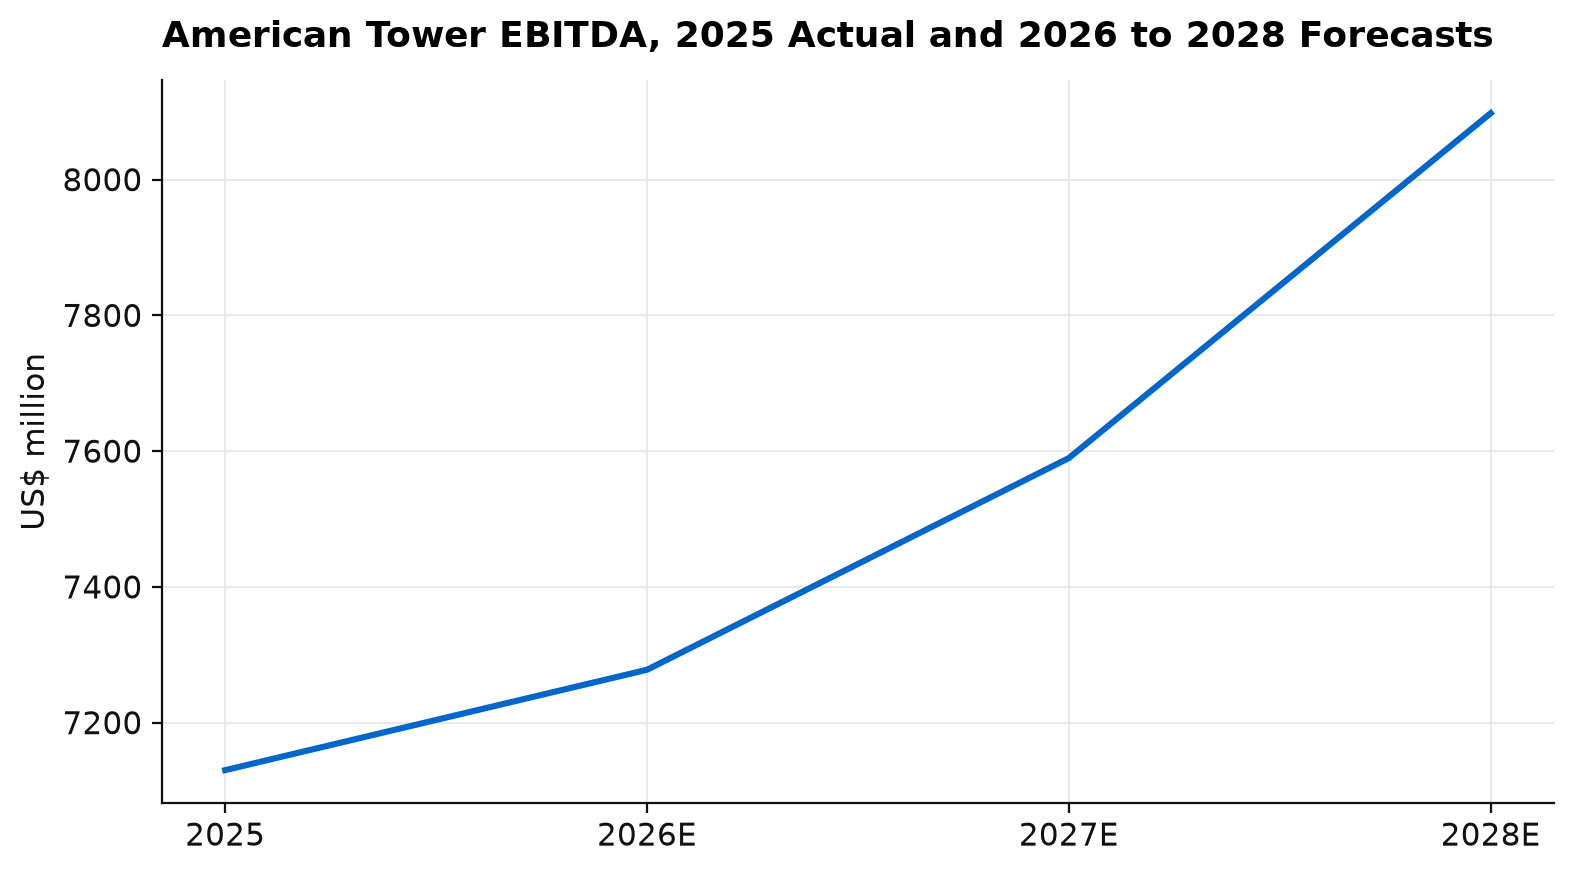
Institutional sell-side research forecasts revenue of US$11,032.7 million for 2026, US$11,374.3 million for 2027 and US$12,061.2 million for 2028, up from US$10,644.6 million in 2025. The 2027 revenue estimate was trimmed from US$11,420.7 million. EBITDA is forecast to rise from US$7,130.0 million in 2025 to US$7,277.9 million in 2026, US$7,589.8 million in 2027 and US$8,097.9 million in 2028. Earnings per share are forecast at US$6.93 in 2026, US$7.60 in 2027 and US$8.68 in 2028, against US$5.40 in 2025. The research left its 2026, 2027 and 2028 AFFO estimates largely unchanged after the result.
Valuation and the Buy Case
Institutional sell-side research lifted its 12 month price target to US$215.00 from US$210, reflecting a lower share count and rolling its valuation forward in time. That target sits about 14.8 per cent above the share price of US$187.29 when this research was published. The upside is modest, and the research’s case rests on its revenue base, data centers and capital allocation.
On the revenue base, Latin America, Africa and Asia Pacific and data centers all beat expectations in a quarter when US leasing stalled. On data centers, CoreSite growth guidance has been raised twice this year to about 16 per cent and capacity could nearly triple. On capital allocation, there were US$300 million of buybacks in the quarter, a US$2.0 billion repurchase plan behind them, and the Canadian sale freeing up capital for buybacks, debt reduction and higher-growth investment.
At US$187.29, investors are looking at a business whose 2026 numbers are held down by the loss of DISH, a single large tenant. The weak US leasing quarter is already known and sits inside reiterated guidance, and data centers and buybacks are lifting per share results now. Management expects AFFO per share growth to inflect in 2027, and that 2027 turn leans on US leasing recovering once DISH laps.
Key Risks
Elevated interest rates could drive lower valuations for highly levered equities across the REIT sector, which would weigh on American Tower regardless of how the business performs. In the core tower leasing business, American Tower could face ongoing pressure if wireless carriers continue to constrain their spending plans. Global macroeconomic pressure could drive further carrier consolidation across its international markets, adding pressure on revenue and AFFO growth. On execution, fourth quarter US new business is expected at around US$25 million against consensus of US$33 million, the customer projects behind the services cut could slip beyond the fourth quarter, and permitting could slow CoreSite’s expansion. Finally, swings in emerging market currencies can move reported revenue and AFFO, as the gap between reported and FX-neutral AFFO per share growth this year shows.
Our View
We like how American Tower is allocating capital. Selling a small Canadian business for about US$202 million and putting the proceeds into buybacks, debt reduction and higher-growth investment is a disciplined choice. We also find it more useful to look at American Tower as two businesses: a tower business going through a slow year while DISH laps and carriers hold back, and a data center business going through a strong one. We are watching fourth quarter US new business most closely, because holding at US$25 million would support management’s timing explanation, while a further slip would make the 2027 inflection harder to reach.
If you would like to discuss American Tower, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR