Buy
Teledyne is a US industrial technology company that makes infrared imaging detectors, test and measurement instruments, defense electronics and engineered products across four segments.
Institutional sell-side research rates it Buy because third quarter 2026 earnings per share, revenue and margins all beat consensus, and management raised full-year earnings guidance to US$25.40 to US$25.50. Digital Imaging revenue grew 15 per cent and its margin rose 370 basis points. The shares trade below their long-run historical average valuation, and earnings forecasts for each year were lifted.
- Sell-side rating
- Buy
- Sell-side target
- US$915.00
- Upside to target
- +35.1%
- Initial price
- US$665.5630 Oct 2026
- Last close
- US$677.4629 Oct 2026
Teledyne‘s revenue, margins and earnings per share for the third quarter of 2026 all came in ahead of consensus, and management raised full-year guidance on every one of those measures. Adjusted earnings per share of US$6.72 landed 9 per cent above the US$6.17 the market expected, revenue of US$1.68bn beat consensus of US$1.65bn, and the company lifted its 2026 earnings guidance to US$25.40 to US$25.50. Institutional sell-side research has Teledyne rated Buy with a 12 month price target of US$915.00, about 37.5 per cent above the share price of US$665.56 when this research was published. Digital Imaging led the growth, margins and free cash flow both rose, and the balance sheet can fund more acquisitions.
Research published 30 October 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Teledyne
Teledyne Technologies is a US industrial technology company listed on the New York Stock Exchange under the ticker TDY. Institutional sell-side research covers it within its Americas aerospace and defense universe. The company reports four segments. Digital Imaging, the largest by revenue, sells infrared imaging detectors, components, surveillance systems, imaging systems and X-ray products. Instrumentation covers environmental instrumentation alongside electronic test and measurement instrumentation. Aerospace and Defense Electronics includes defense electronics, and Engineered Systems sells engineered products whose margins move with program mix. In the third quarter of 2026 the group generated US$1.68bn of revenue, with Digital Imaging contributing US$903mn of that. Teledyne grows partly through acquisitions, and institutional sell-side research describes its mergers and acquisitions (M&A) platform as successful.
A Beat on Every Line and Higher Guidance
Earnings per share, or EPS, is the company’s profit divided by the number of shares on issue, and most investors use it to judge a result. Teledyne reported adjusted EPS of US$6.72 for the third quarter of 2026 against a consensus of US$6.17, a beat of 9 per cent. Consensus is the average forecast of the analysts who cover the stock. Revenue of US$1.68bn was also ahead of consensus at US$1.65bn, and 3 per cent above the institutional sell-side estimate, with Digital Imaging and Engineered Systems the segments that came in ahead.
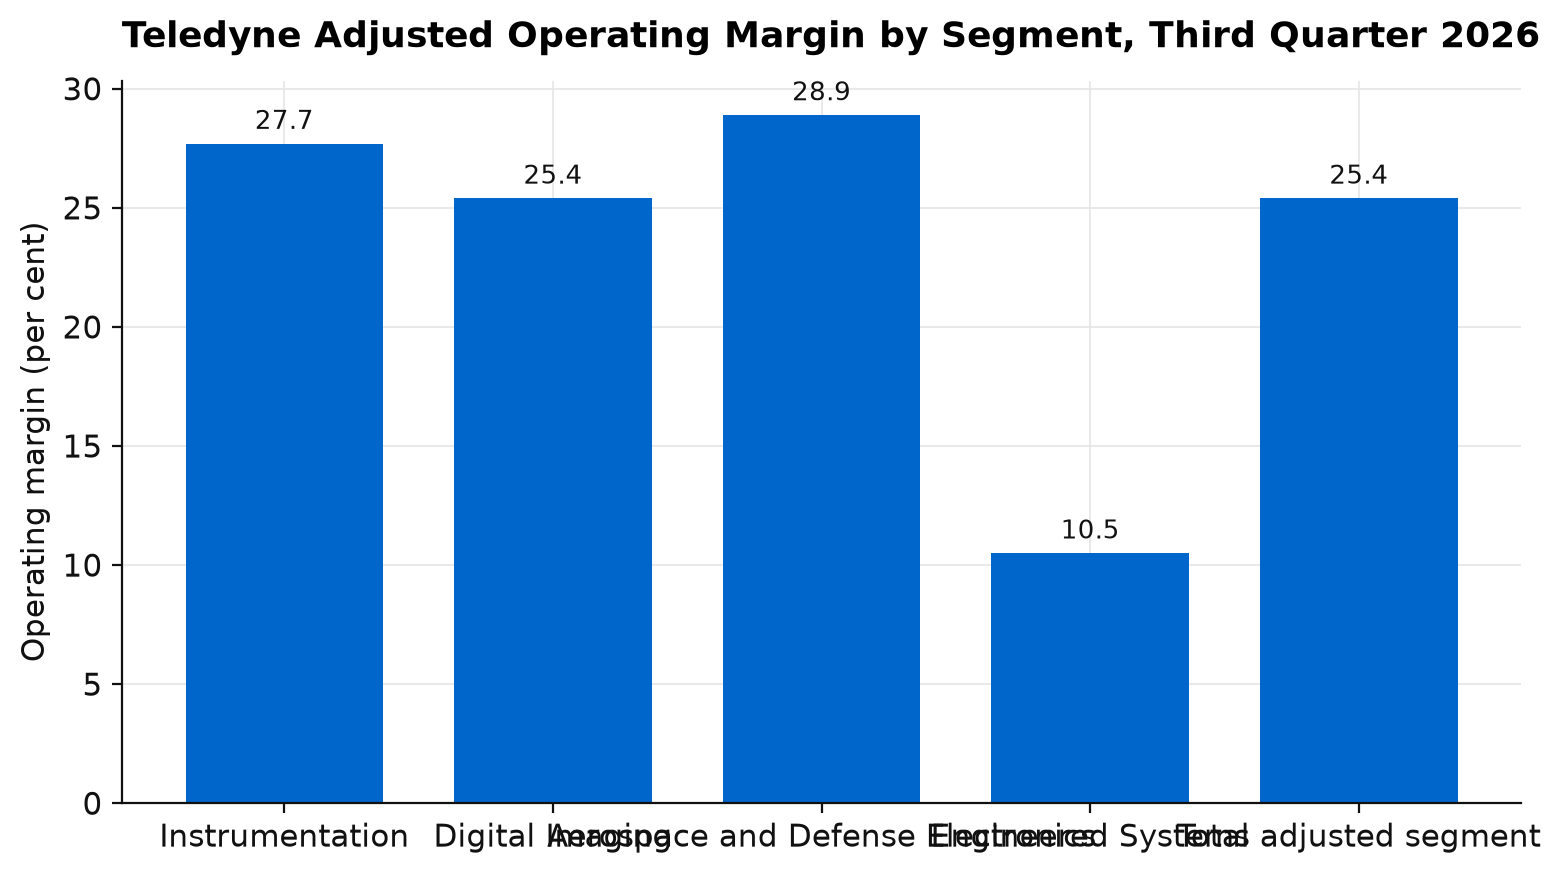
The adjusted segment operating margin, which measures how many cents of operating profit the four segments earn from each dollar of sales, came in at 25.4 per cent against an institutional sell-side estimate of 24.4 per cent. Instrumentation, Digital Imaging and Aerospace and Defense Electronics all beat on margin. Put together, segment earnings before interest and tax were 7 per cent above the institutional sell-side forecast.
Teledyne issued fourth quarter 2026 EPS guidance of US$6.60 to US$6.70, above consensus of US$6.50. It also raised its full-year 2026 EPS guidance to US$25.40 to US$25.50, up from a prior range of US$24.45 to US$24.65. Consensus before the result sat at US$24.74, so the new range is well above what the market expected. With one quarter left in the year, management already has a good view of its orders and production, so the higher range is a fair guide to how the fourth quarter is tracking.
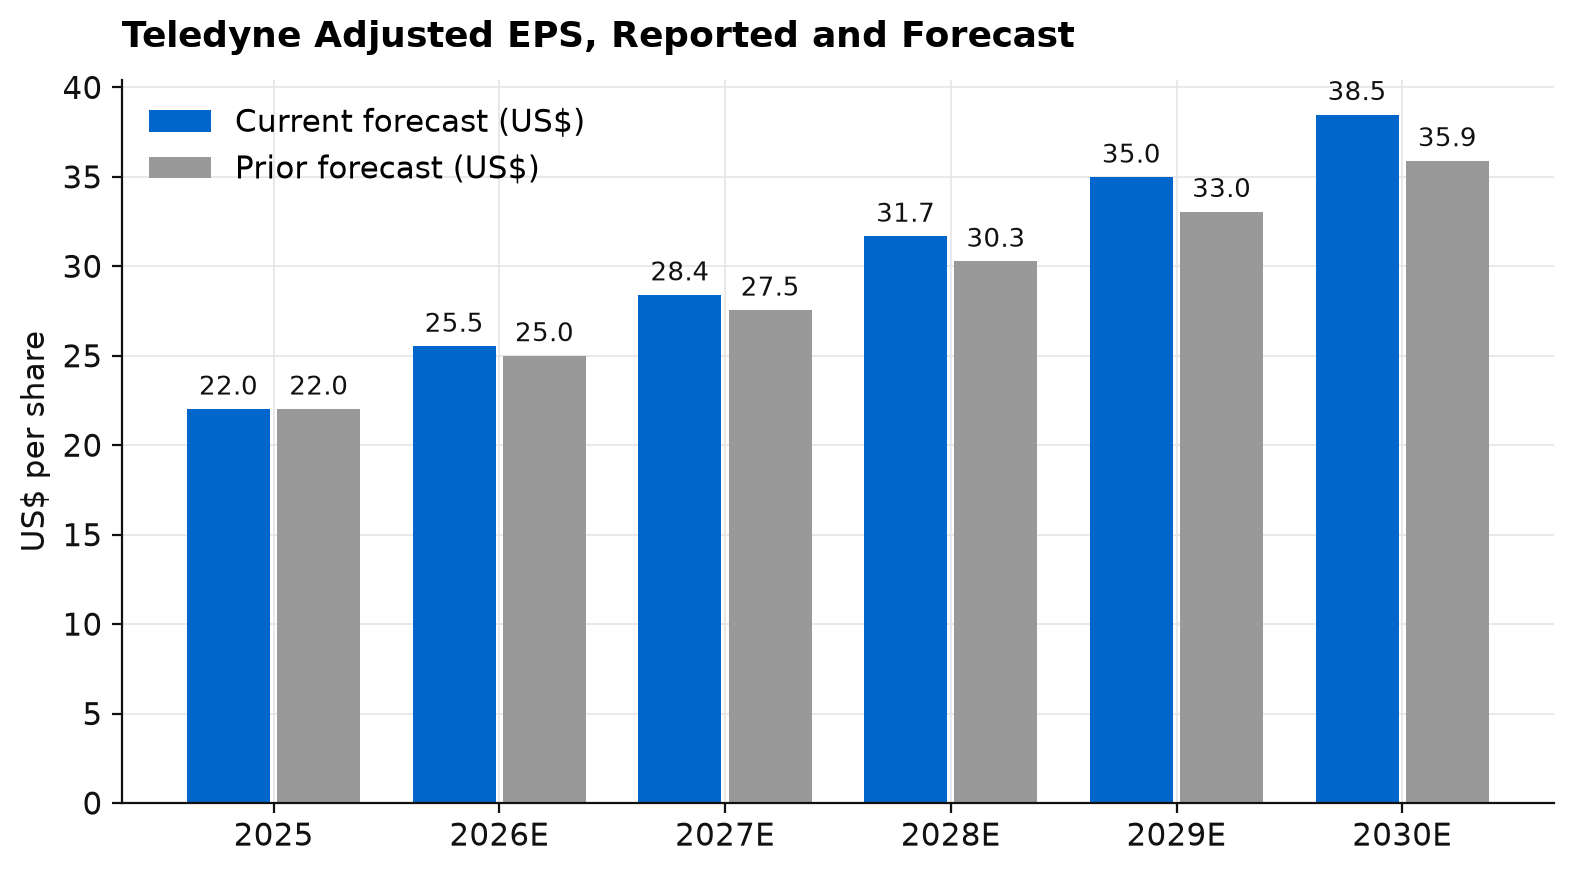
Institutional sell-side research has followed the company higher. Its adjusted EPS forecasts for 2026, 2027 and 2028 move to US$25.52, US$28.39 and US$31.67, from US$24.99, US$27.54 and US$30.27 previously, and the further-out forecasts for 2029 and 2030 rise to US$34.97 and US$38.47 from US$33.05 and US$35.89. Revenue forecasts were lifted too, to US$6,624.6mn for 2026, US$7,099.5mn for 2027 and US$7,534.0mn for 2028, against 2025 revenue of US$6,115.4mn. The research attributes the changes to revised segment growth and margin assumptions. Forecast EPS rises every year from a 2025 base of US$22.01, and the result lifted the forecast for each of those years. Those upgrades are the main reason for the Buy rating.
Digital Imaging Drove Most of the Growth
Teledyne grew 9 per cent organically in the quarter, which counts only the businesses it already owned and leaves out acquisitions. For a company that buys businesses as a core part of its strategy, that is the cleaner measure, and institutional sell-side research names Digital Imaging as the main driver.
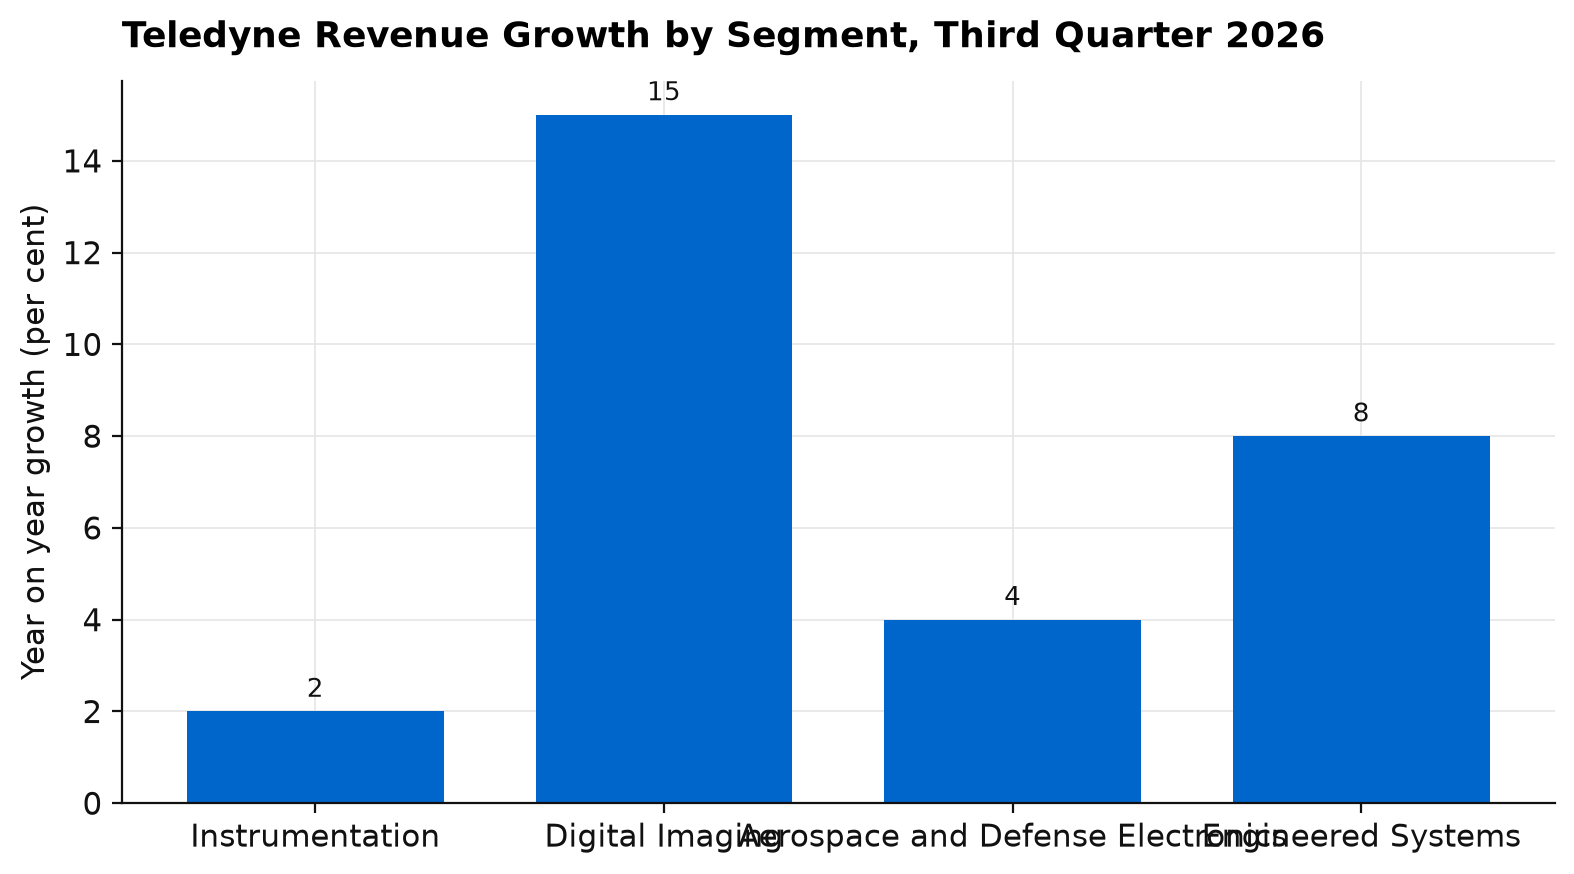
Digital Imaging revenue reached US$903mn, up 15 per cent year on year and 8 per cent above the institutional sell-side estimate. Teledyne pointed to higher sales of infrared imaging detectors, components, surveillance systems, imaging systems and X-ray products. With more than half of the quarter’s group revenue coming from this one segment, its 15 per cent rise accounts for most of the company’s overall growth.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CARGrowth in the other three segments was slower. Instrumentation revenue of US$371mn rose 2 per cent year on year, with higher environmental instrumentation sales partly offset by lower sales of electronic test and measurement instrumentation, and it came in 3 per cent below the institutional sell-side estimate. Aerospace and Defense Electronics revenue of US$287mn increased 4 per cent, helped by strong defense electronics sales, though it was 2 per cent below estimate. Engineered Systems, the smallest segment, lifted revenue 8 per cent to US$124mn on higher sales of engineered products, 3 per cent ahead of estimate.
Institutional sell-side research sees emerging strength in Teledyne’s commercial businesses, while its defense products increasingly sell into faster-growing end markets. Because Teledyne sells to both defense and commercial customers, it does not rely on one source of demand. Instrumentation was soft this quarter, and the group still beat.
Margins and Cash Flow Improved
The adjusted segment operating margin of 25.4 per cent was 100 basis points above the institutional sell-side estimate and up 190 basis points on a year earlier. A basis point is one hundredth of a percentage point, so 190 basis points is 1.9 percentage points, a large step for a business with revenue of US$1.68bn a quarter.
Digital Imaging again led. Its margin of 25.4 per cent was 170 basis points above estimate and up 370 basis points year on year, which the company put down to higher volumes and a favourable product mix. Fixed costs do not rise with every sale, so extra volume flows through to profit, and selling more of the higher-priced products adds to that. Aerospace and Defense Electronics posted the highest margin in the group at 28.9 per cent, 90 basis points above estimate and up 80 basis points, also on higher volumes. Instrumentation’s margin of 27.7 per cent was 30 basis points above estimate but down 40 basis points year on year on unfavourable product mix, and Engineered Systems ran at 10.5 per cent, 50 basis points below estimate and down 10 basis points on program mix.
Free cash flow is the cash a business has left after paying its running costs and investing in equipment and facilities, and it is the money that funds acquisitions, debt repayment or returns to shareholders. Adjusted free cash flow in the quarter was US$320mn, up from US$314mn a year earlier, even as capital expenditure rose to US$33mn from US$29mn. Institutional sell-side research notes that Teledyne’s margin performance and free cash conversion have long been solid and are now strengthening.
Teledyne ended the quarter with US$562mn in cash and cash equivalents, or US$11.99 per share, and institutional sell-side research says the balance sheet has plenty of room to keep buying businesses. Its forecasts also show net debt shrinking relative to earnings across 2026, 2027 and 2028.
Valuation and the Case for a Re-Rate
The 12 month price target of US$915.00 sits about 37.5 per cent above the share price of US$665.56 when this research was published. Institutional sell-side research raised the target from US$877 after the result, reflecting the higher earnings forecasts that came out of the quarter. Despite the strong result, Teledyne trades below its long-run historical average valuation.
Adjusted EPS is forecast to climb from US$25.52 in 2026 to US$28.39 in 2027 and US$31.67 in 2028, each figure higher than before the result. Digital Imaging needs to keep leading the margin gains, after higher volumes and better mix lifted its margin 370 basis points in a single year. Cash flow and the balance sheet also leave room for more acquisitions on top of organic growth.
We think the upside outweighs the risks if Teledyne keeps executing as it did this quarter. For investors wanting exposure to defense and industrial technology, we think now is a reasonable time to start building a position. Further earnings upgrades are the most likely thing to lift the shares.
Key Risks
The first risk is policy, because the defense side of the business is exposed to US Department of Defense spending priorities, and a shift in where that budget goes could slow Aerospace and Defense Electronics. The second risk is valuation. Institutional sell-side research lists premium valuation as a key risk. The shares are cheaper than their own long-run average, but slower growth would still leave them exposed. Within the group, Instrumentation was the soft spot in the quarter, with revenue 3 per cent below the institutional sell-side estimate, lower electronic test and measurement sales and a margin that fell 40 basis points on unfavourable product mix. Execution matters in Engineered Systems too, where the margin slipped to 10.5 per cent on program mix and sits well below the rest of the group. The main company-specific risk is how Teledyne deploys its capital. Teledyne’s growth relies on acquisitions, and overpaying for a deal or failing to integrate one would dilute the returns that have made the platform successful. Finally, much of the guidance upgrade rests on Digital Imaging continuing at the pace it set this quarter, so any slowdown in that segment would weigh on the forecast path.
Our View
Revenue, margin and earnings all beat, cash flow grew, and guidance went up for the next quarter and the full year. Beating on all three lines and then raising guidance is a stronger signal about the underlying business than any single beat.
There are also a few things we would like to see from here. Teledyne has a balance sheet with room to spare, and the research is clear that acquisitions are part of the plan. We would like to see that capacity used patiently, on deals that fit the existing segments. Capital deployment is what we will watch most closely, because one poorly priced deal would dilute the returns. We will also watch Instrumentation. It is a high-margin segment, and a return to growth in electronic test and measurement would spread the strength beyond Digital Imaging. For now, this quarter supports the Buy case.
If you would like to discuss Teledyne, request a callback or call us on 1300 889 603.
Financial Summary
Learn to trade with a plan
Our free 5-day course covers entries, exits and risk management.
Start the free courseBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR