

Buy
Accent Group is an Australian consumer retailer listed on the Australian Securities Exchange that earns most of its profit over Christmas and is expanding its Sports Direct business.
Institutional sell-side research rates it Buy because the softer trading update is already reflected in lower forecasts and a lower target, including some of the currency hedging benefit going into promotions and stock clearance. The shares trade at about a 40 per cent discount to closest listed peer Universal Store on forecast earnings, and the trailing dividend yield is 6.9 per cent, fully franked.
- Sell-side rating
- Buy
- Sell-side target
- A$0.80
- Upside to target
- +23.1%
- Initial price
- A$0.6523 Nov 2026
- Last close
- A$0.6520 Nov 2026
Accent Group has released a trading update that was softer than expected, with sales slowing just ahead of Christmas, the period that produces most of its annual profit. Management pointed to elevated fuel prices, the November interest rate rise and weak consumer confidence. Like-for-like sales are now falling, and the research has cut its operating profit forecasts for the 2027 to 2029 financial years by up to 9 per cent. Institutional sell-side research has Accent rated Buy with a 12 month price target of A$0.80, about 23.1 per cent above the share price of A$0.65 when this research was published. The target has come down from A$0.85, and the Buy rating is unchanged.
Research published 23 November 2026. Price target and upside based on prices at time of publication.
Table of contents [hideshow]
About Accent Group
Accent Group is an Australian consumer retailer listed on the Australian Securities Exchange under the code AX1. The company reports on a financial year ending in June. In the 2026 financial year it generated revenue of A$1,539.2 million and EBITDA of A$278.9 million. EBITDA means earnings before interest, tax, depreciation and amortisation, a rough measure of the profit the stores and operations generate before financing costs and accounting charges. Accent reports its trading through like-for-like retail sales, which compare sales in existing stores with the same weeks a year earlier. Most of its profit is earned in the first half of the financial year, which includes Christmas. Currency hedging has supported its gross margin so far this financial year, and the company is expanding its Sports Direct business.
A Softer Trading Update Than Expected
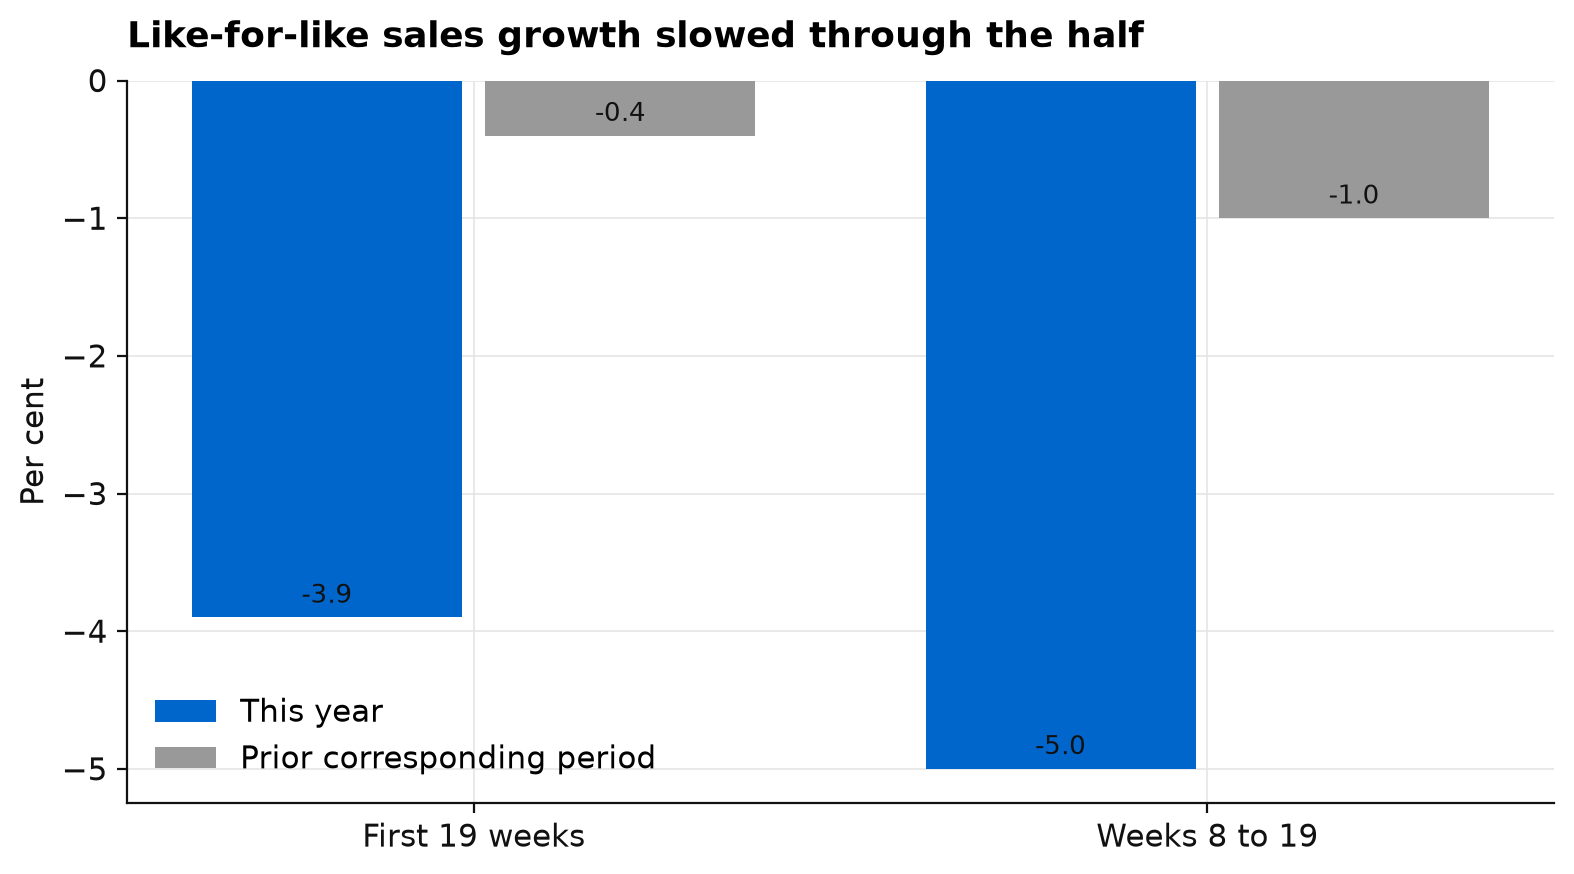
Like-for-like retail sales fell 3.9 per cent over the first 19 weeks of the financial year. Like-for-like, often shortened to LFL, compares sales in existing stores with the same period a year earlier, so it leaves out the effect of opening or closing stores. A negative figure means the existing business is selling less than it did a year ago. In the same 19 weeks a year earlier, the decline was only 0.4 per cent.
Trading also weakened as the half went on. Over weeks 8 to 19, the most recent stretch, like-for-like sales fell 5.0 per cent, a steeper fall than across the full 19 weeks. That compares with a decline of around 1 per cent in the same weeks a year earlier, on institutional sell-side estimates.
Management put the slowdown down to three pressures on shoppers: elevated fuel prices taking money out of household budgets, the November interest rate rise adding to mortgage costs, and weak consumer confidence leading people to put off purchases they can delay.
Christmas Comparisons Get Harder From Here
November and December are the most important trading months for Accent, and they now face a harder comparison. In the same two months a year ago, like-for-like sales grew by around 5 per cent, so Accent has to match a strong period just to keep sales flat. After a 5.0 per cent decline in the most recent weeks, matching last year’s Christmas will need a clear improvement in spending.
Most of Accent’s profit comes from the half that includes Christmas. In the half to December 2025 it earned A$0.05 of earnings per share (EPS, net profit divided by the number of shares on issue), against A$0.01 in the half to June 2026. The research forecasts the same pattern this year, with A$0.05 in the half to December 2026 and A$0.01 in the half to June 2027. With the second half contributing so little, a weak Christmas would be hard to make up later in the year.
A rules-based approach to leveraged ETFs
See how our quantitative strategy works and who it suits.
Explore the strategyBecome an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR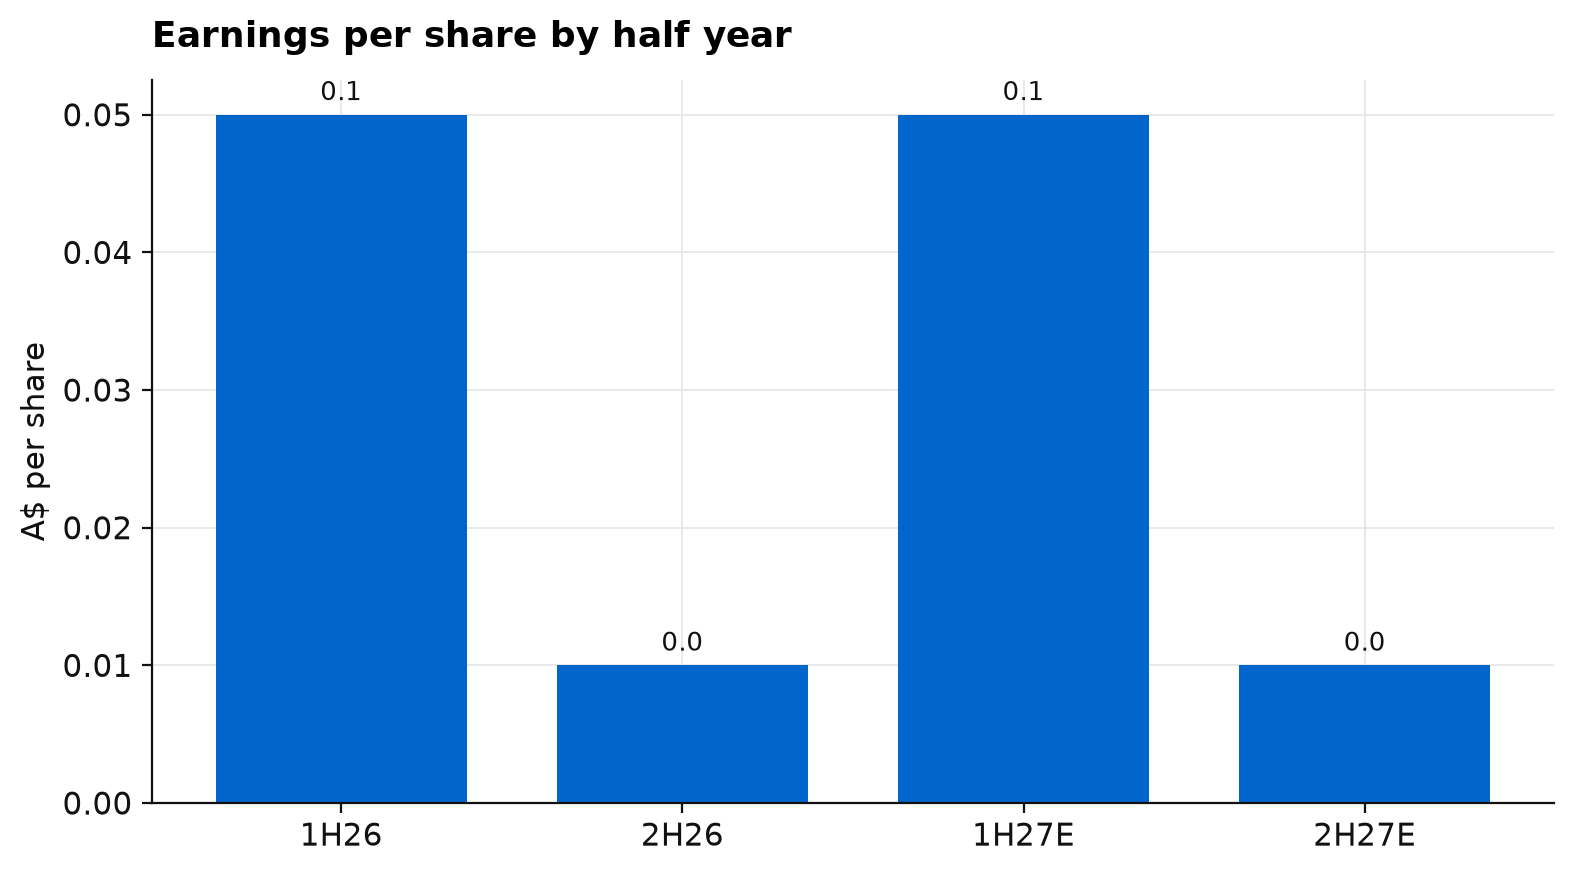
Margins and Earnings Reset Lower
Gross margin, the share of each dollar of sales left after paying for the goods sold, has improved so far this financial year. Accent’s currency hedging has helped, because it fixes exchange rates ahead of time on stock bought in foreign currency.
The research expects some of that benefit to be spent. With sales running below plan, it expects more promotions and a greater chance of clearing stock at lower prices, both of which eat into gross margin. The research still forecasts gross margin to rise this year, but by much less than it expected before the update.
Softer sales and a smaller margin gain have led the research to cut its EBIT forecasts for the 2027 to 2029 financial years by between 1 and 9 per cent. For the 2027 financial year, EBIT (earnings before interest and tax, the operating profit before financing costs and tax) is now forecast at A$86 million.
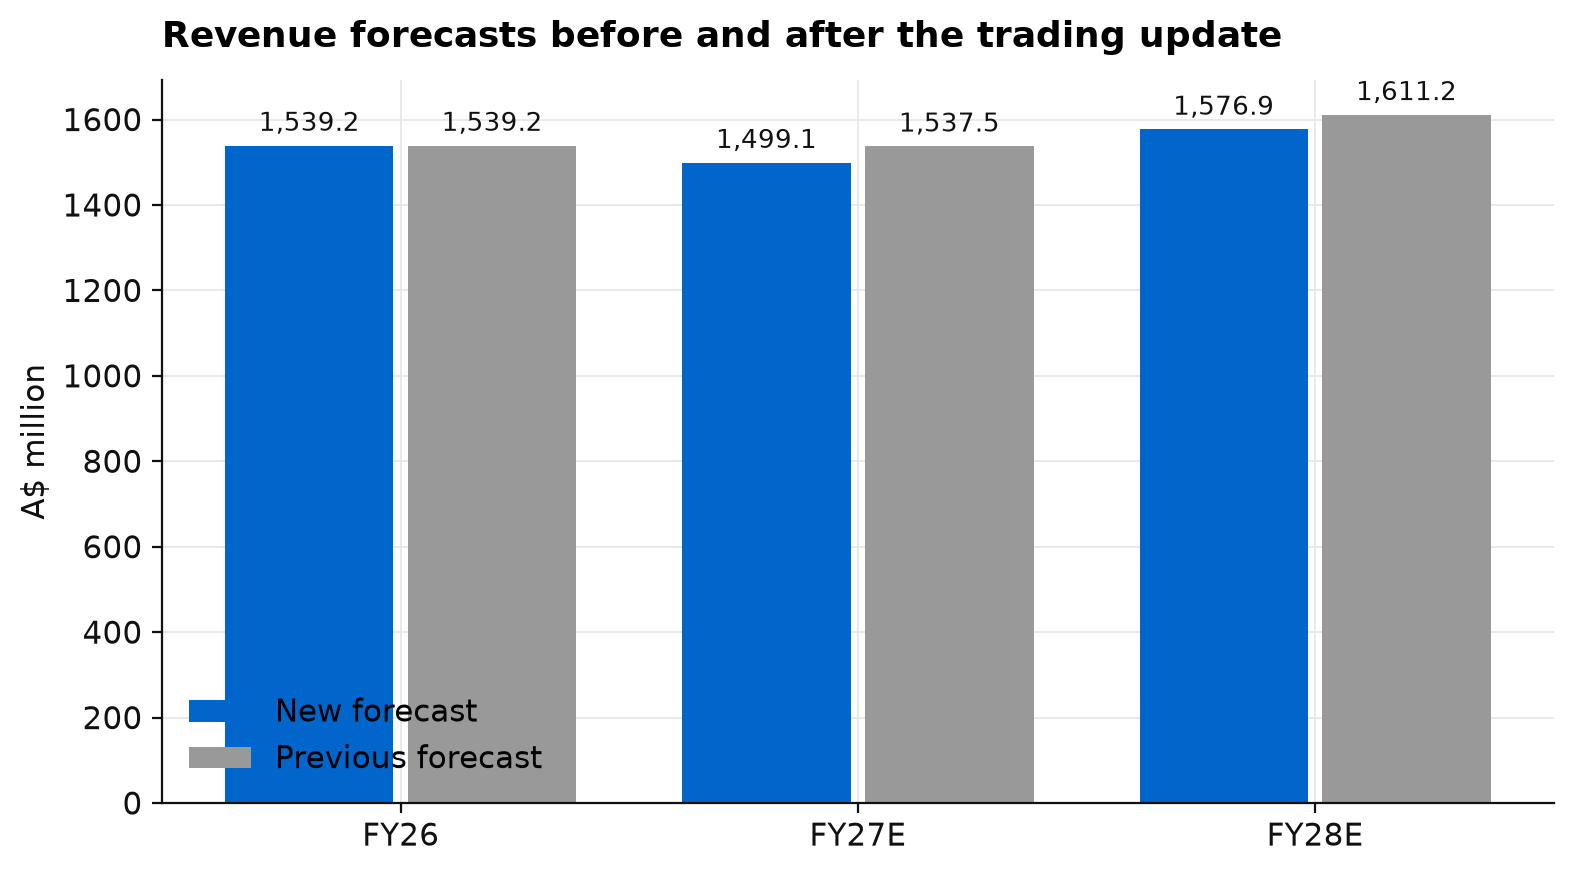
Revenue for the 2027 financial year is now forecast at A$1,499.1 million, down from A$1,537.5 million before the update and below the A$1,539.2 million reported in the 2026 financial year. For the 2028 financial year the forecast is now A$1,576.9 million, against A$1,611.2 million previously. The 2029 financial year is forecast at A$1,668.6 million.
Earnings per share forecasts have moved by less, with the 2027 forecast easing to A$0.06 from A$0.07 and the 2028 forecast unchanged at A$0.08, the same figure forecast for 2029. EBITDA is forecast at A$275.7 million in the 2027 financial year, rising to A$297.9 million in 2028 and A$316.4 million in 2029. Cash return on cash invested (CROCI), which measures the cash the business generates relative to the capital tied up in it, is forecast at 18.5 per cent in the 2027 financial year and 18.9 per cent in both 2028 and 2029, compared with 20.0 per cent in 2026.
Valuation After the Earnings Reset
Following the cut to forecasts, the 12 month price target has been lowered to A$0.80, from A$0.85. At the share price of A$0.65, that target sits about 23.1 per cent above the share price.
The research sets its target using an equal blend of two methods. One is a discounted cash flow valuation over ten years. The other applies a multiple to forecast EBIT for the 2027 financial year. That multiple sits below the level for other Australian discretionary retailers, because Accent earns a lower return on the capital it invests. The research also notes that Accent shares trade at about a 40 per cent discount to their closest listed peer, Universal Store, on price to forecast earnings over the next twelve months.
Over the past twelve months Accent has paid dividends of A$0.045 per share, a trailing dividend yield of 6.9 per cent at the current share price, fully franked, meaning company tax has already been paid on those profits and shareholders receive a credit for it. An SMSF can use those credits to reduce the tax it pays, and receives any excess as a refund. Dividends depend on profits, so a weaker year could affect future payments.
Key Risks
The research lists three key risks: market share losses, if competitors win customers from Accent during the downturn; an unsuccessful Sports Direct expansion, which would tie up capital without delivering the sales and earnings expected; and promotional intensity staying elevated, which would erode the margin gains from currency hedging further than currently forecast.
Our View
Like-for-like sales fell 5.0 per cent in the latest stretch, and November and December still face a comparison of around 5 per cent growth. The research’s lower forecasts and target already allow for the softer update, including some of the currency hedging benefit going into promotions and stock clearance, and further discounting would pressure the margin forecast. Next to watch are Christmas trading and the Sports Direct expansion, one of the research’s key risks.
If you would like to discuss Accent, request a callback or call us on 1300 889 603.
Financial Summary
Become an authorised representative
Advise your clients under an established AFSL without building your own. Choose AR or CAR.
Become an AR or CAR